Council Agenda item 13A
Staff Report: City Manager, Treasurer, Clerk, Planning & Zoning, Department of Public Works, Engineer, Police
City Council, Monday, July 13, 2026
Download these 49 pages, 1.8 MB Whole packet, 121 pages, 22.6 MB
Page 71
Text of page 71
City Manager Report July 13, 2026
Maple Street Construction Update • Water main crossing the 16” sewer force mains was completed on 7/7. • The second stretch of water main from Allegan Street north has been installed, tested, and approved. • The remaining 200 ft of the third stretch of water main will be completed this week. • Water services to homes and businesses are being finished this week south of Allegan Street. Water services north of Allegan Street are scheduled for next week. • Water main tie-in at State Street and/or Blue Star Highway planned for this week or next week. o For the water main tie-in at Blue Star Highway and Maple Street, a line stop will be utilized to cut in the planned tee and valves without an excessive shut off area. The additional cost will be split between the Township and the City. • Water main tie-in on north side of Allegan Street will be done this week or next week. • Once mainline water main is complete, Schippers will move to installing the underground storage and the storm sewer (starting on the south end of the Maple Street). • Mail delivery has been a challenge. Several residents have indicated inconsistent delivery. If this continues, mailbox banks will be utilized to aid in mail delivery. • A reminder that if your constituents have questions, please have them contact the following: o Public Works - Michelle Gibson, Project Coordinator - (269) 224-9504 o Fleis & VandenBrink Engineering Jon Moxey, P.E., Project Manager – (616) 588-1925 Peter Tierney, P.E., Project Manager – (616) 914-8621 Oval Beach Internet and Credit Card Payments • Frontier (now under Verizon) hasn’t yet extended fiber out to Oval Beach. I have remained in contact with their government affairs representative about the need for the service. Frontier advised they were unable to secure approval from Consumes to attach to their poles and that is the reason for the delay. They have been evaluating underground options, and I hope to receive another update soon. • I reached out to Comcast to inquire about options to run service to Oval Beach. The construction cost is quite substantial and would be a cost that would have to be paid back by the City over a five-year period.
Page 72
Text of page 72
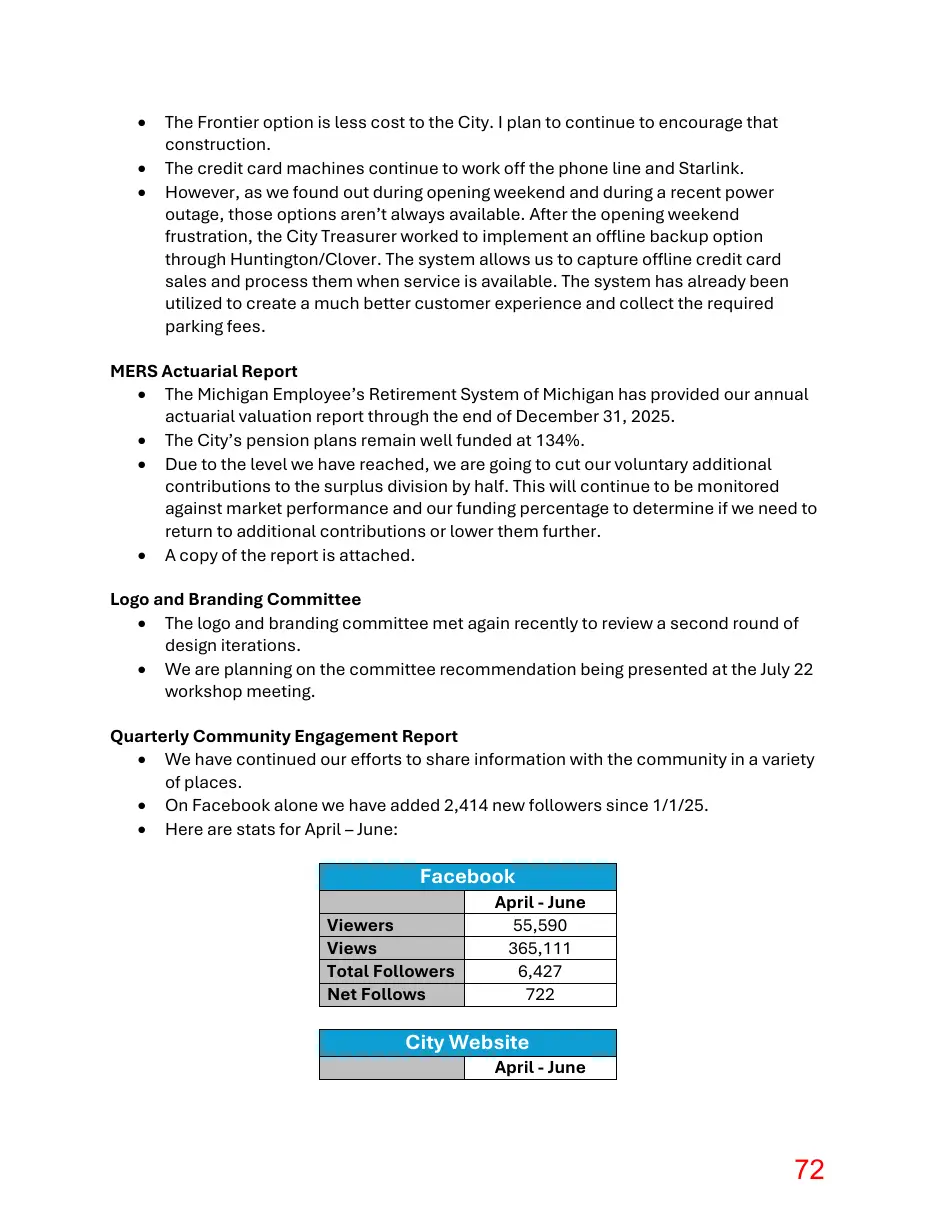
The Frontier option is less cost to the City. I plan to continue to encourage that construction. The credit card machines continue to work off the phone line and Starlink. However, as we found out during opening weekend and during a recent power outage, those options aren’t always available. After the opening weekend frustration, the City Treasurer worked to implement an offline backup option through Huntington/Clover. The system allows us to capture offline credit card sales and process them when service is available. The system has already been utilized to create a much better customer experience and collect the required parking fees.
MERS Actuarial Report • The Michigan Employee’s Retirement System of Michigan has provided our annual actuarial valuation report through the end of December 31, 2025. • The City’s pension plans remain well funded at 134%. • Due to the level we have reached, we are going to cut our voluntary additional contributions to the surplus division by half. This will continue to be monitored against market performance and our funding percentage to determine if we need to return to additional contributions or lower them further. • A copy of the report is attached. Logo and Branding Committee • The logo and branding committee met again recently to review a second round of design iterations. • We are planning on the committee recommendation being presented at the July 22 workshop meeting. Quarterly Community Engagement Report • We have continued our efforts to share information with the community in a variety of places. • On Facebook alone we have added 2,414 new followers since 1/1/25. • Here are stats for April – June:
Facebook Viewers Views Total Followers Net Follows
April - June 55,590 365,111 6,427 722
City Website
April - June
Page 73
Text of page 73
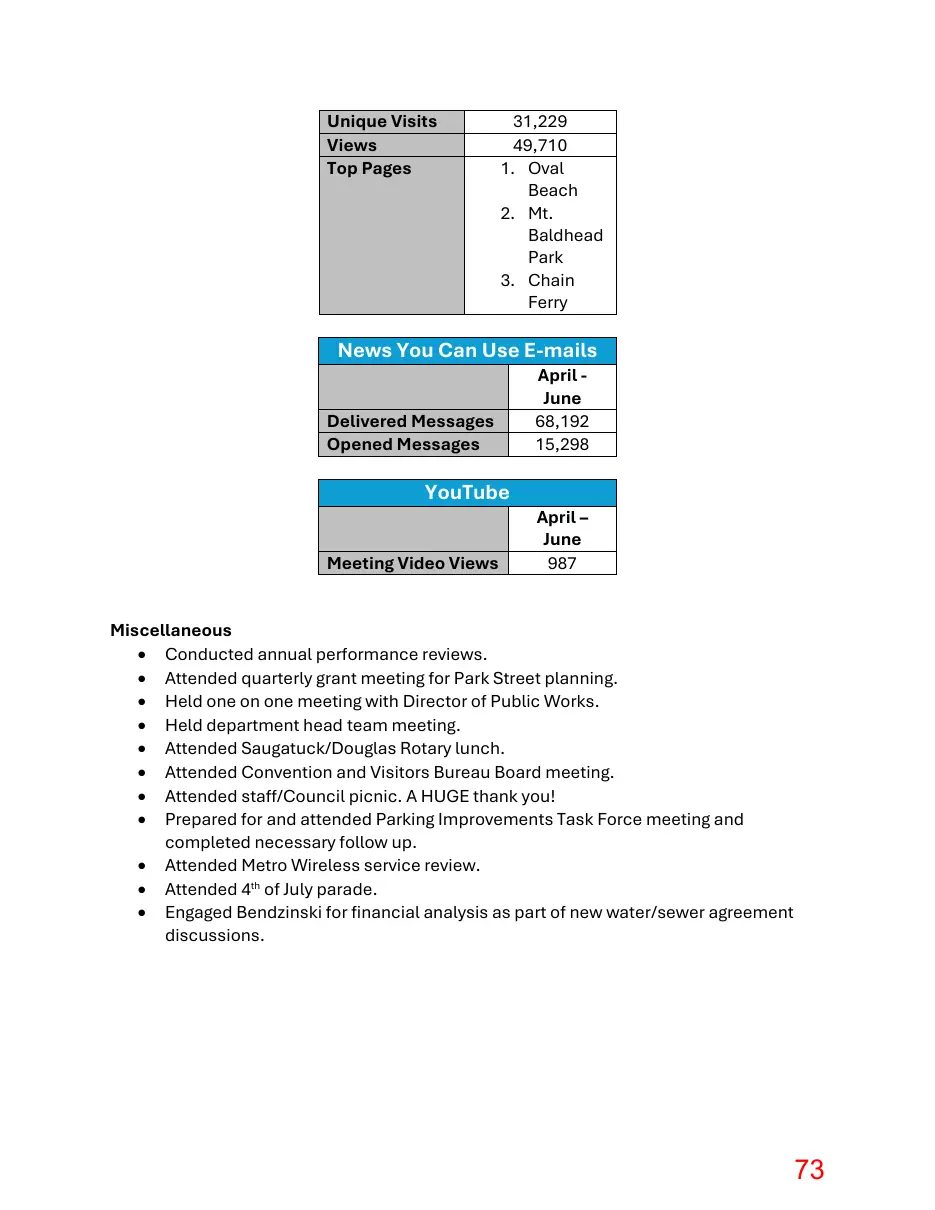
Unique Visits Views Top Pages
31,229 49,710 1. Oval Beach 2. Mt. Baldhead Park 3. Chain Ferry
News You Can Use E-mails Delivered Messages Opened Messages
YouTube Meeting Video Views
April June 68,192 15,298
April – June 987
Miscellaneous • Conducted annual performance reviews. • Attended quarterly grant meeting for Park Street planning. • Held one on one meeting with Director of Public Works. • Held department head team meeting. • Attended Saugatuck/Douglas Rotary lunch. • Attended Convention and Visitors Bureau Board meeting. • Attended staff/Council picnic. A HUGE thank you! • Prepared for and attended Parking Improvements Task Force meeting and completed necessary follow up. • Attended Metro Wireless service review. • Attended 4th of July parade. • Engaged Bendzinski for financial analysis as part of new water/sewer agreement discussions.
Page 74
Text of page 74
Municipal Employees’ Retirement System of Michigan Annual Actuarial Valuation Report December 31, 2025 - Saugatuck, City of (0307)
Page 75
Text of page 75
Spring 2026
Saugatuck, City of In care of: Municipal Employees' Retirement System of Michigan 1134 Municipal Way Lansing, Michigan 48917 This report presents the results of the Annual Actuarial Valuation, prepared for Saugatuck, City of (0307) as of December 31, 2025. The report includes the determination of liabilities and contribution rates resulting from the participation in the Municipal Employees’ Retirement System of Michigan (“MERS”). This report contains the minimum actuarially determined contribution requirement, in alignment with the MERS Plan Document, Actuarial Policy, the Michigan Constitution, and governing statutes. Saugatuck, City of is responsible for the employer contributions needed to provide MERS benefits for its employees and former employees. The purposes of this valuation are to: • • • • •
Measure funding progress as of December 31, 2025, Establish contribution requirements for the fiscal year beginning July 1, 2027, Provide information regarding the identification and assessment of risk, Provide actuarial information in connection with applicable Governmental Accounting Standards Board (GASB) statements, and Provide information to assist the local unit of government with State reporting requirements.
This valuation assumed the continuing ability of the plan sponsor to make the contributions necessary to fund this plan. A determination regarding whether or not the plan sponsor is actually able to do so is outside our scope of expertise and was not performed. The findings in this report are based on data and other information through December 31, 2025. The valuation was based upon information furnished by MERS concerning Retirement System benefits, financial transactions, plan provisions and active members, terminated members, retirees and beneficiaries. We checked for internal reasonability and year-to-year consistency, but did not audit the data. We are not responsible for the accuracy or completeness of the information provided by MERS. The Municipal Employees’ Retirement Act, PA 427 of 1984 and the MERS’ Plan Document Article VI Sec. 71 (1)(d), provides the MERS Board with the authority to set actuarial assumptions and methods after consultation with the actuary. As the fiduciary of the plan, the MERS Retirement Board sets certain assumptions for funding and GASB purposes. These assumptions are reviewed regularly through a comprehensive study, most recently in the Spring of 2025.
Page 76
Text of page 76
Saugatuck, City of Spring 2026 Page 2
The Michigan Department of Treasury provides required assumptions to be used for purposes of Public Act 202, of 2017, reporting. These assumptions are for reporting purposes only and do not impact required contributions. Please refer to the State Reporting page found at the end of this report for information for this filing. For a full list of the assumptions used, please refer to the division-specific assumptions described in table(s) in this report, and to the Appendix on the MERS website at: https://www.mersofmich.com/Portals/0/Assets/Resources/AAV-Appendix/MERS2025AnnualActuarialValuation-Appendix.pdf The actuarial assumptions used for this valuation, including the assumed rate of investment return, are reasonable for purposes of the measurement. The combined effect of the assumptions is expected to have no significant bias (i.e., not significantly optimistic or pessimistic). The asset valuation method is more likely to produce an actuarial value of assets that is greater than the market value of assets until application of the dedicated gains policy achieves an assumed rate of investment return of 6.50% (currently 6.79%). In December 2021, the Actuarial Standards Board (ASB) adopted a revision to the Actuarial Standard of Practice (ASOP) No. 4, Measuring Pension Obligations and Determining Pension Plan Costs or Contributions. The revised ASOP No. 4 requires the calculation and disclosure of a liability referred to by the ASOP as the “Low-Default-Risk Obligation Measure” (LDROM). The LDROM calculation is provided in aggregate, along with aggregate employer results, in a separate report titled “Summary Report of the 80th Annual Actuarial Valuations,” and will be available on the MERS website during the fall of 2026. This report has been prepared by actuaries who have substantial experience valuing public employee retirement systems. To the best of our knowledge, the information contained in this report is accurate and fairly presents the actuarial position of Saugatuck, City of as of the valuation date. All calculations have been made in conformity with generally accepted actuarial principles and practices, the Actuarial Standards of Practice issued by the Actuarial Standards Board, and applicable statutes. Rebecca L. Stouffer, Mark Buis, Kurt Dosson, and Shana M. Neeson are members of the American Academy of Actuaries. These actuaries meet the Academy’s Qualification Standards to render the actuarial opinions contained herein. The signing actuaries are independent of the plan sponsor. GRS maintains independent consulting agreements with certain local units of government for services unrelated to the actuarial consulting services provided in this report. The Retirement Board of the Municipal Employees' Retirement System of Michigan confirms that the System provides for payment of the required employer contribution as described in Section 20m of Act No. 314 of 1965 (MCL 38.1140m). This information is purely actuarial in nature. It is not intended to serve as a substitute for legal, accounting, or investment advice.
Page 77
Text of page 77
Saugatuck, City of Spring 2026 Page 3
This report was prepared at the request of the MERS Retirement Board and may be provided only in its entirety by the municipality to other interested parties. MERS customarily provides the full report on request to associated third parties such as the auditor for the municipality. GRS is not responsible for the consequences of any unauthorized use. This report should not be relied on for any purpose other than the purposes described herein. Determinations of financial results, associated with the benefits described in this report, for purposes other than those identified above may be significantly different. If you have reason to believe that the plan provisions are incorrectly described, that important plan provisions relevant to this valuation are not described, that conditions have changed since the calculations were made, that the information provided in this report is inaccurate or is in anyway incomplete, or if you need further information in order to make an informed decision on the subject matter in this report, please contact your Regional Manager at 1.800.767.MERS (6377). Sincerely, Gabriel, Roeder, Smith & Company
Rebecca L. Stouffer, ASA, FCA, MAAA
Mark Buis, FSA, FCA, EA, MAAA
Kurt Dosson, ASA, FCA, MAAA
Shana M. Neeson, ASA, FCA, MAAA
Page 78
Text of page 78
Table of Contents Executive Summary ................................................................................................................................................. 6 Table 1: Employer Contribution Details for the Fiscal Year Beginning July 1, 2027 ............................................. 13 Table 2: Benefit Provisions .................................................................................................................................... 14 Table 3: Participant Summary ............................................................................................................................... 15 Table 4: Reported Assets (Market Value) ............................................................................................................. 16 Table 5: Flow of Valuation Assets ......................................................................................................................... 17 Table 6: Actuarial Accrued Liabilities and Valuation Assets as of December 31, 2025 ........................................ 18 Table 7: Actuarial Accrued Liabilities - Comparative Schedule ............................................................................. 20 Tables 8 and 9: Division-Based Comparative Schedules ....................................................................................... 21 Table 10: Division-Based Layered Amortization Schedule .................................................................................... 24 GASB Statement No. 68 Information .................................................................................................................... 26 Benefit Provision History ....................................................................................................................................... 27 Plan Provisions, Actuarial Assumptions, and Actuarial Funding Method ............................................................. 28 Risk Commentary .................................................................................................................................................. 29 State Reporting ..................................................................................................................................................... 31
Saugatuck, City of (0307) - 2025
Page 79
Text of page 79
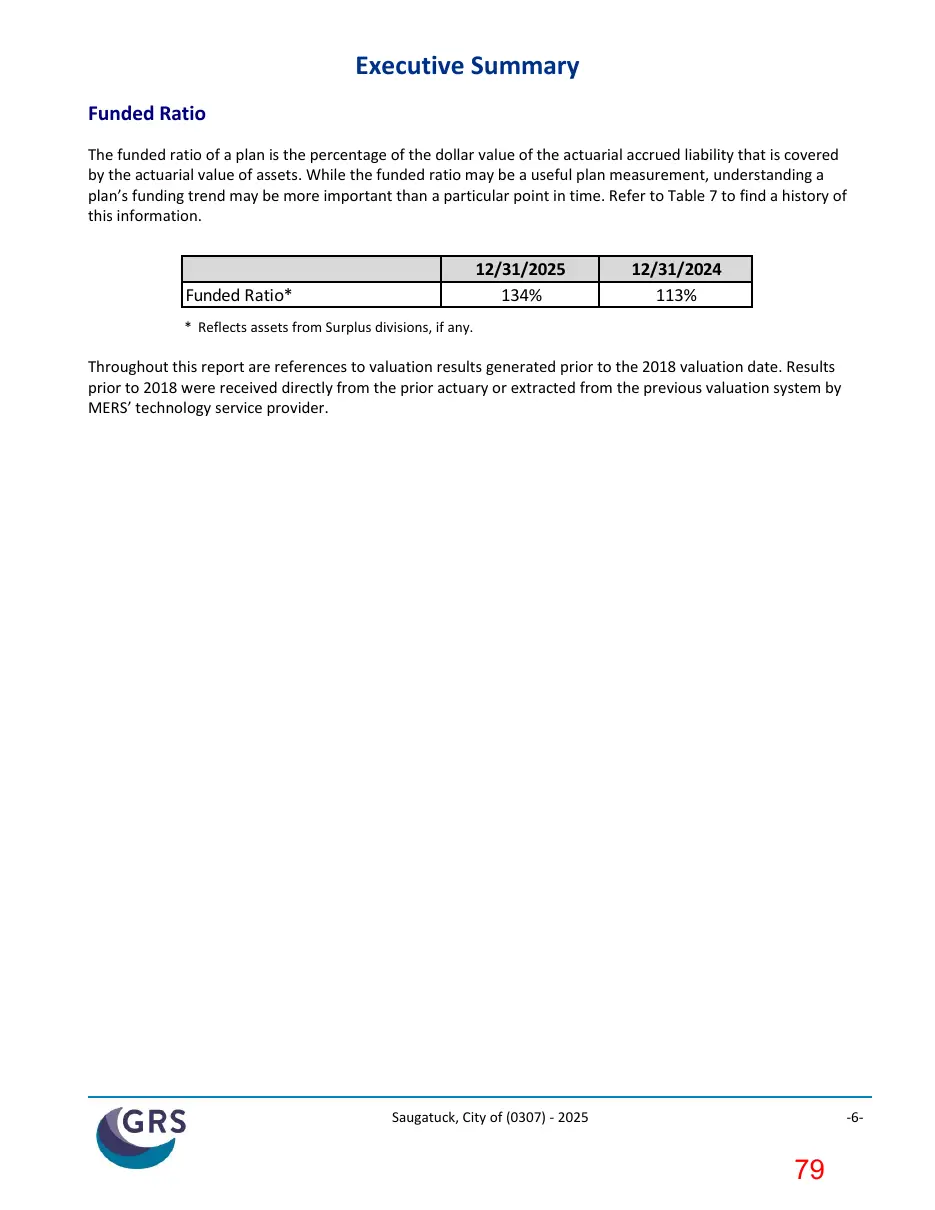
Executive Summary Funded Ratio The funded ratio of a plan is the percentage of the dollar value of the actuarial accrued liability that is covered by the actuarial value of assets. While the funded ratio may be a useful plan measurement, understanding a plan’s funding trend may be more important than a particular point in time. Refer to Table 7 to find a history of this information.
12/31/2025 134%
Funded Ratio*
12/31/2024 113%
* Reflects assets from Surplus divisions, if any.
Throughout this report are references to valuation results generated prior to the 2018 valuation date. Results prior to 2018 were received directly from the prior actuary or extracted from the previous valuation system by MERS’ technology service provider.
Saugatuck, City of (0307) - 2025
Page 80
Text of page 80
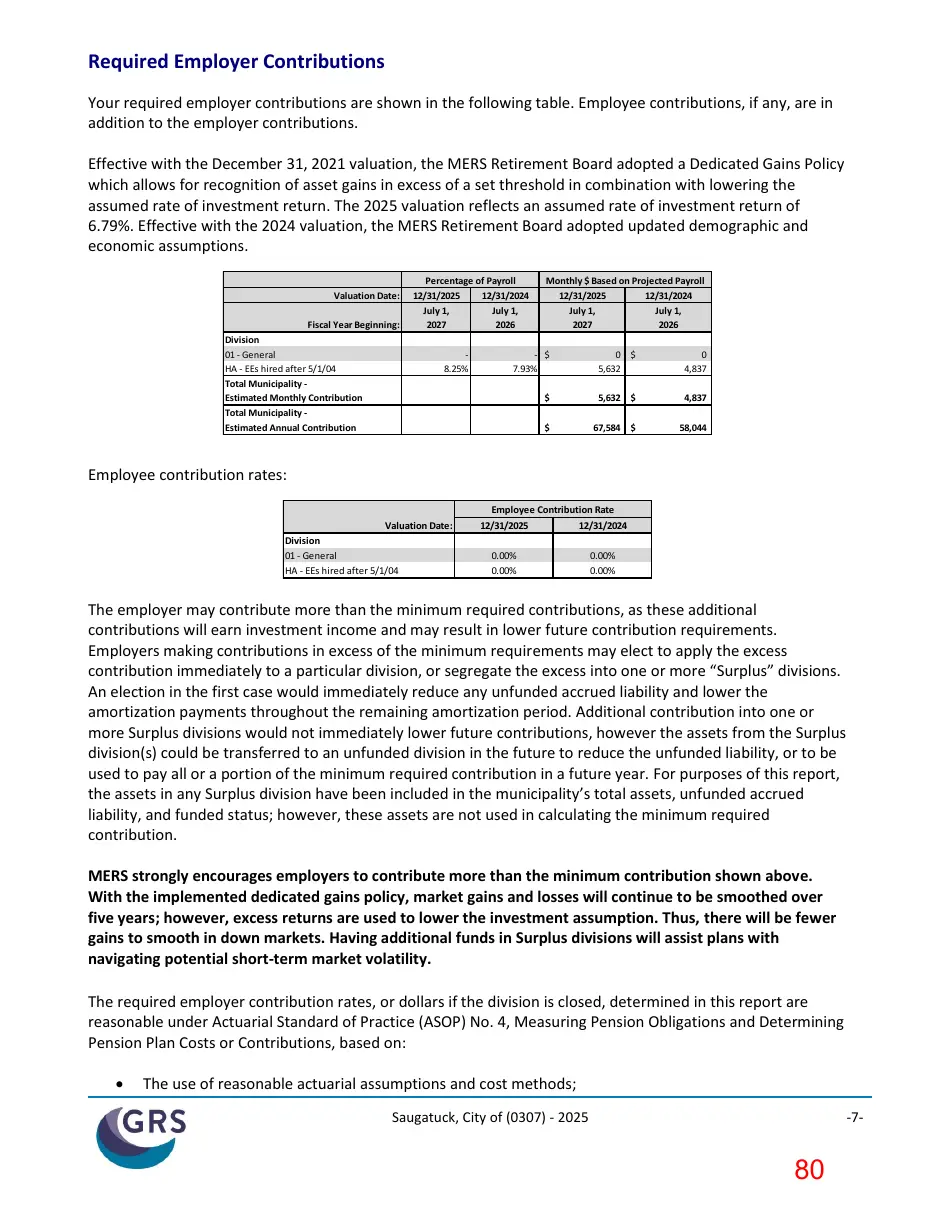
Required Employer Contributions Your required employer contributions are shown in the following table. Employee contributions, if any, are in addition to the employer contributions. Effective with the December 31, 2021 valuation, the MERS Retirement Board adopted a Dedicated Gains Policy which allows for recognition of asset gains in excess of a set threshold in combination with lowering the assumed rate of investment return. The 2025 valuation reflects an assumed rate of investment return of 6.79%. Effective with the 2024 valuation, the MERS Retirement Board adopted updated demographic and economic assumptions. Valuation Date: Fiscal Year Beginning: Division 01 - General HA - EEs hired after 5/1/04 Total Municipality Estimated Monthly Contribution Total Municipality Estimated Annual Contribution
Percentage of Payroll 12/31/2025 12/31/2024 July 1, July 1, 2027 2026 8.25%
Monthly $ Based on Projected Payroll 12/31/2025 12/31/2024 July 1, July 1, 2027 2026
- $ 7.93%
0 $ 5,632
0 4,837
5,632 $
4,837
67,584 $
58,044
Employee contribution rates: Valuation Date: Division 01 - General HA - EEs hired after 5/1/04
Employee Contribution Rate 12/31/2025 12/31/2024 0.00% 0.00%
0.00% 0.00%
The employer may contribute more than the minimum required contributions, as these additional contributions will earn investment income and may result in lower future contribution requirements. Employers making contributions in excess of the minimum requirements may elect to apply the excess contribution immediately to a particular division, or segregate the excess into one or more “Surplus” divisions. An election in the first case would immediately reduce any unfunded accrued liability and lower the amortization payments throughout the remaining amortization period. Additional contribution into one or more Surplus divisions would not immediately lower future contributions, however the assets from the Surplus division(s) could be transferred to an unfunded division in the future to reduce the unfunded liability, or to be used to pay all or a portion of the minimum required contribution in a future year. For purposes of this report, the assets in any Surplus division have been included in the municipality’s total assets, unfunded accrued liability, and funded status; however, these assets are not used in calculating the minimum required contribution. MERS strongly encourages employers to contribute more than the minimum contribution shown above. With the implemented dedicated gains policy, market gains and losses will continue to be smoothed over five years; however, excess returns are used to lower the investment assumption. Thus, there will be fewer gains to smooth in down markets. Having additional funds in Surplus divisions will assist plans with navigating potential short-term market volatility. The required employer contribution rates, or dollars if the division is closed, determined in this report are reasonable under Actuarial Standard of Practice (ASOP) No. 4, Measuring Pension Obligations and Determining Pension Plan Costs or Contributions, based on: •
The use of reasonable actuarial assumptions and cost methods; Saugatuck, City of (0307) - 2025
Page 81
Text of page 81
The use of reasonable amortization and asset valuation methods; and Application of the MERS funding policy which will accumulate sufficient assets to make benefit payments when due, assuming all assumptions will be realized, and the required employer contributions are made when due.
How and Why Do These Numbers Change? In a defined benefit plan, contributions vary from one annual actuarial valuation to the next as a result of the following:
Changes in benefit provisions (see Table 2); Changes in actuarial assumptions and methods (see the Appendix); and Experience of the plan (investment experience and demographic experience); this is the difference between actual experience of the plan and the actuarial assumptions.
These impacts are reflected in various tables in the report. For more information, please contact your Regional Manager.
Comments on Investment Rate of Return Assumption A defined benefit plan is funded by employer contributions, participant contributions, and investment earnings. Investment earnings have historically provided a significant portion of the funding. The larger the share of benefits being provided from investment returns, the smaller the required contributions, and vice versa. Determining the contributions required to prefund the promised retirement benefits requires an assumption of what investment earnings are expected to add to the fund over a long period of time. This is called the Investment Return Assumption. The MERS Investment Return Assumption is 6.79% per year. This, along with all other actuarial assumptions, is reviewed at least every five years in an Experience Study that compares the assumptions used against actual experience and recommends adjustments if necessary. If your municipality would like to explore contributions at lower assumed investment return assumptions, please review the “What If” projection scenarios later in this report.
Assumption and Method Changes in 2025 Effective February 17, 2022 and first implemented in the December 31, 2021 annual actuarial valuation, the MERS Retirement Board adopted a dedicated gains policy that automatically lowers the assumed rate of investment return by using excess asset gains to mitigate large increases in required contributions to the Plan. Full details of this dedicated gains policy are available in the Actuarial Policy found on the MERS website. Some goals of the dedicated gains policy are to: • •
Provide a systematic approach to lower the assumed rate of investment return between experience studies; and Use excess gains to cover both the increase in normal cost and any increase in UAL payment the first contribution year after application (i.e., minimize the first-year impact (i.e., increase) in employer contributions).
Investment performance measured for the one-year period ending December 31, 2025 resulted in current year excess gains for use in lowering the assumed rate of investment return. As a result, the assumed rate of investment return was lowered from 6.93% to 6.79%. The December 31, 2025 valuation liabilities were Saugatuck, City of (0307) - 2025
Page 82
Text of page 82
developed using this new, lower assumption. Additionally, as a result of recognizing excess market gains, the valuation assets used to fund these liabilities are 2.7% higher than if there were no dedicated gains policy. The combined impact of these changes will minimize the first-year impact on employer contributions and may result in an increase or a decrease in employer contributions. There were no other assumption or method changes in 2025.
Comments on Asset Smoothing To avoid dramatic spikes and dips in annual contribution requirements due to short-term fluctuations in asset markets, MERS applies a technique called asset smoothing. This spreads out each year’s investment gains or losses over the prior year and the following four years. After initial application of asset smoothing, any remaining excess market gains are used to buy down the assumed rate of investment return and increase the level of valuation assets, to the extent allowed by the dedicated gains policy. This smoothing method is used to determine your actuarial value of assets (valuation assets), which is then used to determine both your funded ratio and your required contributions. The (smoothed) actuarial rate of return for 2025 was 8.18%, while the actual market rate of return was 15.25%. To see historical details of the market rate of return compared to the smoothed actuarial rate of return, refer to this report’s Appendix or view the “How Smoothing Works” video on the Defined Benefit resource page of the MERS website. As of December 31, 2025, the actuarial value of assets is just over 100% of market value due to asset smoothing and dedicated gains. This means that there are deferred investment losses, which will put slight upward pressure on contributions in the short term. The level of market value of assets and actuarial value of assets are very similar, resulting in a funded percentage that is not materially different.
Alternate Scenarios to Estimate the Potential Volatility of Results ("What If Scenarios") The calculations in this report are based on assumptions about long-term economic and demographic behavior. These assumptions will never materialize in a given year, except by coincidence. Therefore, the results will vary from one year to the next. The volatility of the results depends upon the characteristics of the plan. For example: • • • •
Open divisions that have substantial assets compared to their active employee payroll will have more volatile employer contribution rates due to investment return fluctuations. Open divisions that have substantial accrued liability compared to their active employee payroll will have more volatile employer contribution rates due to demographic experience fluctuations. Small divisions will have more volatile contribution patterns than larger divisions because statistical fluctuations are relatively larger among small populations. Shorter amortization periods result in more volatile contribution patterns.
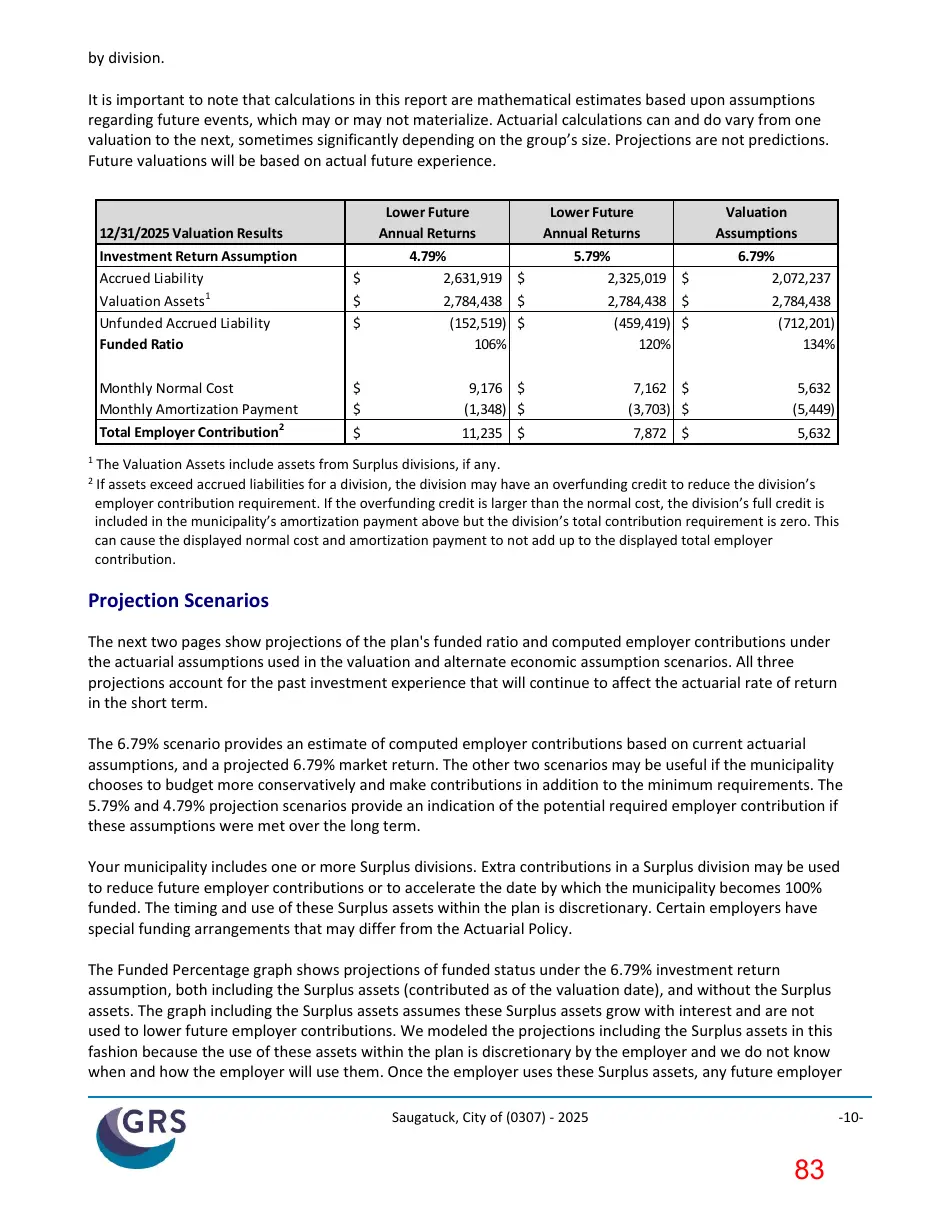
Many assumptions are important in determining the required employer contributions. In the following table, we show the impact of varying the Investment Return assumption. Lower investment returns would generally result in higher required employer contributions, and vice versa. The three economic scenarios below provide a quantitative risk assessment for the impact of investment returns on the plan’s projected financial condition for funding purposes. The relative impact of the economic scenarios below will vary from year to year, as the participant demographics change. The impact of each scenario should be analyzed for a given year, not from year to year. The results in the table are based on the December 31, 2025 valuation and are for the municipality in total, not Saugatuck, City of (0307) - 2025
Page 83
Text of page 83
by division. It is important to note that calculations in this report are mathematical estimates based upon assumptions regarding future events, which may or may not materialize. Actuarial calculations can and do vary from one valuation to the next, sometimes significantly depending on the group’s size. Projections are not predictions. Future valuations will be based on actual future experience.
12/31/2025 Valuation Results Investment Return Assumption Accrued Liability 1
1 2
Lower Future Annual Returns 4.79% 2,631,919 $
Lower Future Annual Returns 5.79% 2,325,019 $
Valuation Assumptions 6.79% 2,072,237
Valuation Assets Unfunded Accrued Liability Funded Ratio
2,784,438 $ (152,519) $ 106%
2,784,438 $ (459,419) $ 120%
2,784,438 (712,201) 134%
Monthly Normal Cost Monthly Amortization Payment Total Employer Contribution2
9,176 $ (1,348) $
7,162 $ (3,703) $
5,632 (5,449)
11,235 $
7,872 $
5,632
The Valuation Assets include assets from Surplus divisions, if any. If assets exceed accrued liabilities for a division, the division may have an overfunding credit to reduce the division’s employer contribution requirement. If the overfunding credit is larger than the normal cost, the division’s full credit is included in the municipality’s amortization payment above but the division’s total contribution requirement is zero. This can cause the displayed normal cost and amortization payment to not add up to the displayed total employer contribution.
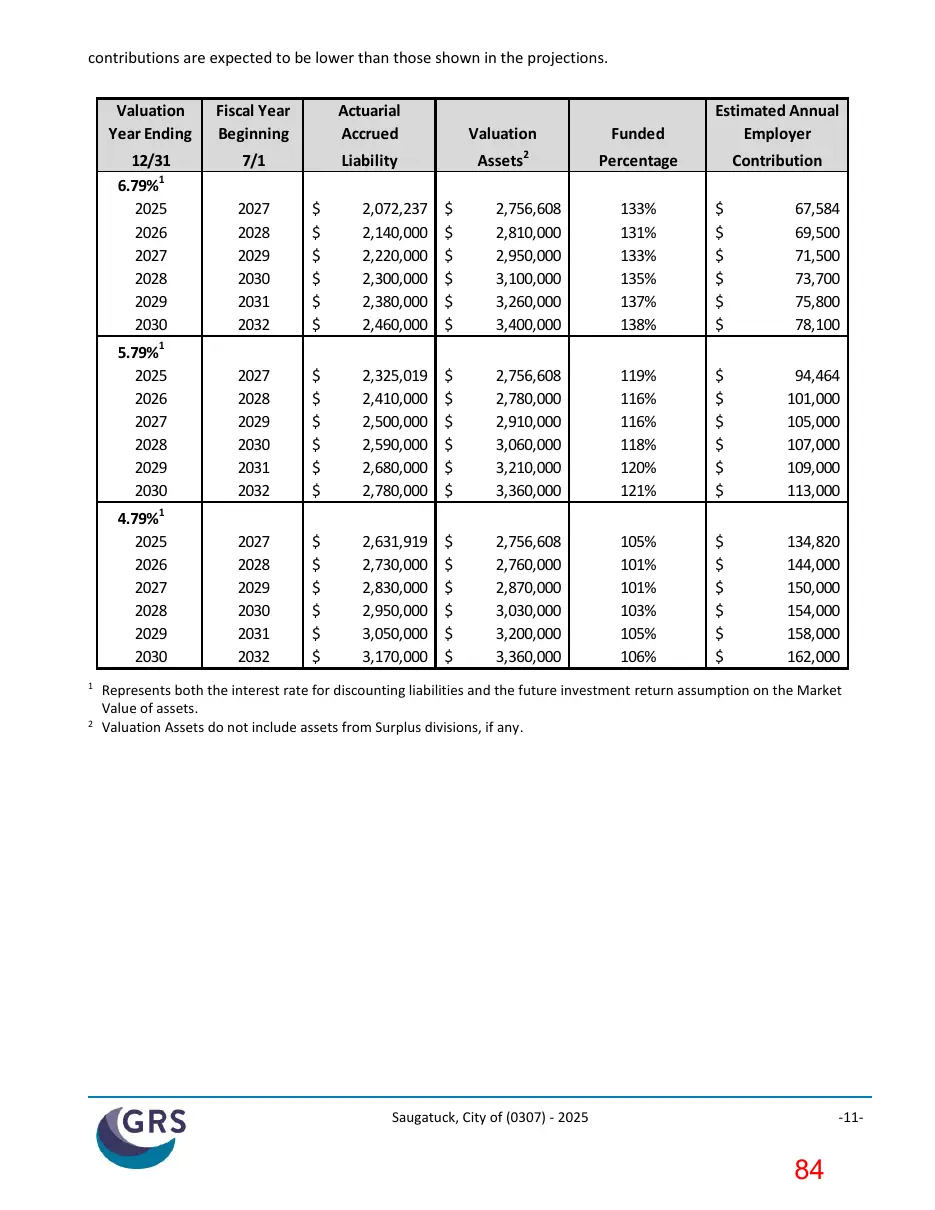
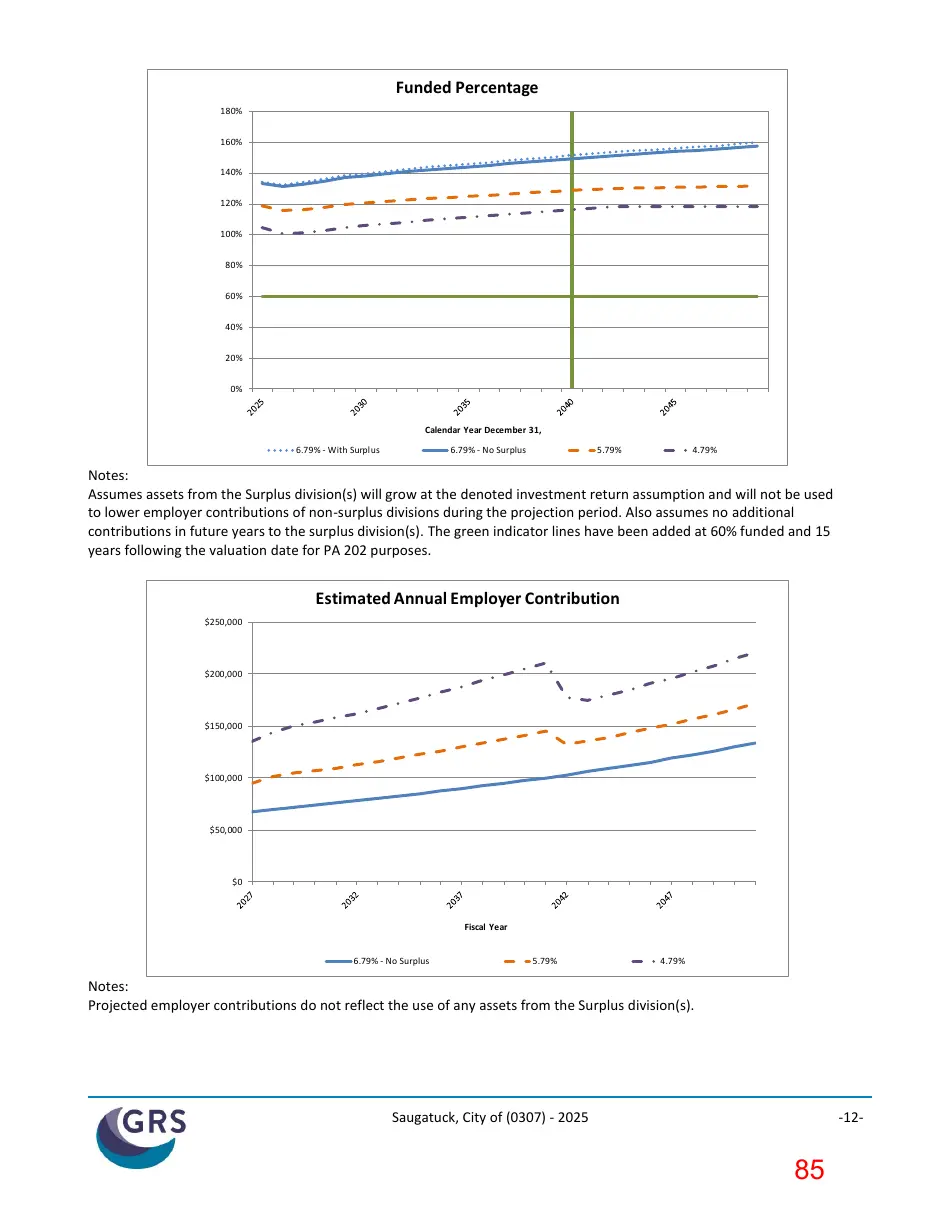
Projection Scenarios The next two pages show projections of the plan's funded ratio and computed employer contributions under the actuarial assumptions used in the valuation and alternate economic assumption scenarios. All three projections account for the past investment experience that will continue to affect the actuarial rate of return in the short term. The 6.79% scenario provides an estimate of computed employer contributions based on current actuarial assumptions, and a projected 6.79% market return. The other two scenarios may be useful if the municipality chooses to budget more conservatively and make contributions in addition to the minimum requirements. The 5.79% and 4.79% projection scenarios provide an indication of the potential required employer contribution if these assumptions were met over the long term. Your municipality includes one or more Surplus divisions. Extra contributions in a Surplus division may be used to reduce future employer contributions or to accelerate the date by which the municipality becomes 100% funded. The timing and use of these Surplus assets within the plan is discretionary. Certain employers have special funding arrangements that may differ from the Actuarial Policy. The Funded Percentage graph shows projections of funded status under the 6.79% investment return assumption, both including the Surplus assets (contributed as of the valuation date), and without the Surplus assets. The graph including the Surplus assets assumes these Surplus assets grow with interest and are not used to lower future employer contributions. We modeled the projections including the Surplus assets in this fashion because the use of these assets within the plan is discretionary by the employer and we do not know when and how the employer will use them. Once the employer uses these Surplus assets, any future employer Saugatuck, City of (0307) - 2025
-10-
Page 84
Text of page 84
contributions are expected to be lower than those shown in the projections.
Valuation Year Ending
Fiscal Year Beginning
Actuarial Accrued
Valuation
Funded
Estimated Annual Employer
12/31 6.79%1 2025 2026 2027 2028 2029 2030
7/1
Liability
Assets2
Percentage
Contribution
2027 2028 2029 2030 2031 2032
2,072,237 2,140,000 2,220,000 2,300,000 2,380,000 2,460,000
2,756,608 2,810,000 2,950,000 3,100,000 3,260,000 3,400,000
133% 131% 133% 135% 137% 138%
67,584 69,500 71,500 73,700 75,800 78,100
5.79%1 2025 2026 2027 2028 2029 2030
2027 2028 2029 2030 2031 2032
2,325,019 2,410,000 2,500,000 2,590,000 2,680,000 2,780,000
2,756,608 2,780,000 2,910,000 3,060,000 3,210,000 3,360,000
119% 116% 116% 118% 120% 121%
94,464 101,000 105,000 107,000 109,000 113,000
4.79%1 2025 2026 2027 2028 2029 2030
2027 2028 2029 2030 2031 2032
2,631,919 2,730,000 2,830,000 2,950,000 3,050,000 3,170,000
2,756,608 2,760,000 2,870,000 3,030,000 3,200,000 3,360,000
105% 101% 101% 103% 105% 106%
134,820 144,000 150,000 154,000 158,000 162,000
Represents both the interest rate for discounting liabilities and the future investment return assumption on the Market Value of assets. 2 Valuation Assets do not include assets from Surplus divisions, if any.
Saugatuck, City of (0307) - 2025
-11-
Page 85
Text of page 85
Funded Percentage 180% 160% 140% 120% 100%
80% 60% 40% 20% 0%
Calendar Year December 31, 6.79% - With Surplus
6.79% - No Surplus
5.79%
4.79%
Notes: Assumes assets from the Surplus division(s) will grow at the denoted investment return assumption and will not be used to lower employer contributions of non-surplus divisions during the projection period. Also assumes no additional contributions in future years to the surplus division(s). The green indicator lines have been added at 60% funded and 15 years following the valuation date for PA 202 purposes.
Estimated Annual Employer Contribution $250,000
$200,000
$150,000
$100,000
$50,000
Fiscal Year
6.79% - No Surplus
5.79%
4.79%
Notes: Projected employer contributions do not reflect the use of any assets from the Surplus division(s).
Saugatuck, City of (0307) - 2025
-12-
Page 86
Text of page 86
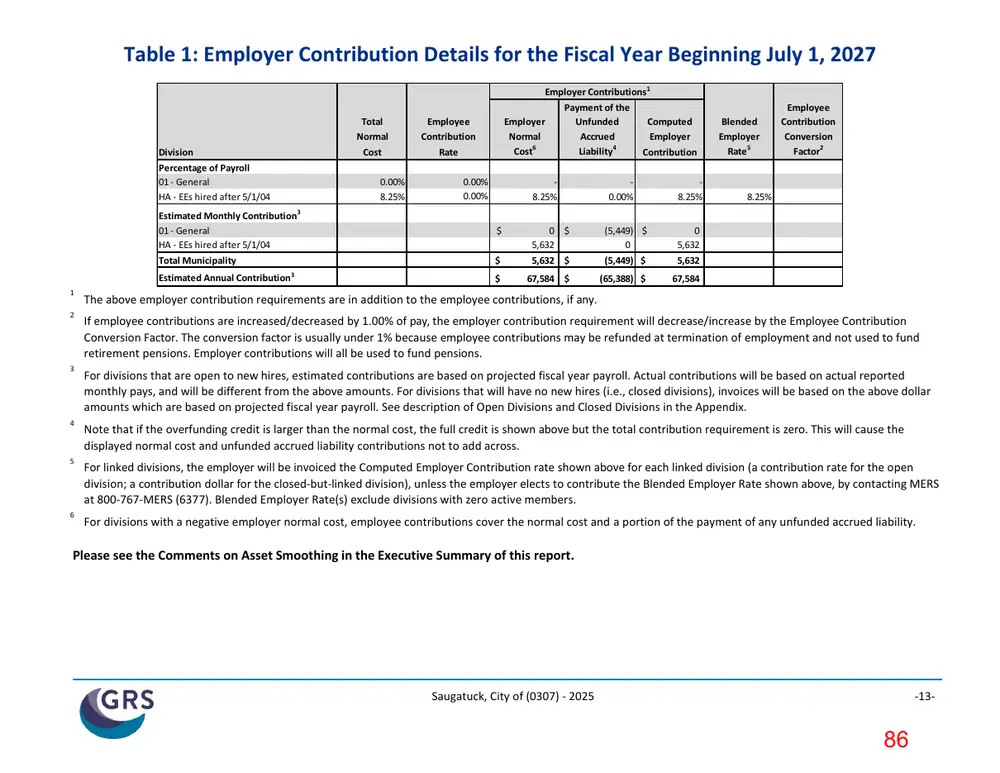
Table 1: Employer Contribution Details for the Fiscal Year Beginning July 1, 2027
Division Percentage of Payroll 01 - General HA - EEs hired after 5/1/04 Estimated Monthly Contribution 01 - General HA - EEs hired after 5/1/04 Total Municipality Estimated Annual Contribution3 1 2
Total Normal
Employee Contribution
Cost
Rate
0.00% 8.25%
Employer Contributions1 Payment of the Employer Unfunded Computed Normal Accrued Employer Cost6 Liability4 Contribution
0.00% 0.00%
8.25%
0.00%
8.25%
0 $ 5,632 5,632 $
(5,449) $ 0 (5,449) $
0 5,632 5,632
67,584 $
(65,388) $
67,584
Blended Employer Rate5
Employee Contribution Conversion Factor2
8.25%
The above employer contribution requirements are in addition to the employee contributions, if any. If employee contributions are increased/decreased by 1.00% of pay, the employer contribution requirement will decrease/increase by the Employee Contribution Conversion Factor. The conversion factor is usually under 1% because employee contributions may be refunded at termination of employment and not used to fund retirement pensions. Employer contributions will all be used to fund pensions. For divisions that are open to new hires, estimated contributions are based on projected fiscal year payroll. Actual contributions will be based on actual reported monthly pays, and will be different from the above amounts. For divisions that will have no new hires (i.e., closed divisions), invoices will be based on the above dollar amounts which are based on projected fiscal year payroll. See description of Open Divisions and Closed Divisions in the Appendix. Note that if the overfunding credit is larger than the normal cost, the full credit is shown above but the total contribution requirement is zero. This will cause the displayed normal cost and unfunded accrued liability contributions not to add across. For linked divisions, the employer will be invoiced the Computed Employer Contribution rate shown above for each linked division (a contribution rate for the open division; a contribution dollar for the closed-but-linked division), unless the employer elects to contribute the Blended Employer Rate shown above, by contacting MERS at 800-767-MERS (6377). Blended Employer Rate(s) exclude divisions with zero active members. For divisions with a negative employer normal cost, employee contributions cover the normal cost and a portion of the payment of any unfunded accrued liability.
Please see the Comments on Asset Smoothing in the Executive Summary of this report.
Saugatuck, City of (0307) - 2025
-13-
Page 87
Text of page 87
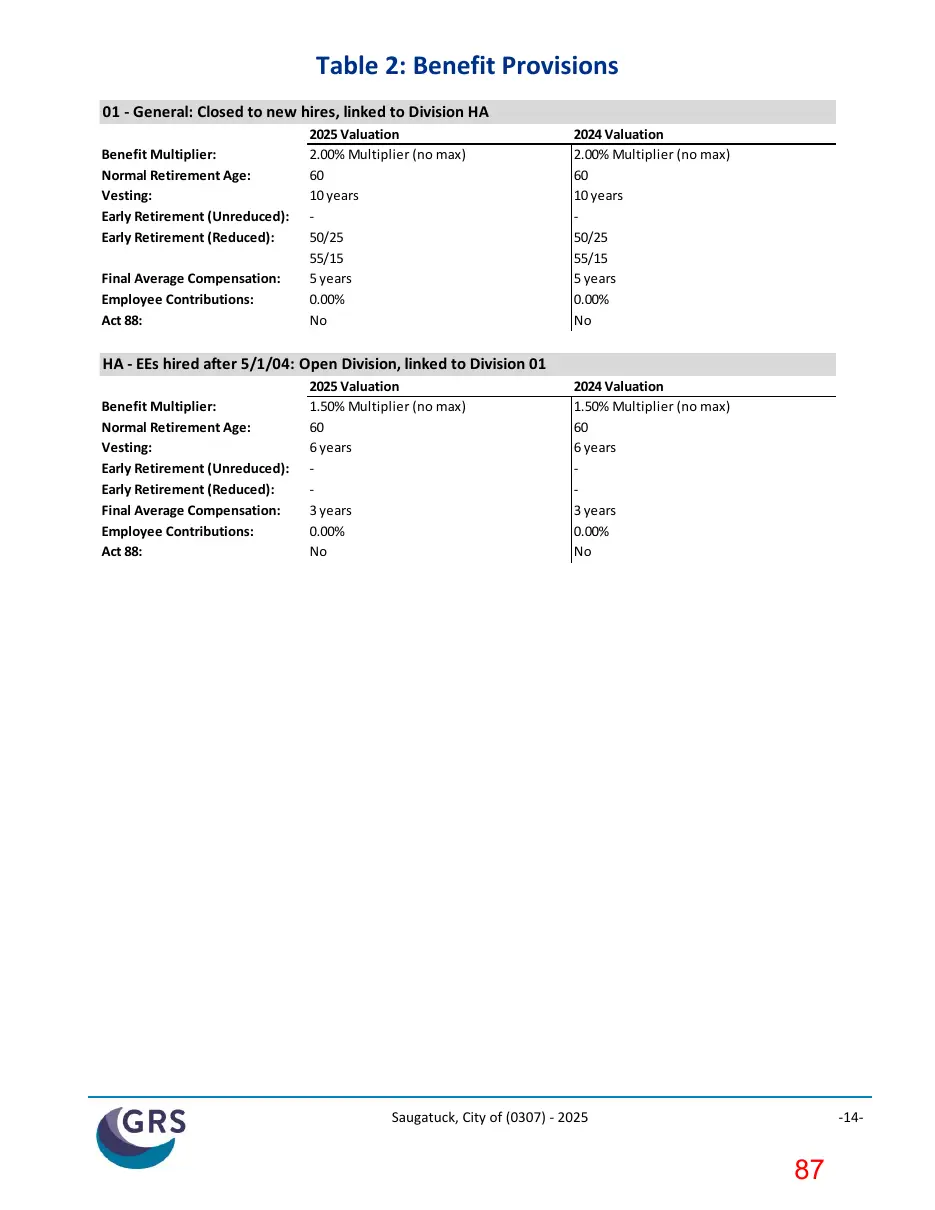
Table 2: Benefit Provisions 01 - General: Closed to new hires, linked to Division HA Benefit Multiplier: Normal Retirement Age: Vesting: Early Retirement (Unreduced): Early Retirement (Reduced): Final Average Compensation: Employee Contributions: Act 88:
2025 Valuation 2.00% Multiplier (no max) 60 10 years 50/25 55/15 5 years 0.00% No
2024 Valuation 2.00% Multiplier (no max) 60 10 years 50/25 55/15 5 years 0.00% No
HA - EEs hired after 5/1/04: Open Division, linked to Division 01 Benefit Multiplier: Normal Retirement Age: Vesting: Early Retirement (Unreduced): Early Retirement (Reduced): Final Average Compensation: Employee Contributions: Act 88:
2025 Valuation 1.50% Multiplier (no max) 60 6 years 3 years 0.00% No
2024 Valuation 1.50% Multiplier (no max) 60 6 years 3 years 0.00% No
Saugatuck, City of (0307) - 2025
-14-
Page 88
Text of page 88
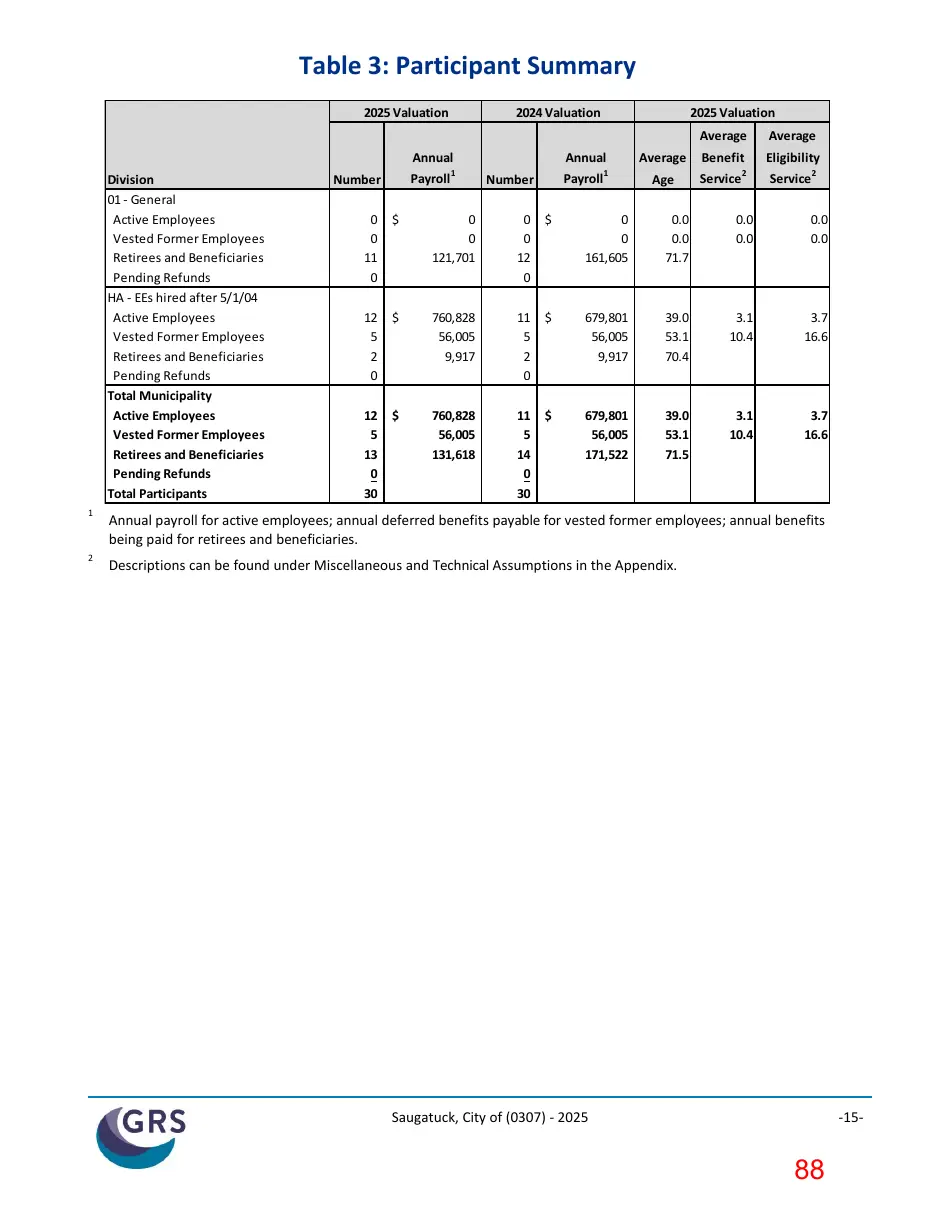
Table 3: Participant Summary
Division 01 - General Active Employees Vested Former Employees Retirees and Beneficiaries Pending Refunds HA - EEs hired after 5/1/04 Active Employees Vested Former Employees Retirees and Beneficiaries Pending Refunds Total Municipality Active Employees Vested Former Employees Retirees and Beneficiaries Pending Refunds Total Participants 1
2025 Valuation
2024 Valuation
Annual Payroll1
Annual Payroll1
Number
Number
2025 Valuation Average Age
Average
Average
Benefit Service 2
Eligibility Service 2
0 0 11 0
0 0 121,701
0 0 12 0
0 0 161,605
0.0 0.0 71.7
0.0 0.0
0.0 0.0
12 5 2 0
760,828 56,005 9,917
11 5 2 0
679,801 56,005 9,917
39.0 53.1 70.4
3.1 10.4
3.7 16.6
12 5 13 0 30
760,828 56,005 131,618
11 5 14 0 30
679,801 56,005 171,522
39.0 53.1 71.5
3.1 10.4
3.7 16.6
Annual payroll for active employees; annual deferred benefits payable for vested former employees; annual benefits being paid for retirees and beneficiaries. Descriptions can be found under Miscellaneous and Technical Assumptions in the Appendix.
Saugatuck, City of (0307) - 2025
-15-
Page 89
Text of page 89
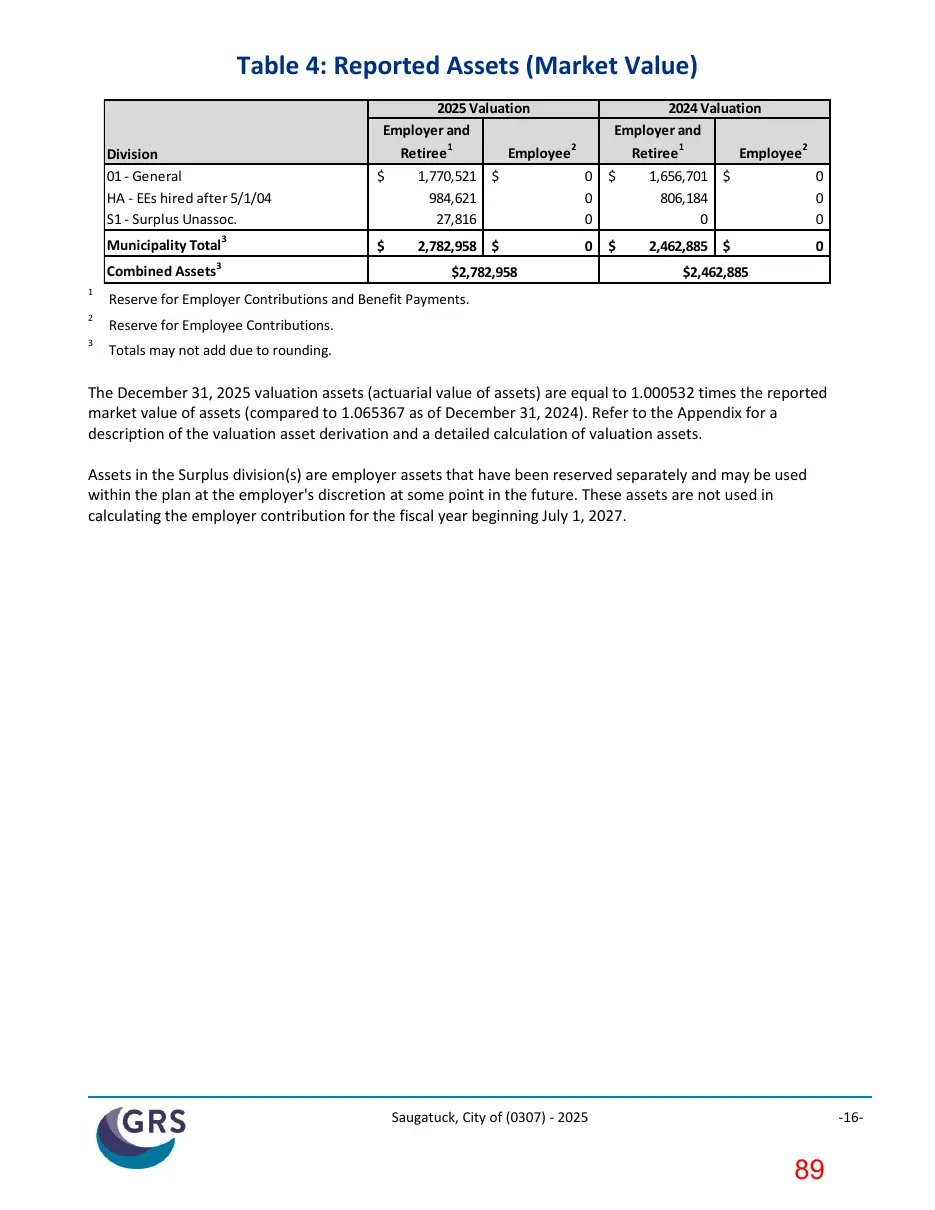
Table 4: Reported Assets (Market Value) Division 01 - General HA - EEs hired after 5/1/04 S1 - Surplus Unassoc. Municipality Total3 Combined Assets 1 2 3
2025 Valuation Employer and Retiree 1 Employee2
2024 Valuation Employer and Retiree 1 Employee 2
1,770,521 $ 984,621 27,816
0 0 0
1,656,701 $ 806,184 0
0 0 0
2,782,958 $
2,462,885 $
$2,782,958
$2,462,885
Reserve for Employer Contributions and Benefit Payments. Reserve for Employee Contributions. Totals may not add due to rounding.
The December 31, 2025 valuation assets (actuarial value of assets) are equal to 1.000532 times the reported market value of assets (compared to 1.065367 as of December 31, 2024). Refer to the Appendix for a description of the valuation asset derivation and a detailed calculation of valuation assets. Assets in the Surplus division(s) are employer assets that have been reserved separately and may be used within the plan at the employer's discretion at some point in the future. These assets are not used in calculating the employer contribution for the fiscal year beginning July 1, 2027.
Saugatuck, City of (0307) - 2025
-16-
Page 90
Text of page 90
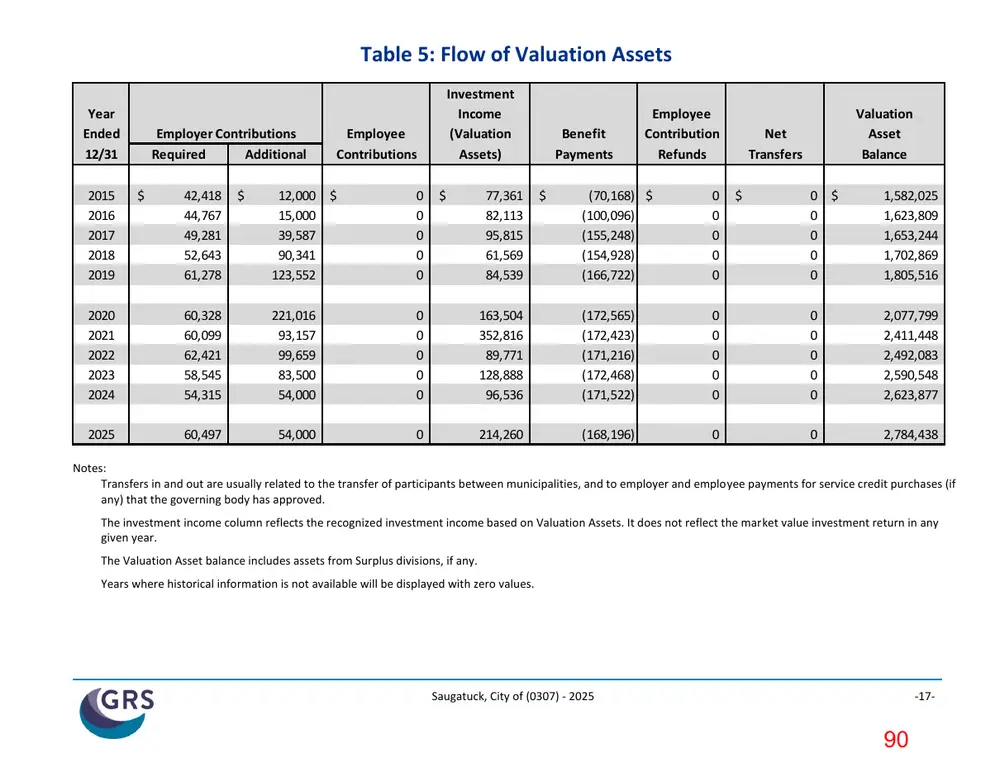
Table 5: Flow of Valuation Assets Year Ended 12/31 2015 2016 2017 2018 2019
Employer Contributions Required Additional $
42,418 44,767 49,281 52,643 61,278
Investment Income (Valuation Assets)
Employee Contributions
12,000 $ 15,000 39,587 90,341 123,552
0 0 0 0 0
77,361 82,113 95,815 61,569 84,539
Benefit Payments $
Employee Contribution Refunds
(70,168) $ (100,096) (155,248) (154,928) (166,722)
0 0 0 0 0
Valuation Asset Balance
Net Transfers $
0 $ 0 0 0 0
1,582,025 1,623,809 1,653,244 1,702,869 1,805,516
2020 2021 2022 2023 2024
60,328 60,099 62,421 58,545 54,315
221,016 93,157 99,659 83,500 54,000
0 0 0 0 0
163,504 352,816 89,771 128,888 96,536
(172,565) (172,423) (171,216) (172,468) (171,522)
0 0 0 0 0
0 0 0 0 0
2,077,799 2,411,448 2,492,083 2,590,548 2,623,877
2025
60,497
54,000
214,260
(168,196)
2,784,438
Notes: Transfers in and out are usually related to the transfer of participants between municipalities, and to employer and employee payments for service credit purchases (if any) that the governing body has approved. The investment income column reflects the recognized investment income based on Valuation Assets. It does not reflect the market value investment return in any given year. The Valuation Asset balance includes assets from Surplus divisions, if any. Years where historical information is not available will be displayed with zero values.
Saugatuck, City of (0307) - 2025
-17-
Page 91
Text of page 91
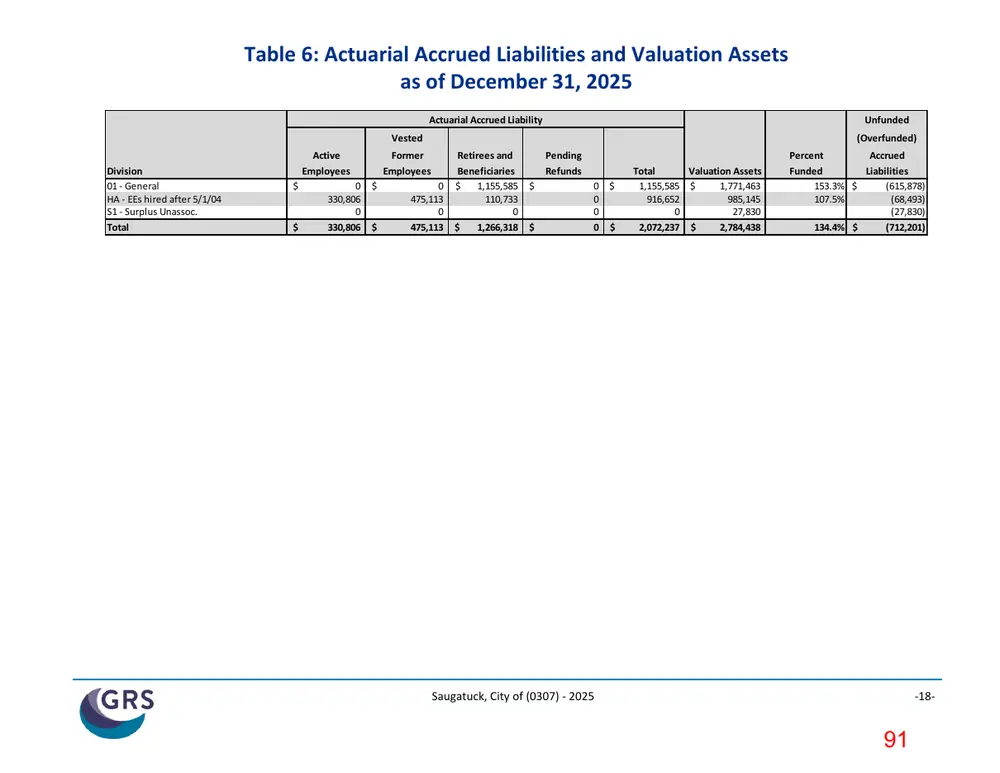
Table 6: Actuarial Accrued Liabilities and Valuation Assets as of December 31, 2025 Actuarial Accrued Liability
Unfunded
Vested Division 01 - General HA - EEs hired after 5/1/04 S1 - Surplus Unassoc. Total
(Overfunded)
Active
Former
Retirees and
Pending
Employees
Employees
Beneficiaries $ 1,155,585 110,733 0 $ 1,266,318
Refunds
0 330,806 0 330,806
0 475,113 0 475,113
Percent 0 $ 0 0 0 $
Total Valuation Assets 1,155,585 $ 1,771,463 916,652 985,145 0 27,830 2,072,237 $ 2,784,438
Accrued
Funded Liabilities 153.3% $ (615,878) 107.5% (68,493) (27,830) 134.4% $ (712,201)
Saugatuck, City of (0307) - 2025
-18-
Page 92
Text of page 92
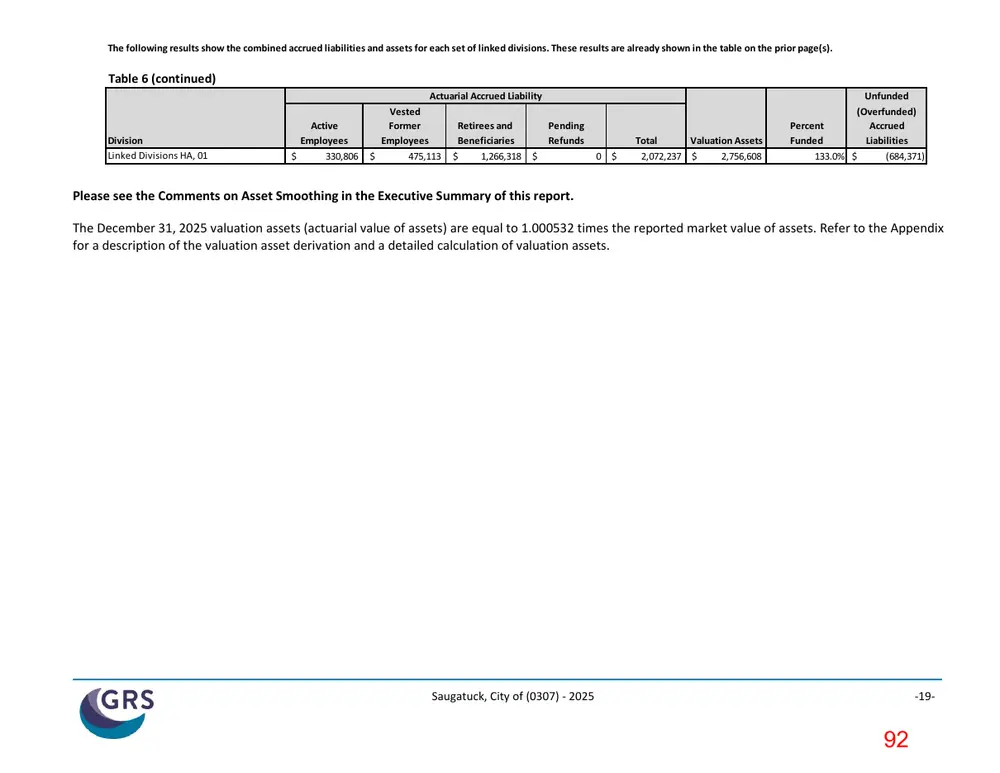
The following results show the combined accrued liabilities and assets for each set of linked divisions. These results are already shown in the table on the prior page(s).
Table 6 (continued)
Division Linked Divisions HA, 01
Active Employees $ 330,806
Actuarial Accrued Liability Vested Former Retirees and Pending Employees Beneficiaries Refunds $ 475,113 $ 1,266,318 $
Total Valuation Assets 2,072,237 $ 2,756,608
Unfunded (Overfunded) Percent Accrued Funded Liabilities 133.0% $ (684,371)
Please see the Comments on Asset Smoothing in the Executive Summary of this report. The December 31, 2025 valuation assets (actuarial value of assets) are equal to 1.000532 times the reported market value of assets. Refer to the Appendix for a description of the valuation asset derivation and a detailed calculation of valuation assets.
Saugatuck, City of (0307) - 2025
-19-
Page 93
Text of page 93
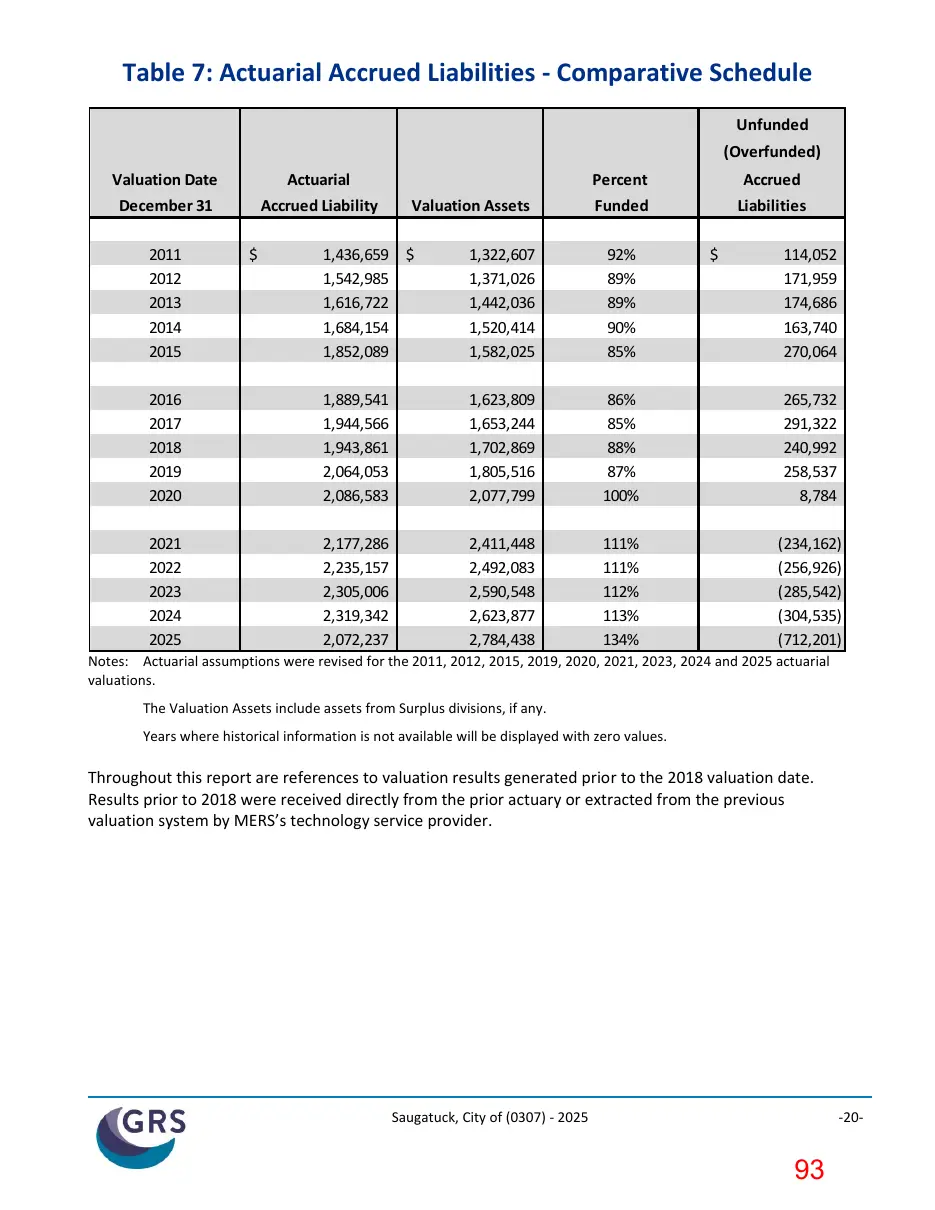
Table 7: Actuarial Accrued Liabilities - Comparative Schedule Unfunded (Overfunded) Valuation Date
Actuarial
December 31
Accrued Liability
2011 2012 2013 2014 2015
Valuation Assets
Percent
Accrued
Funded
Liabilities
1,436,659 $ 1,542,985 1,616,722 1,684,154 1,852,089
1,322,607 1,371,026 1,442,036 1,520,414 1,582,025
92% 89% 89% 90% 85%
114,052 171,959 174,686 163,740 270,064
2016 2017 2018 2019 2020
1,889,541 1,944,566 1,943,861 2,064,053 2,086,583
1,623,809 1,653,244 1,702,869 1,805,516 2,077,799
86% 85% 88% 87% 100%
265,732 291,322 240,992 258,537 8,784
2021 2022 2023 2024 2025
2,177,286 2,235,157 2,305,006 2,319,342 2,072,237
2,411,448 2,492,083 2,590,548 2,623,877 2,784,438
111% 111% 112% 113% 134%
(234,162) (256,926) (285,542) (304,535) (712,201)
Notes: Actuarial assumptions were revised for the 2011, 2012, 2015, 2019, 2020, 2021, 2023, 2024 and 2025 actuarial valuations. The Valuation Assets include assets from Surplus divisions, if any. Years where historical information is not available will be displayed with zero values.
Throughout this report are references to valuation results generated prior to the 2018 valuation date. Results prior to 2018 were received directly from the prior actuary or extracted from the previous valuation system by MERS’s technology service provider.
Saugatuck, City of (0307) - 2025
-20-
Page 94
Text of page 94
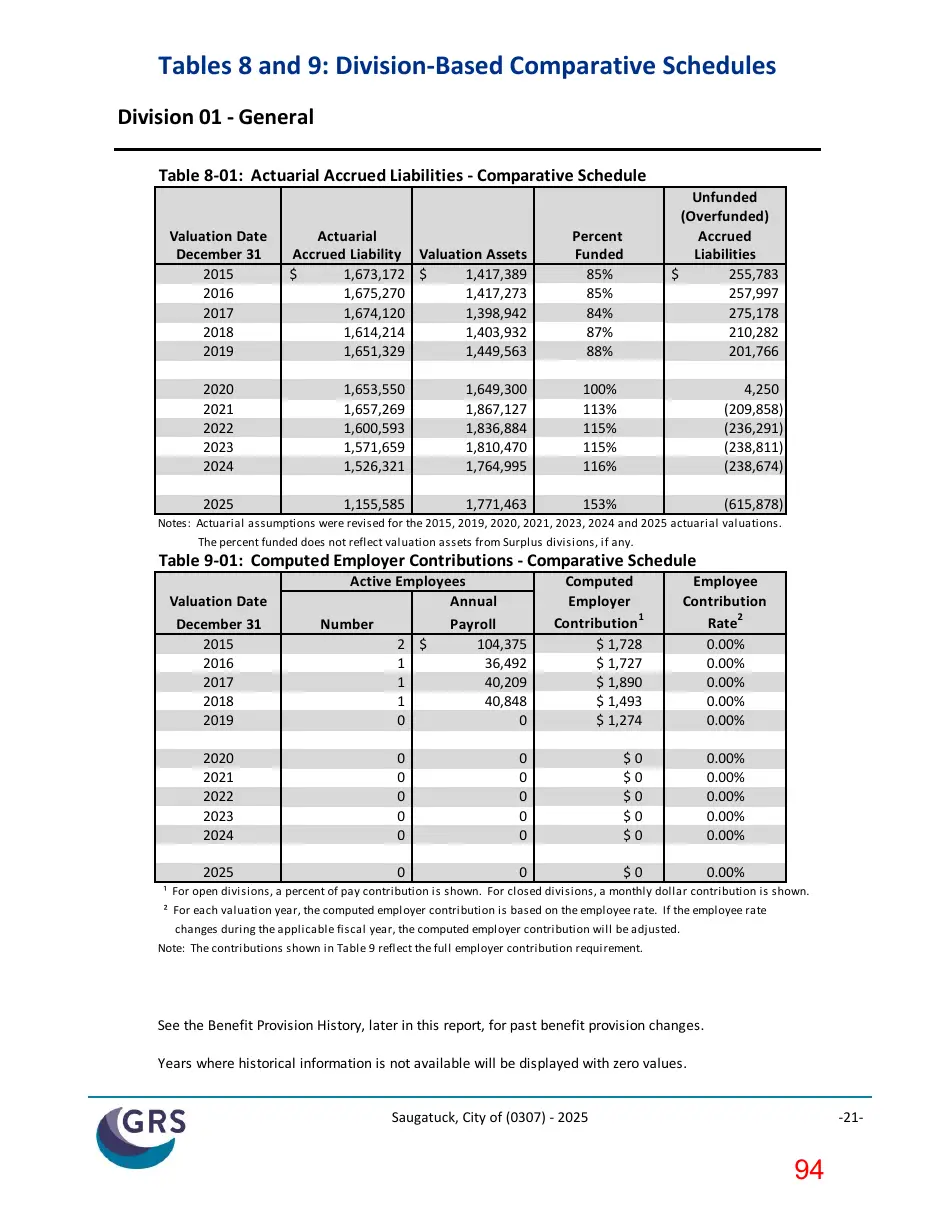
Tables 8 and 9: Division-Based Comparative Schedules Division 01 - General Table 8-01: Actuarial Accrued Liabilities - Comparative Schedule Valuation Date December 31 2015 2016 2017 2018 2019
Actuarial Accrued Liability Valuation Assets $ 1,673,172 $ 1,417,389 1,675,270 1,417,273 1,674,120 1,398,942 1,614,214 1,403,932 1,651,329 1,449,563
Percent Funded 85% 85% 84% 87% 88%
Unfunded (Overfunded) Accrued Liabilities $ 255,783 257,997 275,178 210,282 201,766
2020 2021 2022 2023 2024
1,653,550 1,657,269 1,600,593 1,571,659 1,526,321
1,649,300 1,867,127 1,836,884 1,810,470 1,764,995
100% 113% 115% 115% 116%
4,250 (209,858) (236,291) (238,811) (238,674)
2025
1,155,585
1,771,463
153%
(615,878)
Notes: Actuarial assumptions were revised for the 2015, 2019, 2020, 2021, 2023, 2024 and 2025 actuarial valuations. The percent funded does not reflect valuation assets from Surplus divisions, if any.
Table 9-01: Computed Employer Contributions - Comparative Schedule Valuation Date December 31 2015 2016 2017 2018 2019
Active Employees Annual Number Payroll 2 $ 104,375 1 36,492 1 40,209 1 40,848 0 0
Computed Employer Contribution 1 $ 1,728 $ 1,727 $ 1,890 $ 1,493 $ 1,274
Employee Contribution Rate2 0.00% 0.00% 0.00% 0.00% 0.00%
2020 2021 2022 2023 2024
0 0 0 0 0
0 0 0 0 0
$0 $0 $0 $0 $0
0.00% 0.00% 0.00% 0.00% 0.00%
2025
0.00%
¹ For open divisions, a percent of pay contribution is shown. For closed divisions, a monthly dollar contribution is shown. ² For each valuation year, the computed employer contribution is based on the employee rate. If the employee rate changes during the applicable fiscal year, the computed employer contribution will be adjusted. Note: The contributions shown in Table 9 reflect the full employer contribution requirement.
See the Benefit Provision History, later in this report, for past benefit provision changes. Years where historical information is not available will be displayed with zero values.
Saugatuck, City of (0307) - 2025
-21-
Page 95
Text of page 95
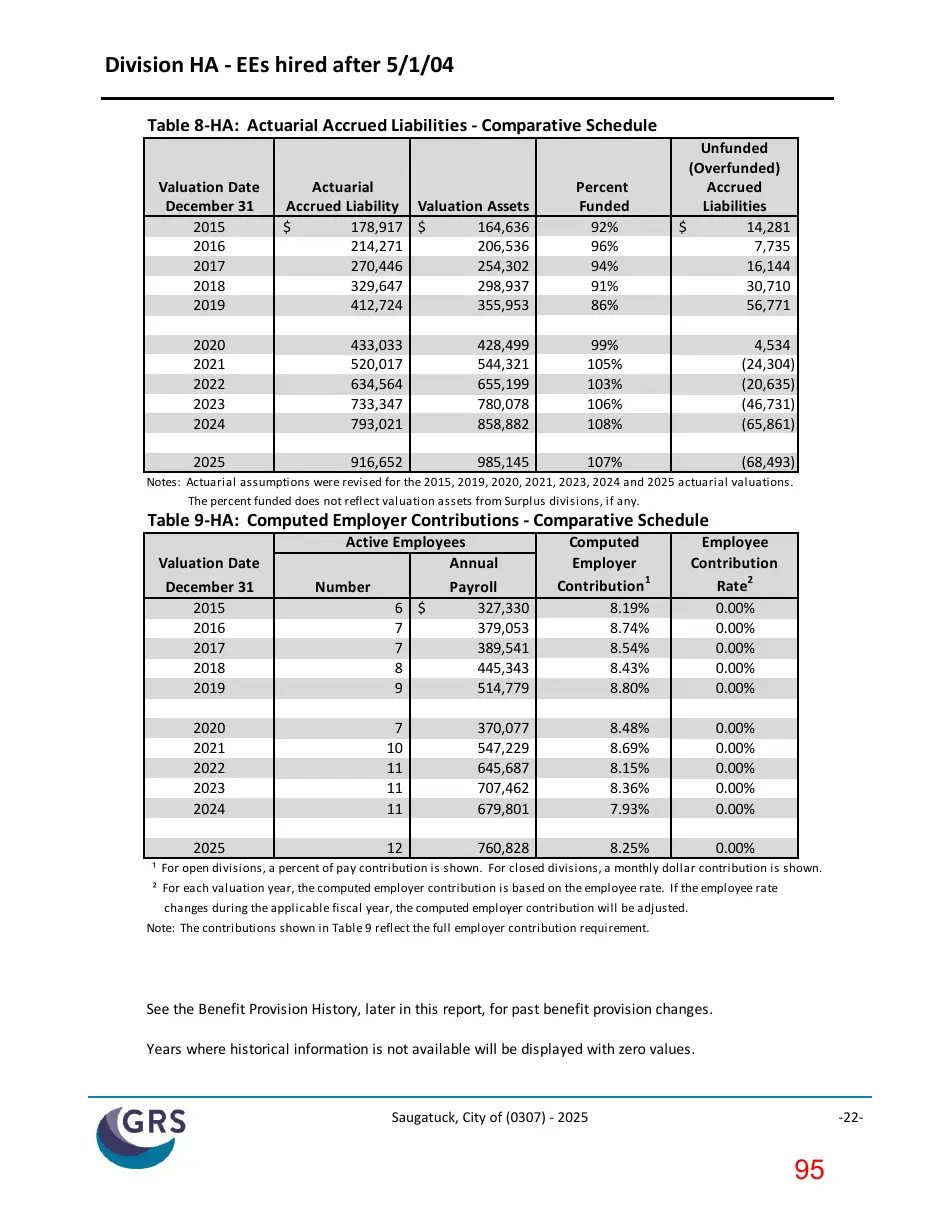
Division HA - EEs hired after 5/1/04 Table 8-HA: Actuarial Accrued Liabilities - Comparative Schedule Valuation Date December 31 2015 2016 2017 2018 2019
Actuarial Accrued Liability Valuation Assets $ 178,917 $ 164,636 214,271 206,536 270,446 254,302 329,647 298,937 412,724 355,953
Percent Funded 92% 96% 94% 91% 86%
Unfunded (Overfunded) Accrued Liabilities $ 14,281 7,735 16,144 30,710 56,771
2020 2021 2022 2023 2024
433,033 520,017 634,564 733,347 793,021
428,499 544,321 655,199 780,078 858,882
99% 105% 103% 106% 108%
4,534 (24,304) (20,635) (46,731) (65,861)
2025
916,652
985,145
107%
(68,493)
Notes: Actuarial assumptions were revised for the 2015, 2019, 2020, 2021, 2023, 2024 and 2025 actuarial valuations. The percent funded does not reflect valuation assets from Surplus divisions, if any.
Table 9-HA: Computed Employer Contributions - Comparative Schedule Valuation Date December 31 2015 2016 2017 2018 2019
Active Employees Annual Number Payroll 6 $ 327,330 7 379,053 7 389,541 8 445,343 9 514,779
Computed Employer Contribution 1 8.19% 8.74% 8.54% 8.43% 8.80%
Employee Contribution Rate2 0.00% 0.00% 0.00% 0.00% 0.00%
2020 2021 2022 2023 2024
7 10 11 11 11
370,077 547,229 645,687 707,462 679,801
8.48% 8.69% 8.15% 8.36% 7.93%
0.00% 0.00% 0.00% 0.00% 0.00%
2025
760,828
8.25%
0.00%
¹ For open divisions, a percent of pay contribution is shown. For closed divisions, a monthly dollar contribution is shown. ² For each valuation year, the computed employer contribution is based on the employee rate. If the employee rate changes during the applicable fiscal year, the computed employer contribution will be adjusted. Note: The contributions shown in Table 9 reflect the full employer contribution requirement.
See the Benefit Provision History, later in this report, for past benefit provision changes. Years where historical information is not available will be displayed with zero values.
Saugatuck, City of (0307) - 2025
-22-
Page 96
Text of page 96
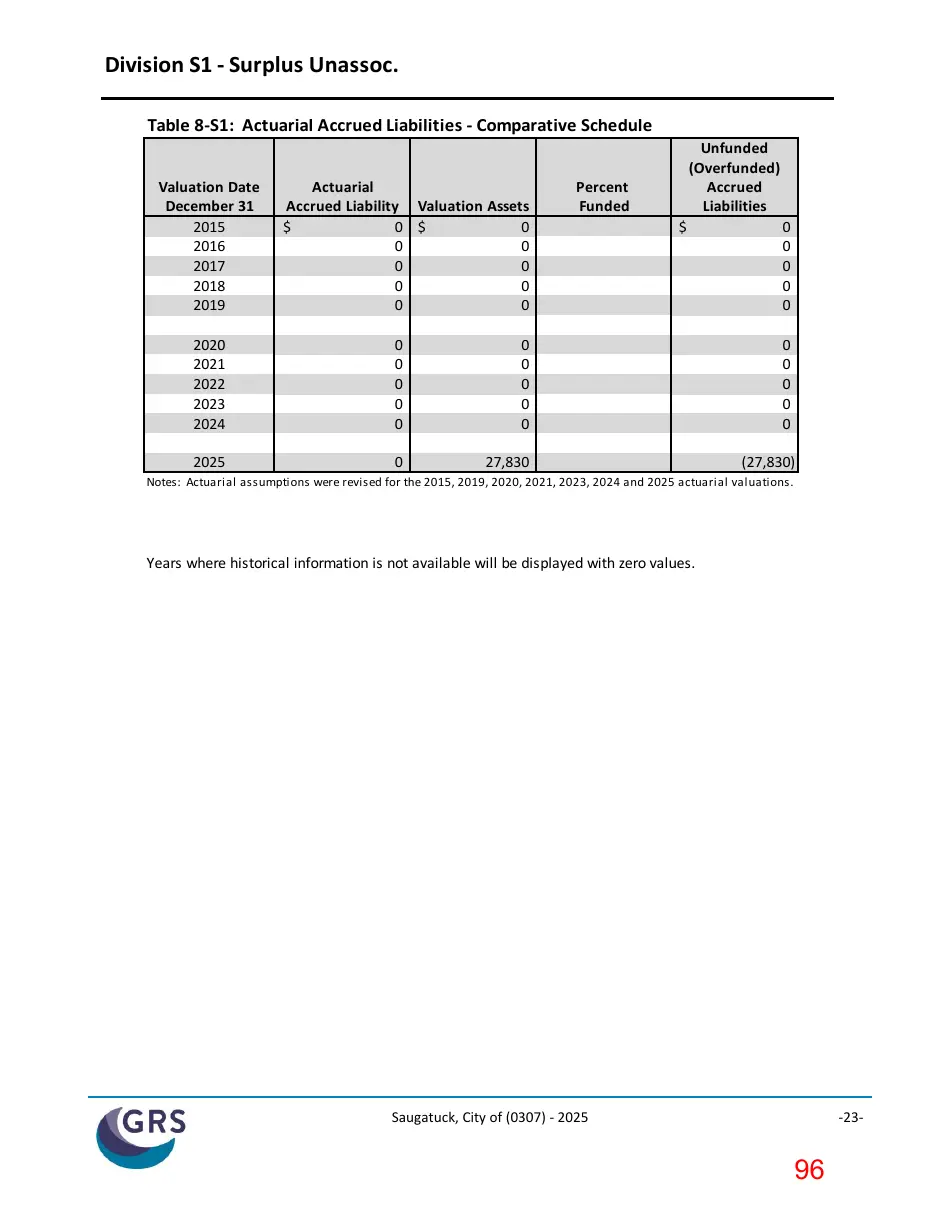
Division S1 - Surplus Unassoc. Table 8-S1: Actuarial Accrued Liabilities - Comparative Schedule Unfunded (Overfunded) Accrued Liabilities
Valuation Date December 31 2015 2016 2017 2018 2019
Actuarial Accrued Liability Valuation Assets $ 0 $ 0 0 0 0 0 0 0 0 0
Percent Funded
2020 2021 2022 2023 2024
0 0 0 0 0
0 0 0 0 0
0 0 0 0 0
2025
27,830
(27,830)
0 0 0 0 0
Notes: Actuarial assumptions were revised for the 2015, 2019, 2020, 2021, 2023, 2024 and 2025 actuarial valuations.
Years where historical information is not available will be displayed with zero values.
Saugatuck, City of (0307) - 2025
-23-
Page 97
Text of page 97
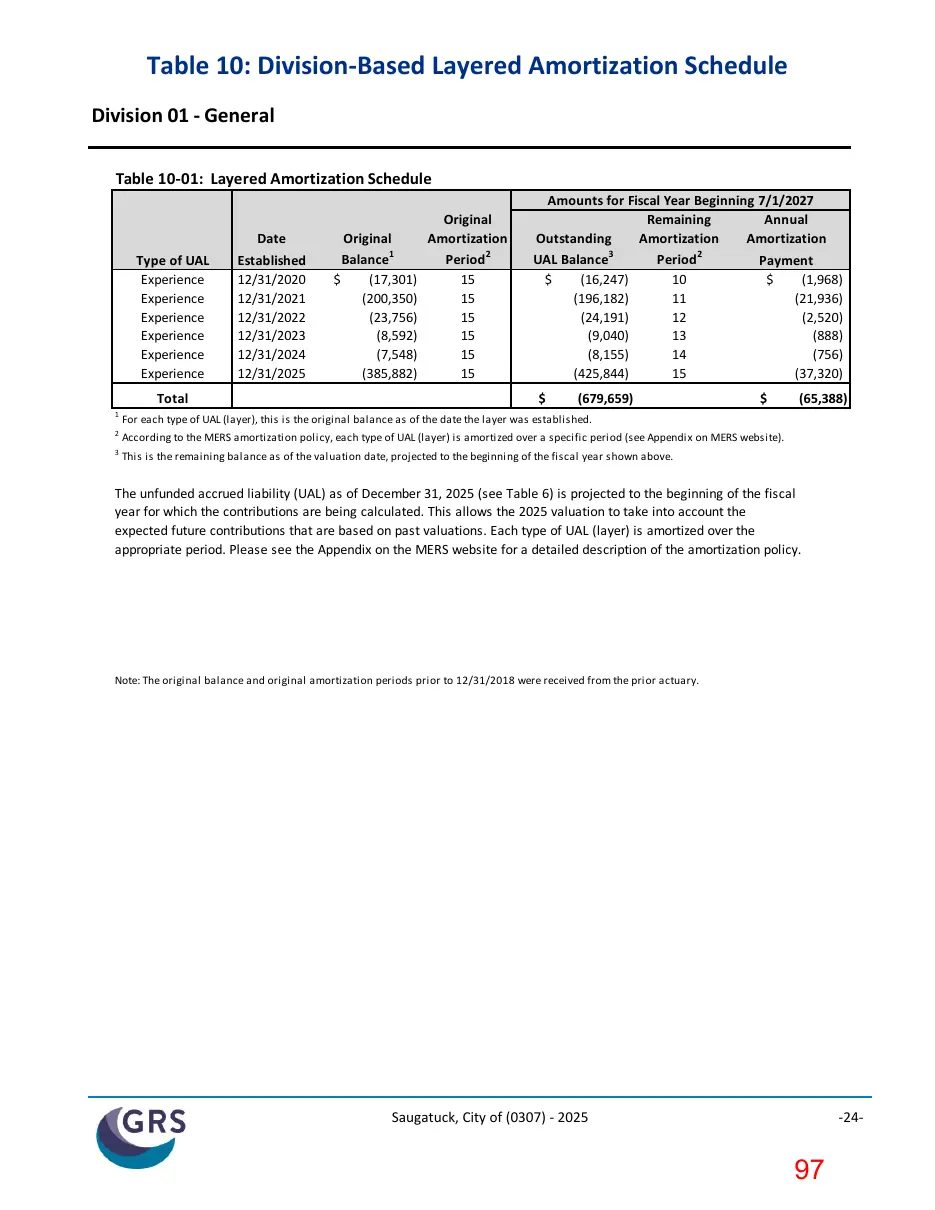
Table 10: Division-Based Layered Amortization Schedule Division 01 - General Table 10-01: Layered Amortization Schedule
Type of UAL Experience Experience Experience Experience Experience Experience Total
Date Established 12/31/2020 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025
Original Balance1 $ (17,301) (200,350) (23,756) (8,592) (7,548) (385,882)
Original Amortization Period 2 15 15 15 15 15 15
Amounts for Fiscal Year Beginning 7/1/2027 Remaining Annual Outstanding Amortization Amortization UAL Balance3 Period 2 Payment $ (16,247) 10 $ (1,968) (196,182) 11 (21,936) (24,191) 12 (2,520) (9,040) 13 (888) (8,155) 14 (756) (425,844) 15 (37,320) $
(679,659)
For each type of UAL (layer), this is the original balance as of the date the layer was established.
According to the MERS amortization policy, each type of UAL (layer) is amortized over a specific period (see Appendix on MERS website).
This is the remaining balance as of the valuation date, projected to the beginning of the fiscal year shown above.
(65,388)
The unfunded accrued liability (UAL) as of December 31, 2025 (see Table 6) is projected to the beginning of the fiscal year for which the contributions are being calculated. This allows the 2025 valuation to take into account the expected future contributions that are based on past valuations. Each type of UAL (layer) is amortized over the appropriate period. Please see the Appendix on the MERS website for a detailed description of the amortization policy.
Note: The original balance and original amortization periods prior to 12/31/2018 were received from the prior actuary.
Saugatuck, City of (0307) - 2025
-24-
Page 98
Text of page 98
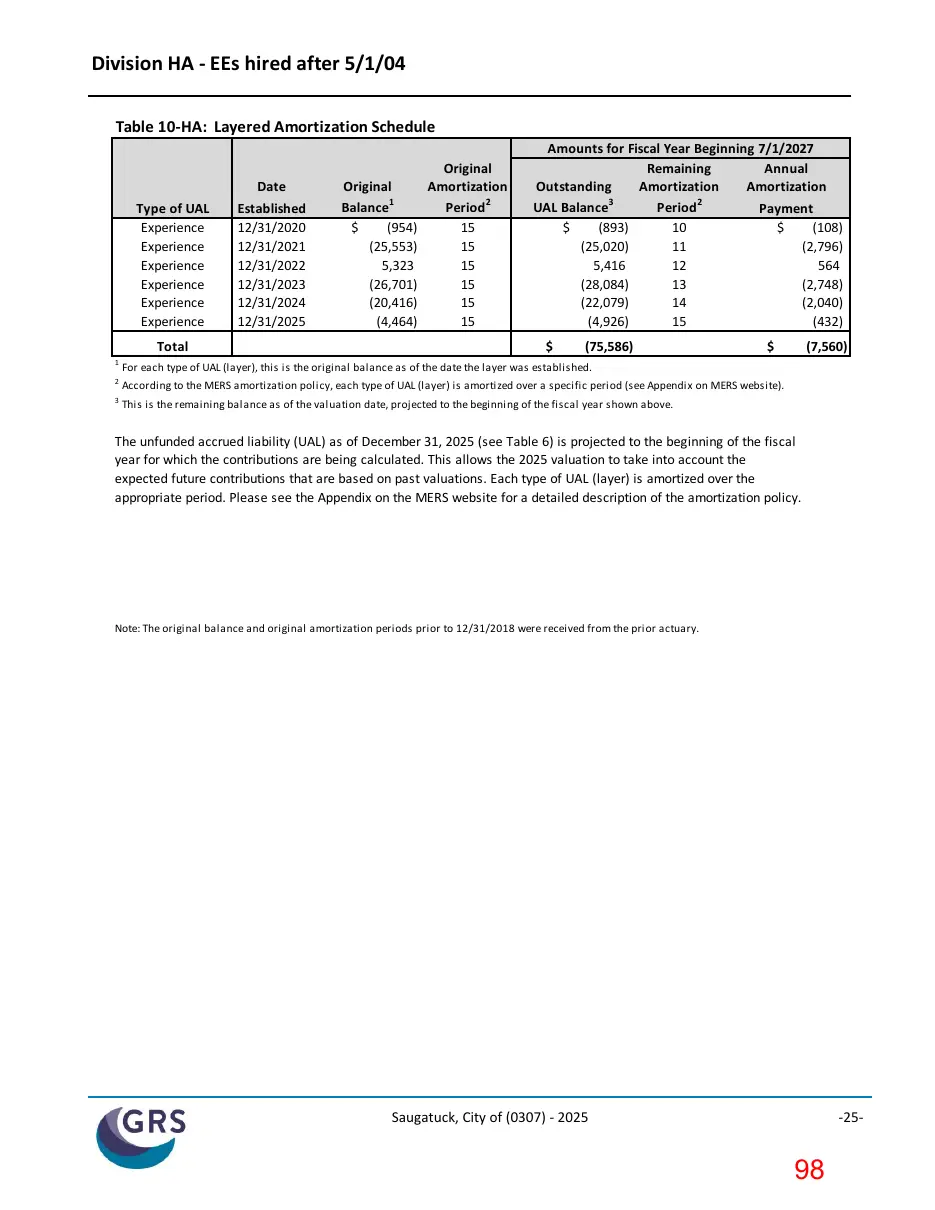
Division HA - EEs hired after 5/1/04 Table 10-HA: Layered Amortization Schedule
Type of UAL Experience Experience Experience Experience Experience Experience Total
Date Established 12/31/2020 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025
Original Balance1 $ (954) (25,553) 5,323 (26,701) (20,416) (4,464)
Original Amortization Period 2 15 15 15 15 15 15
Amounts for Fiscal Year Beginning 7/1/2027 Remaining Annual Outstanding Amortization Amortization UAL Balance3 Period 2 Payment $ (893) 10 $ (108) (25,020) 11 (2,796) 5,416 12 564 (28,084) 13 (2,748) (22,079) 14 (2,040) (4,926) 15 (432) $
(75,586)
For each type of UAL (layer), this is the original balance as of the date the layer was established.
According to the MERS amortization policy, each type of UAL (layer) is amortized over a specific period (see Appendix on MERS website).
This is the remaining balance as of the valuation date, projected to the beginning of the fiscal year shown above.
(7,560)
The unfunded accrued liability (UAL) as of December 31, 2025 (see Table 6) is projected to the beginning of the fiscal year for which the contributions are being calculated. This allows the 2025 valuation to take into account the expected future contributions that are based on past valuations. Each type of UAL (layer) is amortized over the appropriate period. Please see the Appendix on the MERS website for a detailed description of the amortization policy.
Note: The original balance and original amortization periods prior to 12/31/2018 were received from the prior actuary.
Saugatuck, City of (0307) - 2025
-25-
Page 99
Text of page 99
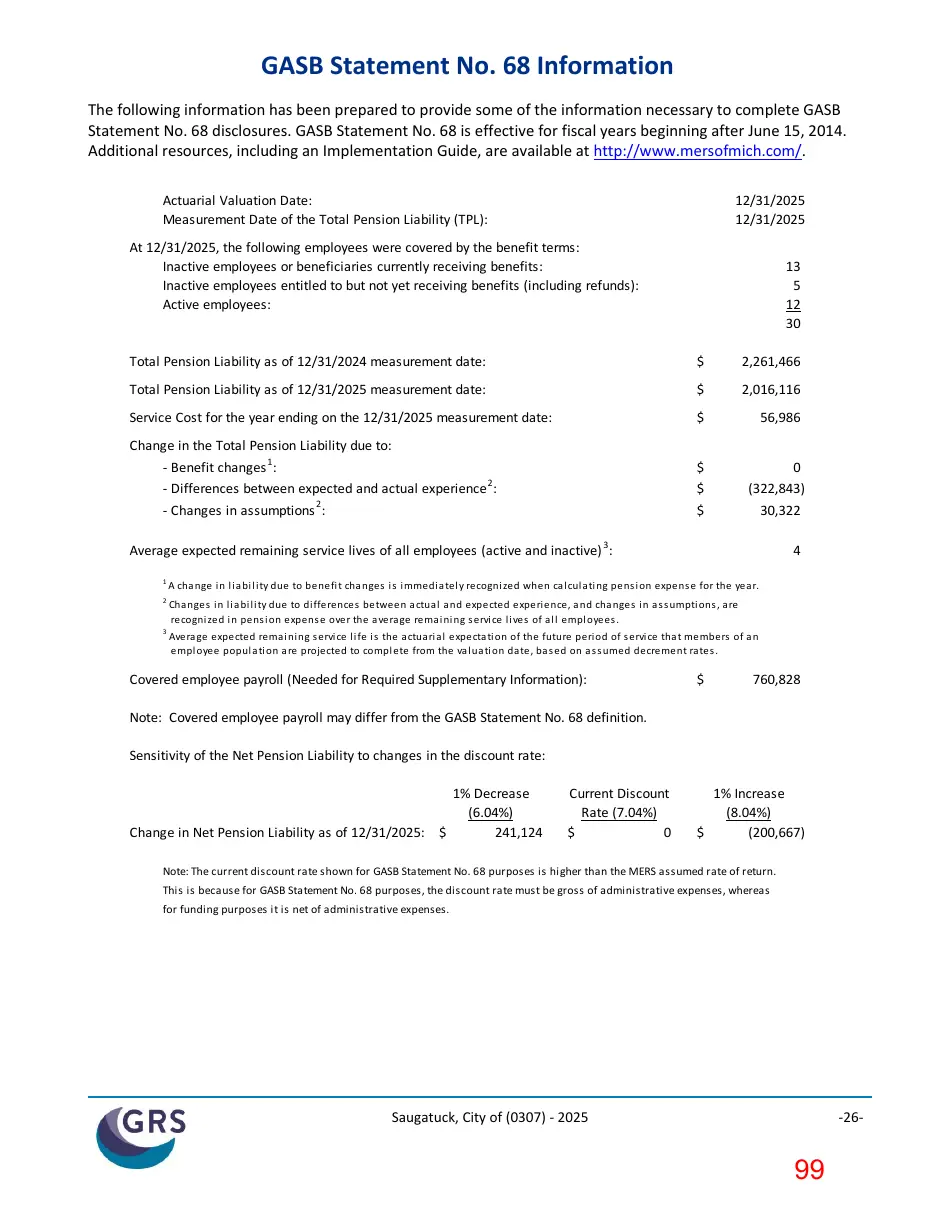
GASB Statement No. 68 Information The following information has been prepared to provide some of the information necessary to complete GASB Statement No. 68 disclosures. GASB Statement No. 68 is effective for fiscal years beginning after June 15, 2014. Additional resources, including an Implementation Guide, are available at http://www.mersofmich.com/. Actuarial Valuation Date: Measurement Date of the Total Pension Liability (TPL):
12/31/2025 12/31/2025
At 12/31/2025, the following employees were covered by the benefit terms: Inactive employees or beneficiaries currently receiving benefits: Inactive employees entitled to but not yet receiving benefits (including refunds): Active employees:
13 5 12 30
Total Pension Liability as of 12/31/2024 measurement date:
2,261,466
Total Pension Liability as of 12/31/2025 measurement date:
2,016,116
Service Cost for the year ending on the 12/31/2025 measurement date:
56,986
Change in the Total Pension Liability due to: - Benefit changes 1: - Differences between expected and actual experience 2: 2 - Changes in assumptions :
0 (322,843) 30,322
Average expected remaining service lives of all employees (active and inactive) 3:
A cha nge i n l i a bi l i ty due to benefi t cha nges i s i mmedi a tel y recogni zed when ca l cul a ti ng pens i on expens e for the yea r.
Cha nges i n l i a bi l i ty due to di fferences between a ctua l a nd expected experi ence, a nd cha nges i n a s s umpti ons , a re recogni zed i n pens i on expens e over the a vera ge rema i ni ng s ervi ce l i ves of a l l empl oyees .
Avera ge expected rema i ni ng s ervi ce l i fe i s the a ctua ri a l expecta ti on of the future peri od of s ervi ce tha t members of a n empl oyee popul a ti on a re projected to compl ete from the va l ua ti on da te, ba s ed on a s s umed decrement ra tes .
Covered employee payroll (Needed for Required Supplementary Information):
760,828
Note: Covered employee payroll may differ from the GASB Statement No. 68 definition. Sensitivity of the Net Pension Liability to changes in the discount rate: 1% Decrease (6.04%) Change in Net Pension Liability as of 12/31/2025: $ 241,124
Current Discount Rate (7.04%) $ 0
1% Increase (8.04%) $ (200,667)
Note: The current discount rate shown for GASB Statement No. 68 purposes is higher than the MERS assumed rate of return. This is because for GASB Statement No. 68 purposes, the discount rate must be gross of administrative expenses, whereas for funding purposes it is net of administrative expenses.
Saugatuck, City of (0307) - 2025
-26-
Page 100
Text of page 100
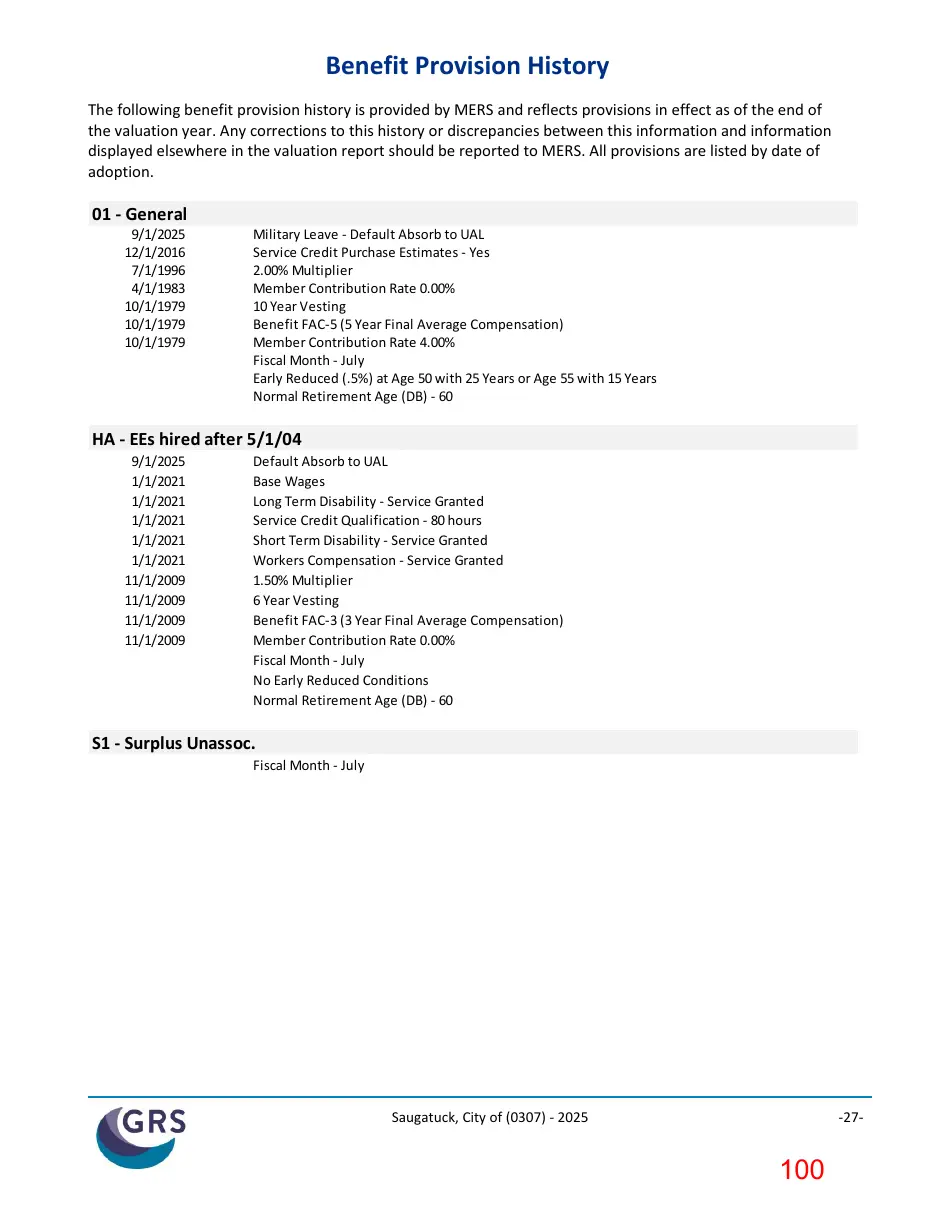
Benefit Provision History The following benefit provision history is provided by MERS and reflects provisions in effect as of the end of the valuation year. Any corrections to this history or discrepancies between this information and information displayed elsewhere in the valuation report should be reported to MERS. All provisions are listed by date of adoption.
01 - General 9/1/2025 12/1/2016 7/1/1996 4/1/1983 10/1/1979 10/1/1979 10/1/1979
Military Leave - Default Absorb to UAL Service Credit Purchase Estimates - Yes 2.00% Multiplier Member Contribution Rate 0.00% 10 Year Vesting Benefit FAC-5 (5 Year Final Average Compensation) Member Contribution Rate 4.00% Fiscal Month - July Early Reduced (.5%) at Age 50 with 25 Years or Age 55 with 15 Years Normal Retirement Age (DB) - 60
HA - EEs hired after 5/1/04 9/1/2025 1/1/2021 1/1/2021 1/1/2021 1/1/2021 1/1/2021 11/1/2009 11/1/2009 11/1/2009 11/1/2009
Default Absorb to UAL Base Wages Long Term Disability - Service Granted Service Credit Qualification - 80 hours Short Term Disability - Service Granted Workers Compensation - Service Granted 1.50% Multiplier 6 Year Vesting Benefit FAC-3 (3 Year Final Average Compensation) Member Contribution Rate 0.00% Fiscal Month - July No Early Reduced Conditions Normal Retirement Age (DB) - 60
S1 - Surplus Unassoc. Fiscal Month - July
Saugatuck, City of (0307) - 2025
-27-
Page 101
Text of page 101
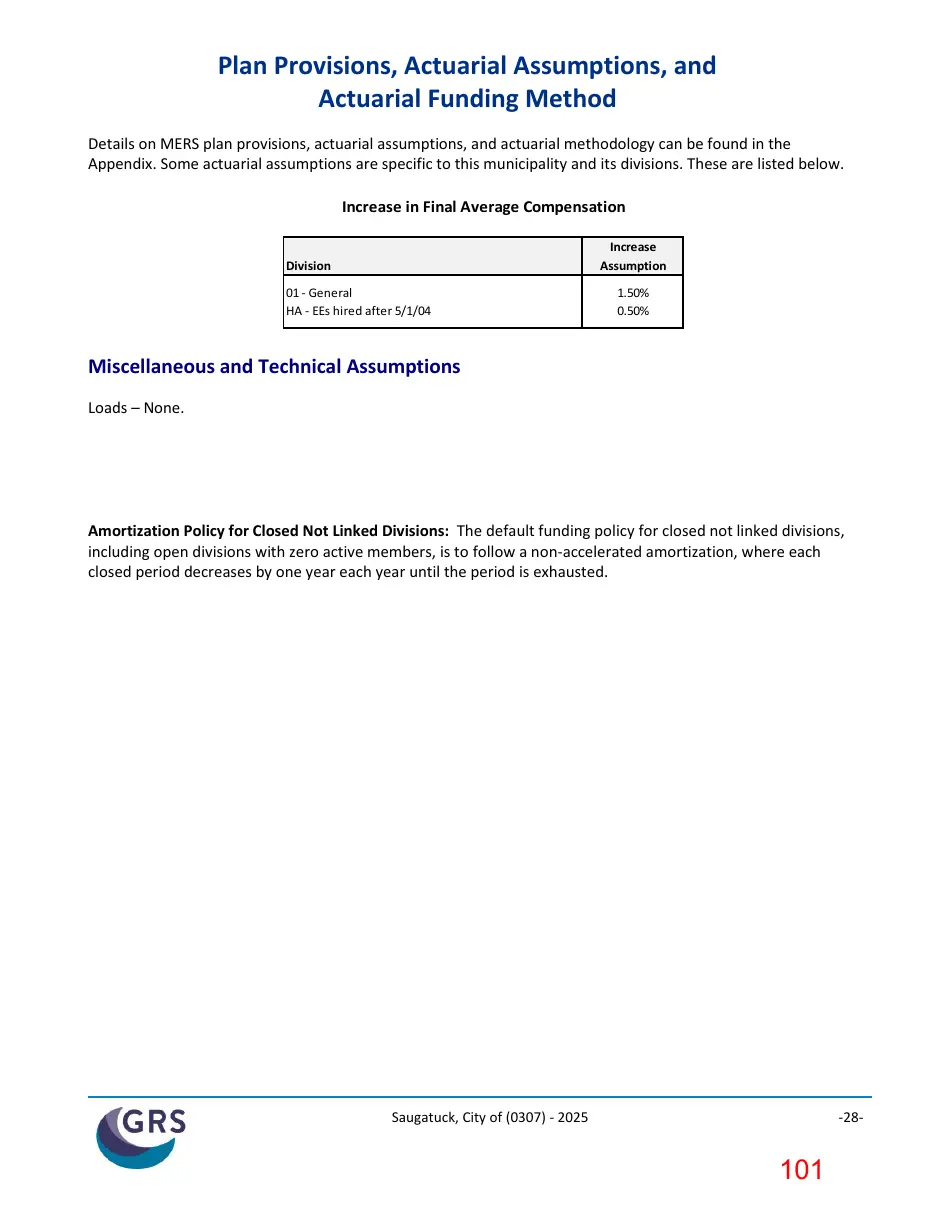
Plan Provisions, Actuarial Assumptions, and Actuarial Funding Method Details on MERS plan provisions, actuarial assumptions, and actuarial methodology can be found in the Appendix. Some actuarial assumptions are specific to this municipality and its divisions. These are listed below. Increase in Final Average Compensation Increase Assumption
Division 01 - General HA - EEs hired after 5/1/04
1.50% 0.50%
Miscellaneous and Technical Assumptions Loads – None.
Amortization Policy for Closed Not Linked Divisions: The default funding policy for closed not linked divisions, including open divisions with zero active members, is to follow a non-accelerated amortization, where each closed period decreases by one year each year until the period is exhausted.
Saugatuck, City of (0307) - 2025
-28-
Page 102
Text of page 102
Risk Commentary Determination of the accrued liability, the employer contribution, and the funded ratio requires the use of assumptions regarding future economic and demographic experience. Risk measures, as illustrated in this report, are intended to aid in the understanding of the effects of future experience differing from the assumptions used in the course of the actuarial valuation. Risk measures may also help with illustrating the potential volatility in the accrued liability, the actuarially determined contribution and the funded ratio that result from the differences between actual experience and the actuarial assumptions. Future actuarial measurements may differ significantly from the current measurements presented in this report due to such factors as the following: plan experience differing from that anticipated by the economic or demographic assumptions; changes in economic or demographic assumptions due to changing conditions; increases or decreases expected as part of the natural operation of the methodology used for these measurements (such as the end of an amortization period, or additional cost or contribution requirements based on the Plan’s funded status); and changes in Plan provisions or applicable law. The scope of an actuarial valuation does not include an analysis of the potential range of such future measurements. Examples of risk that may reasonably be anticipated to significantly affect the plan’s future financial condition include: • Investment Risk – actual investment returns may differ from the expected returns; • Asset/Liability Mismatch – changes in asset values may not match changes in liabilities, thereby altering the gap between the accrued liability and assets and consequently altering the funded status and contribution requirements; • Salary and Payroll Risk – actual salaries and total payroll may differ from expected, resulting in actual future accrued liability and contributions differing from expected; • Longevity Risk – members may live longer or shorter than expected and receive pensions for a period of time other than assumed; and • Other Demographic Risks – members may terminate, retire or become disabled at times or with benefits other than assumed resulting in actual future accrued liability and contributions differing from expected. The effects of certain trends in experience can generally be anticipated. For example, if the investment return since the most recent actuarial valuation is less (or more) than the assumed rate, the cost of the plan can be expected to increase (or decrease). Likewise, if longevity is improving (or worsening), increases (or decreases) in cost can be anticipated.
Saugatuck, City of (0307) - 2025
-29-
Page 103
Text of page 103
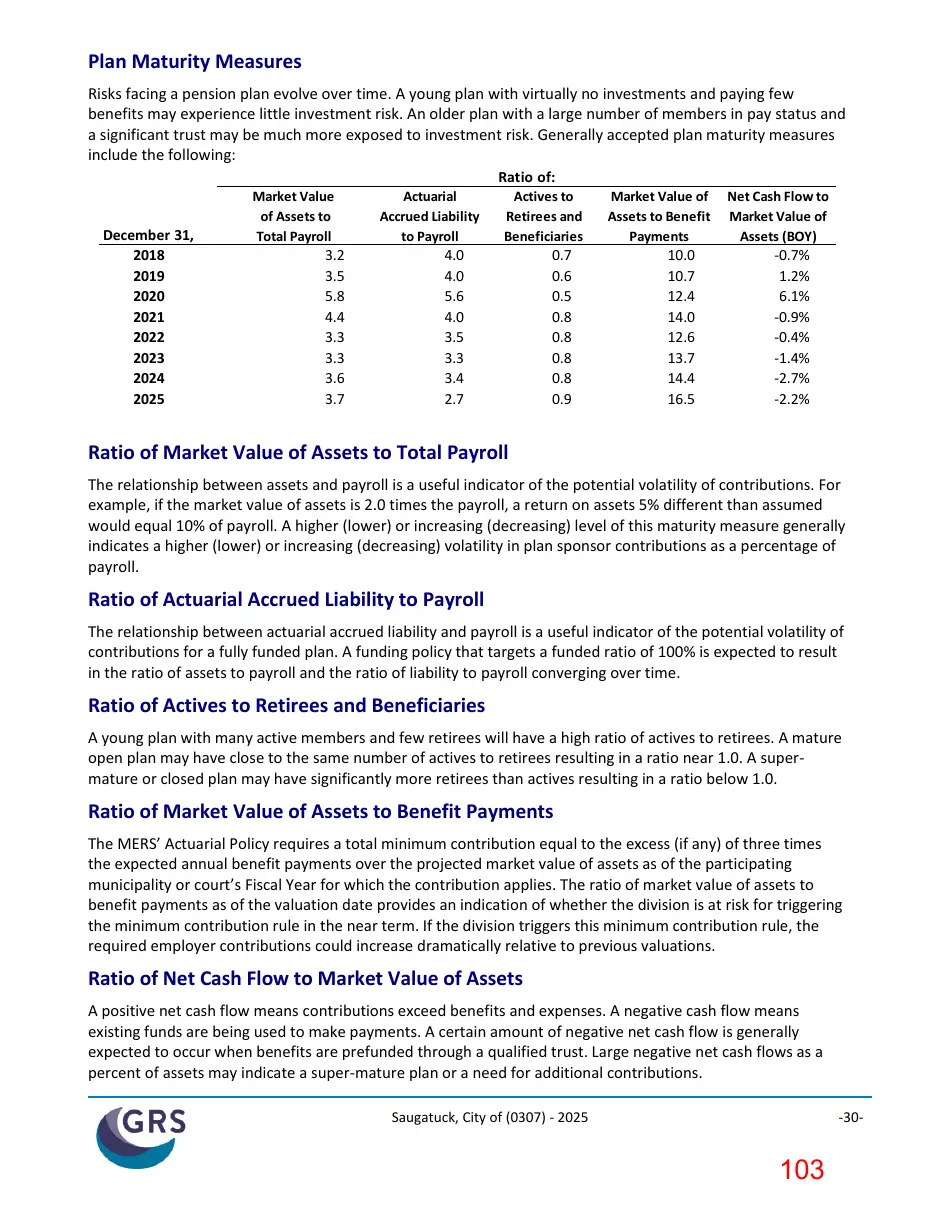
Plan Maturity Measures Risks facing a pension plan evolve over time. A young plan with virtually no investments and paying few benefits may experience little investment risk. An older plan with a large number of members in pay status and a significant trust may be much more exposed to investment risk. Generally accepted plan maturity measures include the following: Ratio of:
December 31, 2018 2019 2020 2021 2022 2023 2024 2025
Market Value of Assets to Total Payroll
3.2 3.5 5.8 4.4 3.3 3.3 3.6 3.7
Actuarial Accrued Liability to Payroll
Actives to Retirees and Beneficiaries
4.0 4.0 5.6 4.0 3.5 3.3 3.4 2.7
0.7 0.6 0.5 0.8 0.8 0.8 0.8 0.9
Market Value of Assets to Benefit Payments
10.0 10.7 12.4 14.0 12.6 13.7 14.4 16.5
Net Cash Flow to Market Value of Assets (BOY)
-0.7% 1.2% 6.1% -0.9% -0.4% -1.4% -2.7% -2.2%
Ratio of Market Value of Assets to Total Payroll The relationship between assets and payroll is a useful indicator of the potential volatility of contributions. For example, if the market value of assets is 2.0 times the payroll, a return on assets 5% different than assumed would equal 10% of payroll. A higher (lower) or increasing (decreasing) level of this maturity measure generally indicates a higher (lower) or increasing (decreasing) volatility in plan sponsor contributions as a percentage of payroll.
Ratio of Actuarial Accrued Liability to Payroll The relationship between actuarial accrued liability and payroll is a useful indicator of the potential volatility of contributions for a fully funded plan. A funding policy that targets a funded ratio of 100% is expected to result in the ratio of assets to payroll and the ratio of liability to payroll converging over time.
Ratio of Actives to Retirees and Beneficiaries A young plan with many active members and few retirees will have a high ratio of actives to retirees. A mature open plan may have close to the same number of actives to retirees resulting in a ratio near 1.0. A supermature or closed plan may have significantly more retirees than actives resulting in a ratio below 1.0.
Ratio of Market Value of Assets to Benefit Payments The MERS’ Actuarial Policy requires a total minimum contribution equal to the excess (if any) of three times the expected annual benefit payments over the projected market value of assets as of the participating municipality or court’s Fiscal Year for which the contribution applies. The ratio of market value of assets to benefit payments as of the valuation date provides an indication of whether the division is at risk for triggering the minimum contribution rule in the near term. If the division triggers this minimum contribution rule, the required employer contributions could increase dramatically relative to previous valuations.
Ratio of Net Cash Flow to Market Value of Assets A positive net cash flow means contributions exceed benefits and expenses. A negative cash flow means existing funds are being used to make payments. A certain amount of negative net cash flow is generally expected to occur when benefits are prefunded through a qualified trust. Large negative net cash flows as a percent of assets may indicate a super-mature plan or a need for additional contributions. Saugatuck, City of (0307) - 2025
-30-
Page 104
Text of page 104
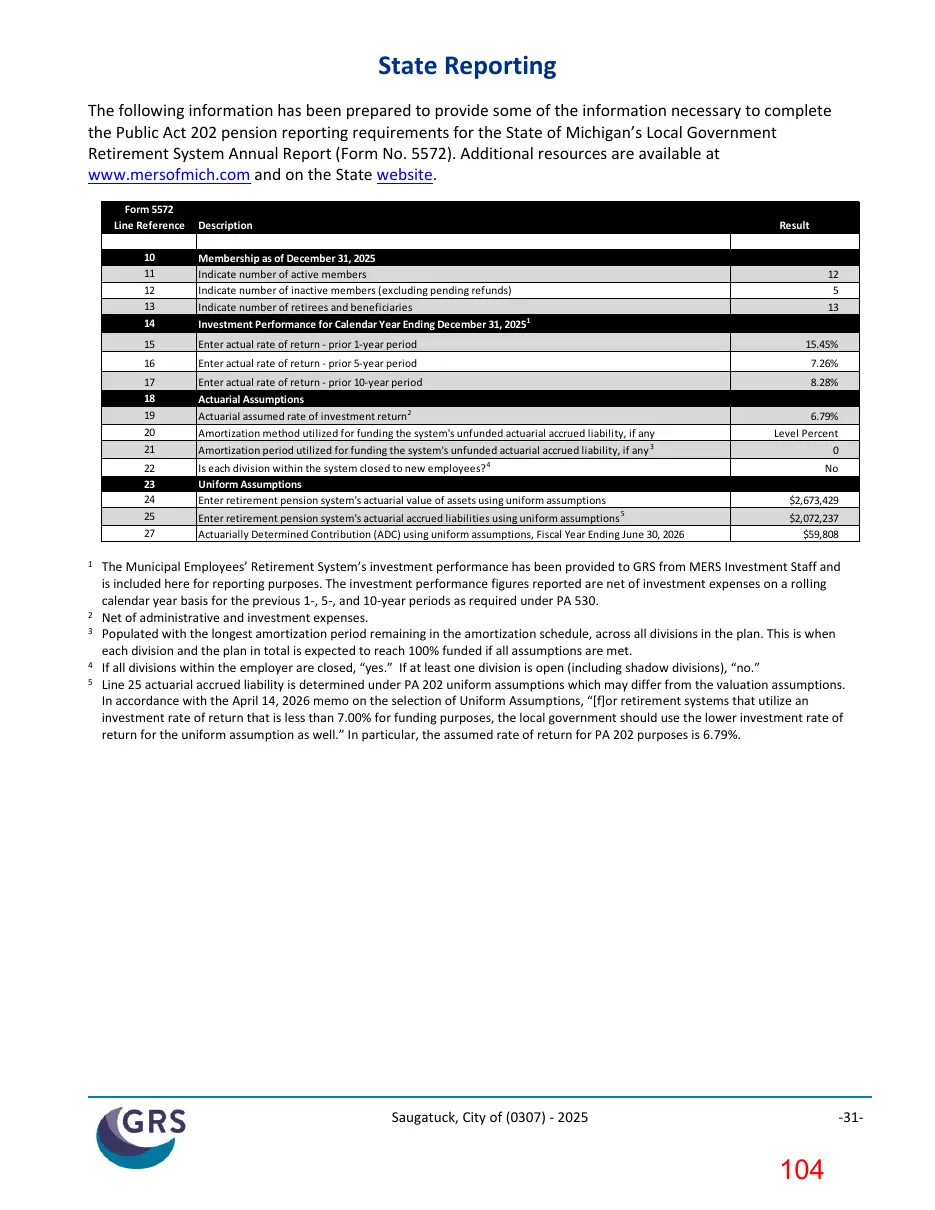
State Reporting The following information has been prepared to provide some of the information necessary to complete the Public Act 202 pension reporting requirements for the State of Michigan’s Local Government Retirement System Annual Report (Form No. 5572). Additional resources are available at www.mersofmich.com and on the State website. Form 5572 Line Reference
Description
Result
10 11 12 13 14
Membership as of December 31, 2025 Indicate number of active members Indicate number of inactive members (excluding pending refunds) Indicate number of retirees and beneficiaries
Enter actual rate of return - prior 1-year period
15.45%
Enter actual rate of return - prior 5-year period
7.26%
17 18 19 20 21
Enter actual rate of return - prior 10-year period Actuarial Assumptions
8.28%
22 23 24 25 27
Is each division within the system closed to new employees? 4 Uniform Assumptions Enter retirement pension system's actuarial value of assets using uniform assumptions
$2,673,429
Enter retirement pension system's actuarial accrued liabilities using uniform assumptions 5 Actuarially Determined Contribution (ADC) using uniform assumptions, Fiscal Year Ending June 30, 2026
$2,072,237 $59,808
12 5 13
Investment Performance for Calendar Year Ending December 31, 20251
Actuarial assumed rate of investment return 2 Amortization method utilized for funding the system's unfunded actuarial accrued liability, if any
6.79% Level Percent
Amortization period utilized for funding the system's unfunded actuarial accrued liability, if any 3
0 No
The Municipal Employees’ Retirement System’s investment performance has been provided to GRS from MERS Investment Staff and is included here for reporting purposes. The investment performance figures reported are net of investment expenses on a rolling calendar year basis for the previous 1-, 5-, and 10-year periods as required under PA 530. 2 Net of administrative and investment expenses. 3 Populated with the longest amortization period remaining in the amortization schedule, across all divisions in the plan. This is when each division and the plan in total is expected to reach 100% funded if all assumptions are met. 4 If all divisions within the employer are closed, “yes.” If at least one division is open (including shadow divisions), “no.” 5 Line 25 actuarial accrued liability is determined under PA 202 uniform assumptions which may differ from the valuation assumptions. In accordance with the April 14, 2026 memo on the selection of Uniform Assumptions, “[f]or retirement systems that utilize an investment rate of return that is less than 7.00% for funding purposes, the local government should use the lower investment rate of return for the uniform assumption as well.” In particular, the assumed rate of return for PA 202 purposes is 6.79%.
Saugatuck, City of (0307) - 2025
-31-
Page 105
Text of page 105
Treasurer Report
July 13, 2026
Tax Administration • • • • •
Completed summer tax bill preparation, printing, mailing, and related duplicateaddress/deferment review. Committed the summer tax roll and uploaded the tax file to the County. Processed and distributed tax file information for mortgage companies and completed related FOIA response. Processed summer property tax disbursements. Reviewed tax-related GL/reporting needs for KLSWA and Warnock Drain collections.
Accounts Payable • •
Processed regular payables for Council review and authorization. Followed up on delayed vendor orders and outstanding invoices to support timely payment processing
Payroll & Benefits • • • •
Processed regular payrolls and related disbursements, including holiday deadline adjustments. Completed payroll setup/reactivation for seasonal employees and continued refinement of seasonal payroll processes. Completed payroll-related monthly and quarterly reporting. Reviewed and documented health insurance renewal materials, including PriorityHealth renewal impact, plan alternatives, employee cost/coverage considerations, and Act 152 compliance. Prepared and supported Council materials related to health insurance renewal and PA 152 exemption.
Financial Management • •
Completed the May bank reconciliation, including correction of reconciliation issues. Entered the FY 2025–2026 budget amendment and distributed final year-end budget updates to staff.
Page 106
Text of page 106
Investments and Banking • • • •
Presented investment activity update to Council. Reviewed banking and credit card processing options for beach operations, including Square and Huntington/Clover backup processing. Advanced setup and testing of backup credit card processing to support revenue continuity. Continued review of MNBCard access and beach credit card reporting/reconciliation needs.
Projects, Assets, and Insurance • •
Prepared Council materials for property/liability insurance renewal, including renewal cost changes and premium increase explanation. Continued review of Maple Street project expense allocations and completed Township invoice for its share of project billing.
Miscellaneous / Administrative • •
Continued Oval Beach and Culver Street revenue processing, reconciliation, and cash-handling support. Helped address temporary Oval Beach internet connectivity and cash/change access issues.
Page 107
Text of page 107
City Clerk Monthly Report Elections • August 4, 2026 – Primary o Ballot: View Here o Ballot Proposals for August 4, 2026: Allegan County: SENIOR CITIZEN SERVICES MILLAGE RENEWAL PROPOSAL Interurban Transit Authority: INTERURBAN TRANSIT AUTHORITY PUBLIC TRANSPORTATION MILLAGE PROPOSAL Saugatuck-Douglas District Library: LIBRARY MILLAGE PROPOSAL • November 3, 2026 – General • 9-Days of Early Voting agreement executed with the City of Village of the Douglas and Saugatuck Township to hold Tri-Community early voting site at the City of the Village of Douglas City Hall. • Residents can register to vote here: https://www.michigan.gov/sos/elections/voting/register-to-vote#HowToRegister Training • Clerk Wolters attended the following in-person election training: o Election Inspector, Receiving Board and 9-Days Early Voting. • Clerk Williams attended the following in-person election training: o Chairperson, Election Inspector, Receiving Board and 9-Days Early Voting. Meetings • Prepared agendas, packets, and minutes for the following bodies: o Two City Council Workshops o Two City Council Regular o Historic District Commission
Page 108
Text of page 108
Planning Commission o Parks and Public Works Committee Participated in: o Maple Street Construction Update o Parking Improvements Task Force o Tri-Community 9-Days Early Voting Planning Session o Department Head Meeting o Monthly City Manager One on One o DPW/Clerk Department Meeting o
Special Events • Special event applications received for processing: o Movie in the Park event date: 8-14-26. o Bike Club Ride event date: 9-20-26. • Upcoming Special events process completed: o Music in the Park event dates: Wednesdays between 6-17-26 – 9-2-26. o SDAC Art Fairs event dates: July 25 & 26. o Venetian Festival event dates: 7-24-26 and 7-25-26. o Saugatuck Farmers Market – The Market at SCA event date: 7-31-26. o Sidewalk Sales event date: 8-13-26. o Art in the Park event date: 9-12-26. o Mt. Baldhead Challenge event date: 9-12-26. o Chili Cook-off event date: 10-11-26. o Art Coast Food & Wine Festival event dates: 11-5-26 through 11-7-26. Administrative & General • Processed 48 zoning permit payments. • Assisted in mailing tax bills. • Mailed 298 Absentee Ballots • 3 FOIA requests. • Wicks Park boat slips - We have 1 open slips, first come, first serve - application here. • Created and distributed 28 community E-News blasts. • City Staff handled a total of 651 incoming phone calls. • City Hall Remodel: Second round of renderings have been received. • Managed front counter operations.
Page 109
Text of page 109
June 2026 Department of Planning & Zoning Report Monthly Update Overview • • •
Continuing development review and interdepartmental coordination. Comprehensive Plan outline proposal presented to the Planning Commission. Comprehensive Plan mapping including: Shoreline Features, Sidewalks, Existing Land Use, Surrounding Communities Future Land Use, Character Analysis, Topography, and Natural Features. Attended stakeholder meeting with a community walking group to discuss mobility planning.
Action & Progress • • • • • • • • • • • •
Participated in Planning Commission & Zoning Board of Appeals interviews and offered recommendations. Welcomed a new Planning Commissioner and Zoning Board of Appeals member. Shared materials and resources. Enrolled newest Planning Commissioner in the MSU Extension Citizen Planner course. Continued notice updates for STR licenses in R-1 Districts for an opportunity halfway through the year. Fielded questions and concerns from residents. Continued STR administration, including resident meetings, application guidance, compliance checks related to property transfers, and coordination with Granicus. Coordination with Fire Department to address property maintenance concerns. Coordinated multiple zoning and policy matters with legal counsel, including STR enforcement cases, site sewer connection, and enforcement strategy. Maintained ongoing coordination with the City Engineer and planning consultant on active and proposed development projects. Created action plan with planning consultant for Comprehensive Plan drafting. Began draft and compiled data for the Comprehensive Plan. Attended webinar Public Land for Public Good. Joined the Michigan Association of Planning Social Equity Committee.
Page 110
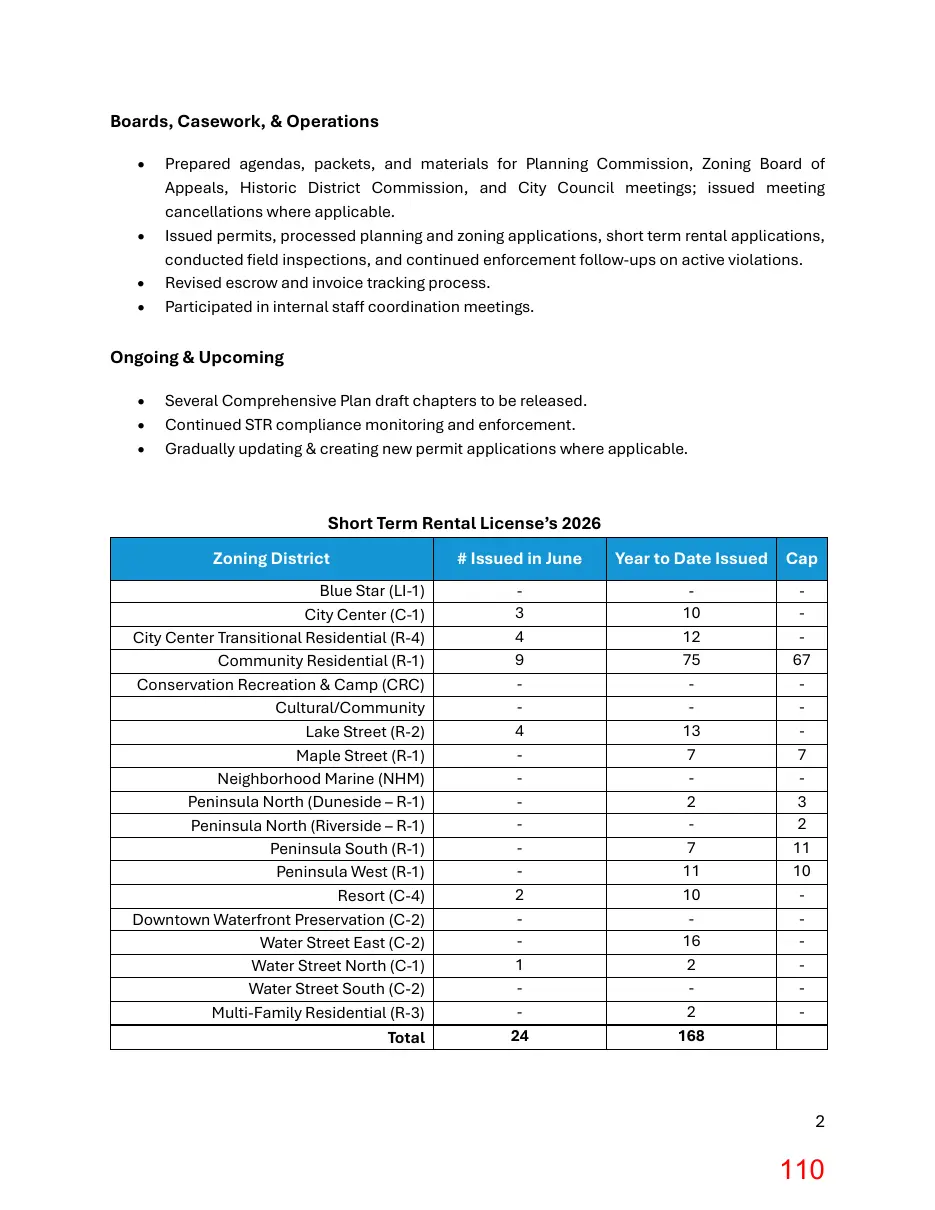
Text of page 110
Boards, Casework, & Operations •
Prepared agendas, packets, and materials for Planning Commission, Zoning Board of Appeals, Historic District Commission, and City Council meetings; issued meeting cancellations where applicable. Issued permits, processed planning and zoning applications, short term rental applications, conducted field inspections, and continued enforcement follow-ups on active violations. Revised escrow and invoice tracking process. Participated in internal staff coordination meetings.
Ongoing & Upcoming • • •
Several Comprehensive Plan draft chapters to be released. Continued STR compliance monitoring and enforcement. Gradually updating & creating new permit applications where applicable.
Short Term Rental License’s 2026 Zoning District
# Issued in June
Blue Star (LI-1) City Center (C-1) City Center Transitional Residential (R-4) Community Residential (R-1) Conservation Recreation & Camp (CRC) Cultural/Community Lake Street (R-2) Maple Street (R-1) Neighborhood Marine (NHM) Peninsula North (Duneside – R-1) Peninsula North (Riverside – R-1) Peninsula South (R-1) Peninsula West (R-1) Resort (C-4) Downtown Waterfront Preservation (C-2) Water Street East (C-2) Water Street North (C-1) Water Street South (C-2) Multi-Family Residential (R-3) Total
3 4 9 4 2 1 24
Year to Date Issued Cap 10 12 75 13 7 2 7 11 10 16 2 2 168
67 7 3 2 11 10 -
Page 111
Text of page 111
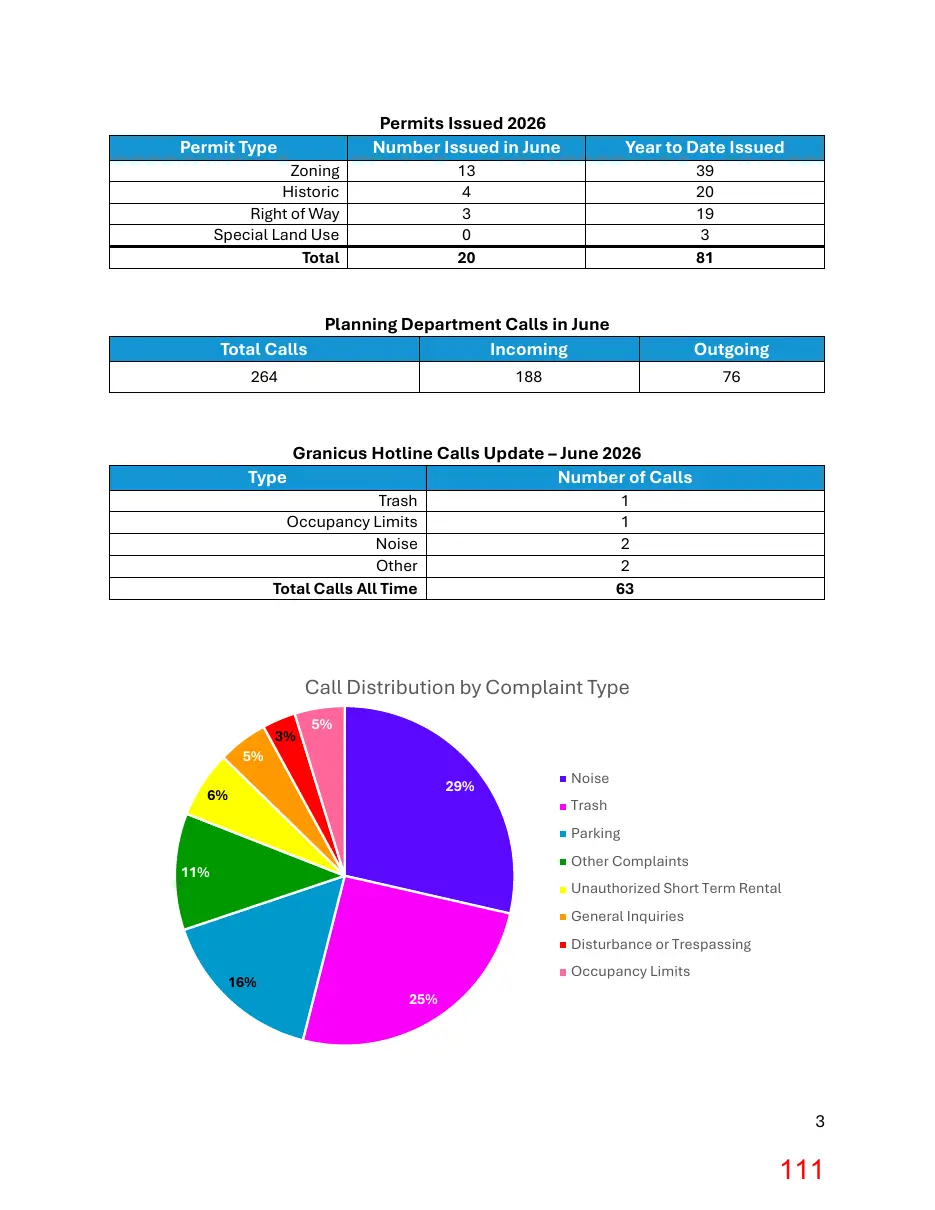
Permit Type
Permits Issued 2026 Number Issued in June
Year to Date Issued
13 4 3 0 20
39 20 19 3 81
Zoning Historic Right of Way Special Land Use Total
Planning Department Calls in June Total Calls Incoming 264
Outgoing
Granicus Hotline Calls Update – June 2026 Type Number of Calls Trash Occupancy Limits Noise Other Total Calls All Time
1 1 2 2 63
Call Distribution by Complaint Type 3%
5% 29%
Noise Trash Parking Other Complaints
11%
Unauthorized Short Term Rental General Inquiries Disturbance or Trespassing 16%
Occupancy Limits 25%
Page 112
Text of page 112
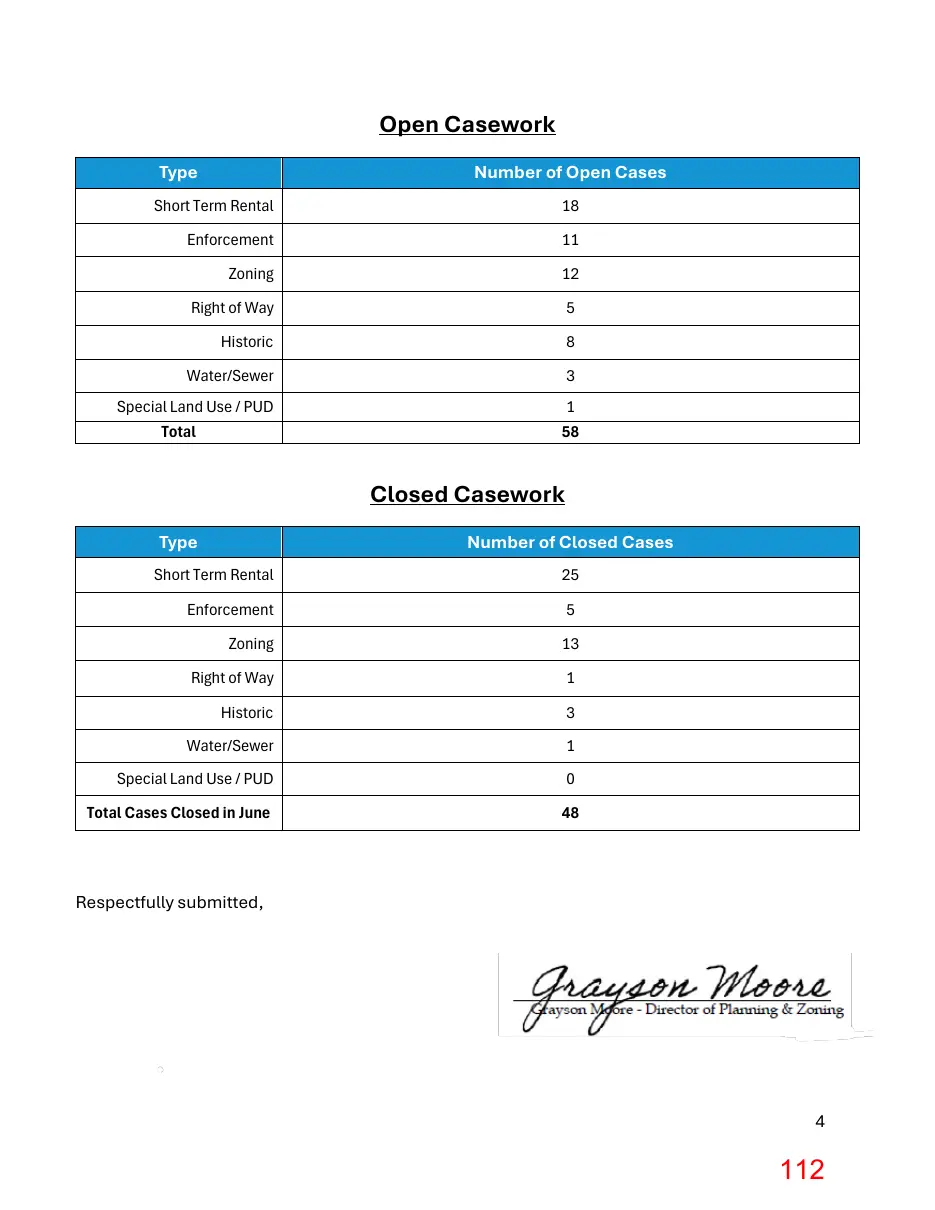
Open Casework Type
Number of Open Cases
Short Term Rental
Enforcement
Zoning
Right of Way
Historic
Water/Sewer
Special Land Use / PUD
Total
Closed Casework Type
Number of Closed Cases
Short Term Rental
Enforcement
Zoning
Right of Way
Historic
Water/Sewer
Special Land Use / PUD
Total Cases Closed in June
Respectfully submitted,
Page 113
Text of page 113
Department of Public Works Below is a summary of notable activities carried out by the Department of Public Works since the last summary provided to City Council at the June 1 regular meeting.
Staff Update: -
Public Works staff have been exceptionally busy this month, and I want to thank the team for their flexibility and responsiveness in addressing work orders as they arise throughout the day. Their willingness to adapt to changing priorities is greatly appreciated and helps keep our operations running smoothly.
Oval Beach staff have also had a busy month, and we now have sufficient summer staffing in place to keep operations running smoothly. Angela has done an excellent job coordinating the team and ensuring daily operations continue to run efficiently.
Oval Beach: -
During the July 4th holiday weekend, Oval Beach experienced a power outage that temporarily disrupted operations. Because the well pump could not be powered by the generator, restroom access was limited until electricity was restored. Power was restored later that day, and normal operations resumed without further issues.
DPW staff responded promptly to the power outage at Oval Beach. After identifying an issue with the generator, they contacted a local electrician for assistance. Through their quick response and troubleshooting efforts, they were able to keep most beach operations running until utility power was restored.
Tree Work: -
We had a tree go down on our steps at near Griffith & Mary Street, since it was later in the day and Consumers Energy had to clear some lines, we cleared the tree the next morning and cleaned up the area.
DPW staff responded promptly to a call from the Fire Department regarding a fallen tree on Perryman. The team quickly cleared the roadway before it caused any significant disruption to traffic.
Page 114
Text of page 114
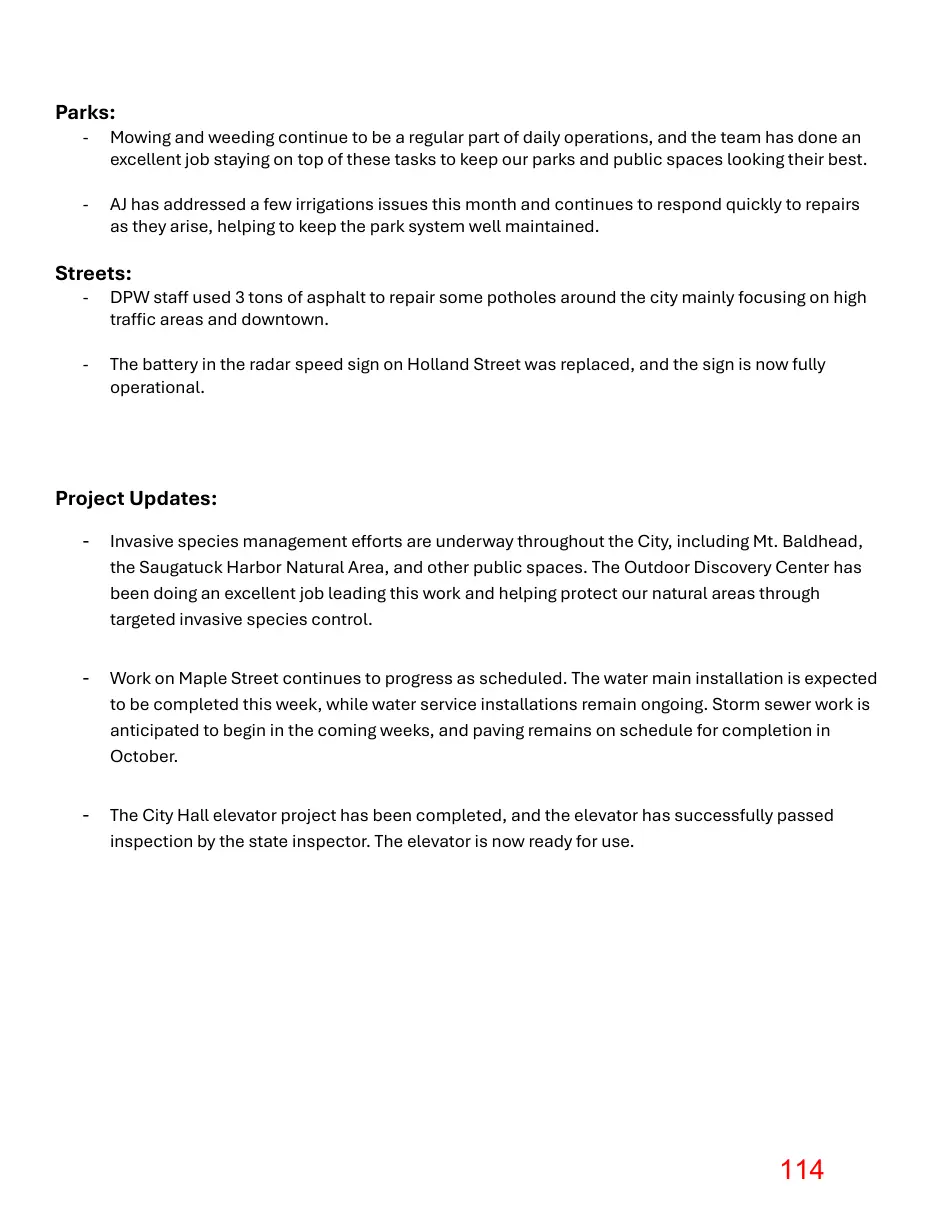
Parks: -
Mowing and weeding continue to be a regular part of daily operations, and the team has done an excellent job staying on top of these tasks to keep our parks and public spaces looking their best.
AJ has addressed a few irrigations issues this month and continues to respond quickly to repairs as they arise, helping to keep the park system well maintained.
Streets: -
DPW staff used 3 tons of asphalt to repair some potholes around the city mainly focusing on high traffic areas and downtown.
The battery in the radar speed sign on Holland Street was replaced, and the sign is now fully operational.
Project Updates: - Invasive species management efforts are underway throughout the City, including Mt. Baldhead, the Saugatuck Harbor Natural Area, and other public spaces. The Outdoor Discovery Center has been doing an excellent job leading this work and helping protect our natural areas through targeted invasive species control.
- Work on Maple Street continues to progress as scheduled. The water main installation is expected to be completed this week, while water service installations remain ongoing. Storm sewer work is anticipated to begin in the coming weeks, and paving remains on schedule for completion in October.
- The City Hall elevator project has been completed, and the elevator has successfully passed inspection by the state inspector. The elevator is now ready for use.
Page 115
Text of page 115
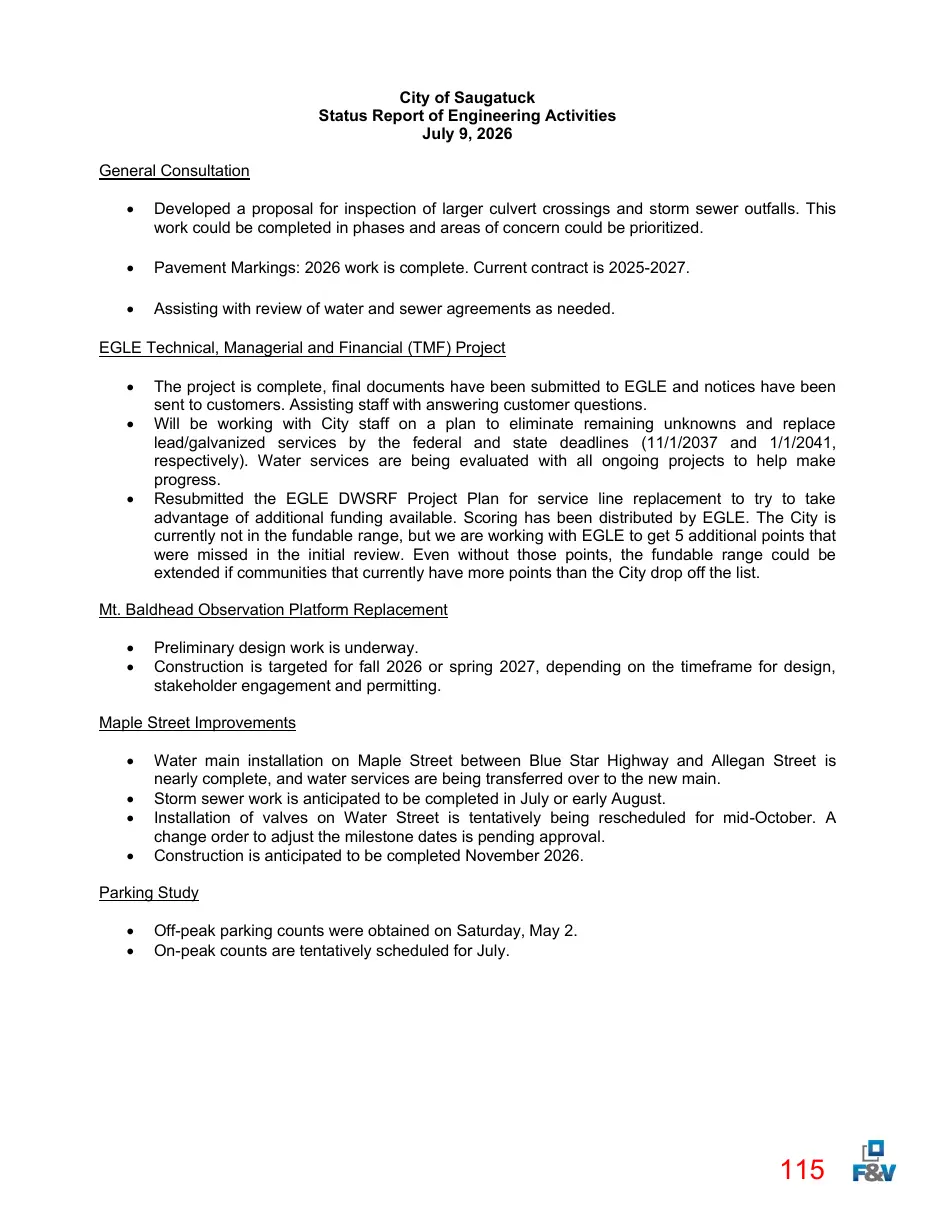
City of Saugatuck Status Report of Engineering Activities July 9, 2026 General Consultation •
Developed a proposal for inspection of larger culvert crossings and storm sewer outfalls. This work could be completed in phases and areas of concern could be prioritized.
Pavement Markings: 2026 work is complete. Current contract is 2025-2027.
Assisting with review of water and sewer agreements as needed.
EGLE Technical, Managerial and Financial (TMF) Project • •
The project is complete, final documents have been submitted to EGLE and notices have been sent to customers. Assisting staff with answering customer questions. Will be working with City staff on a plan to eliminate remaining unknowns and replace lead/galvanized services by the federal and state deadlines (11/1/2037 and 1/1/2041, respectively). Water services are being evaluated with all ongoing projects to help make progress. Resubmitted the EGLE DWSRF Project Plan for service line replacement to try to take advantage of additional funding available. Scoring has been distributed by EGLE. The City is currently not in the fundable range, but we are working with EGLE to get 5 additional points that were missed in the initial review. Even without those points, the fundable range could be extended if communities that currently have more points than the City drop off the list.
Mt. Baldhead Observation Platform Replacement • •
Preliminary design work is underway. Construction is targeted for fall 2026 or spring 2027, depending on the timeframe for design, stakeholder engagement and permitting.
Maple Street Improvements • • • •
Water main installation on Maple Street between Blue Star Highway and Allegan Street is nearly complete, and water services are being transferred over to the new main. Storm sewer work is anticipated to be completed in July or early August. Installation of valves on Water Street is tentatively being rescheduled for mid-October. A change order to adjust the milestone dates is pending approval. Construction is anticipated to be completed November 2026.
Parking Study • •
Off-peak parking counts were obtained on Saturday, May 2. On-peak counts are tentatively scheduled for July.
Page 116
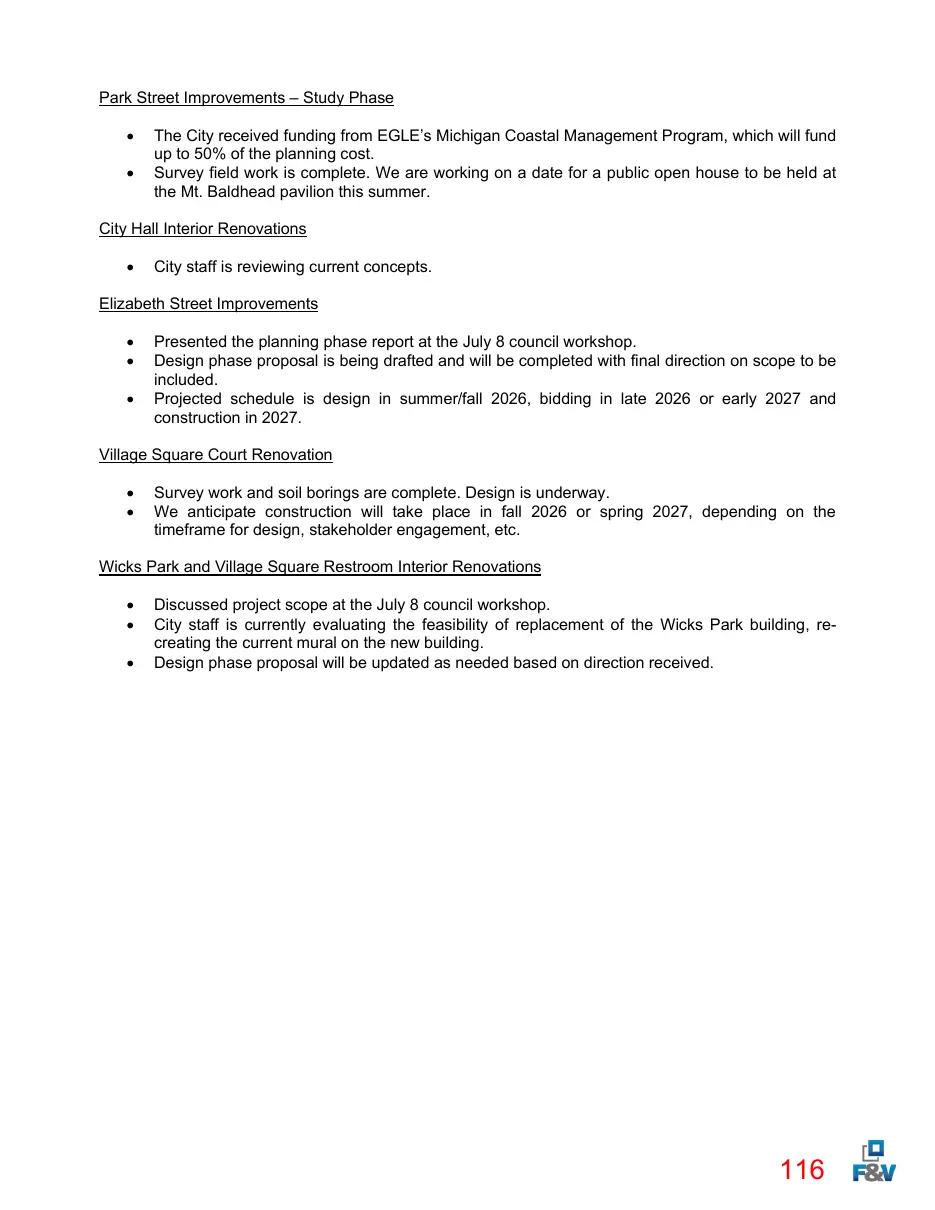
Text of page 116
Park Street Improvements – Study Phase • •
The City received funding from EGLE’s Michigan Coastal Management Program, which will fund up to 50% of the planning cost. Survey field work is complete. We are working on a date for a public open house to be held at the Mt. Baldhead pavilion this summer.
City Hall Interior Renovations •
City staff is reviewing current concepts.
Elizabeth Street Improvements • • •
Presented the planning phase report at the July 8 council workshop. Design phase proposal is being drafted and will be completed with final direction on scope to be included. Projected schedule is design in summer/fall 2026, bidding in late 2026 or early 2027 and construction in 2027.
Village Square Court Renovation • •
Survey work and soil borings are complete. Design is underway. We anticipate construction will take place in fall 2026 or spring 2027, depending on the timeframe for design, stakeholder engagement, etc.
Wicks Park and Village Square Restroom Interior Renovations • • •
Discussed project scope at the July 8 council workshop. City staff is currently evaluating the feasibility of replacement of the Wicks Park building, recreating the current mural on the new building. Design phase proposal will be updated as needed based on direction received.
Page 117
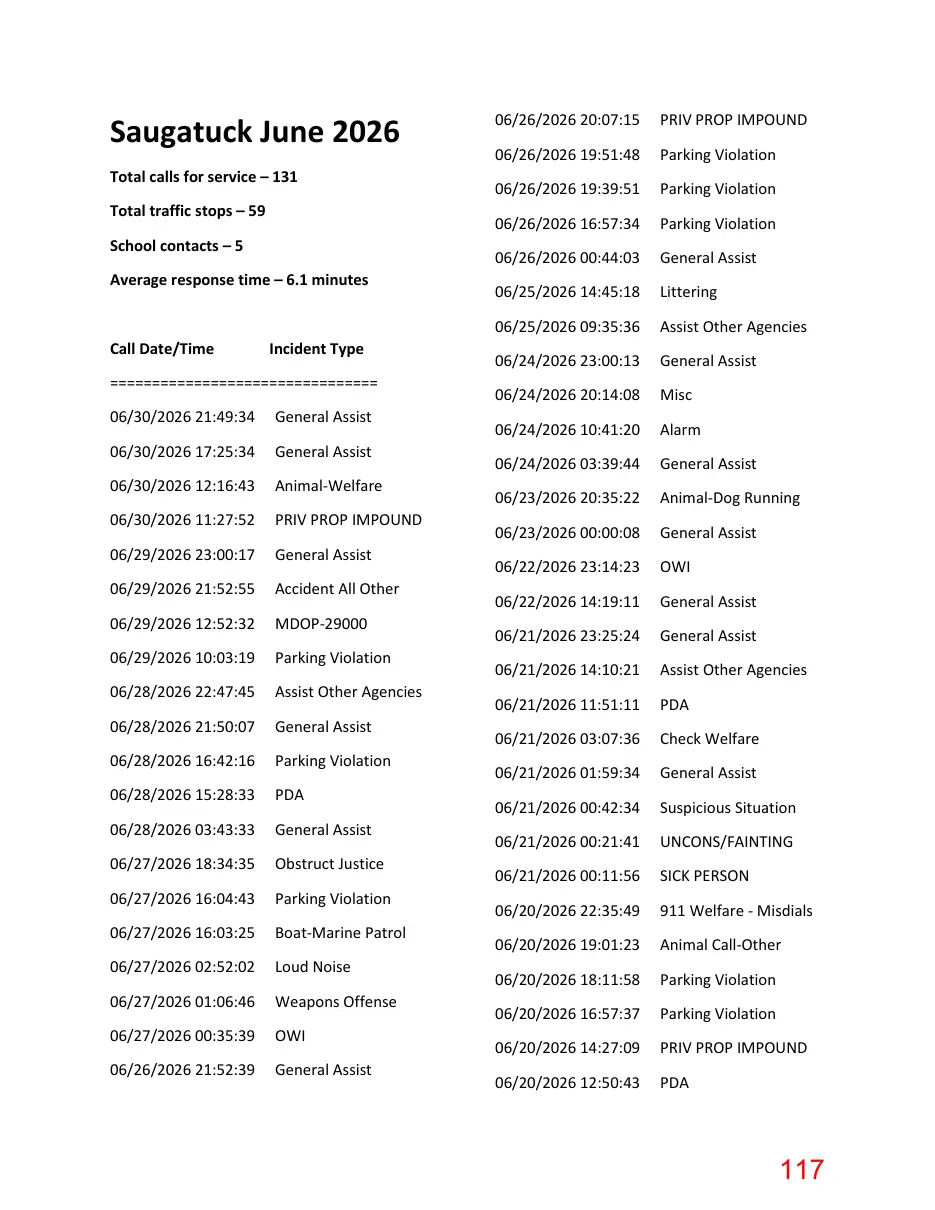
Text of page 117
Saugatuck June 2026 Total calls for service – 131 Total traffic stops – 59 School contacts – 5 Average response time – 6.1 minutes
Call Date/Time
Incident Type
================================ 06/30/2026 21:49:34
General Assist
06/30/2026 17:25:34
General Assist
06/30/2026 12:16:43
Animal-Welfare
06/30/2026 11:27:52
PRIV PROP IMPOUND
06/29/2026 23:00:17
General Assist
06/29/2026 21:52:55
Accident All Other
06/29/2026 12:52:32
MDOP-29000
06/29/2026 10:03:19
Parking Violation
06/28/2026 22:47:45
Assist Other Agencies
06/28/2026 21:50:07
General Assist
06/28/2026 16:42:16
Parking Violation
06/28/2026 15:28:33
PDA
06/28/2026 03:43:33
General Assist
06/27/2026 18:34:35
Obstruct Justice
06/27/2026 16:04:43
Parking Violation
06/27/2026 16:03:25
Boat-Marine Patrol
06/27/2026 02:52:02
Loud Noise
06/27/2026 01:06:46
Weapons Offense
06/27/2026 00:35:39
OWI
06/26/2026 21:52:39
General Assist
06/26/2026 20:07:15
PRIV PROP IMPOUND
06/26/2026 19:51:48
Parking Violation
06/26/2026 19:39:51
Parking Violation
06/26/2026 16:57:34
Parking Violation
06/26/2026 00:44:03
General Assist
06/25/2026 14:45:18
Littering
06/25/2026 09:35:36
Assist Other Agencies
06/24/2026 23:00:13
General Assist
06/24/2026 20:14:08
Misc
06/24/2026 10:41:20
Alarm
06/24/2026 03:39:44
General Assist
06/23/2026 20:35:22
Animal-Dog Running
06/23/2026 00:00:08
General Assist
06/22/2026 23:14:23
OWI
06/22/2026 14:19:11
General Assist
06/21/2026 23:25:24
General Assist
06/21/2026 14:10:21
Assist Other Agencies
06/21/2026 11:51:11
PDA
06/21/2026 03:07:36
Check Welfare
06/21/2026 01:59:34
General Assist
06/21/2026 00:42:34
Suspicious Situation
06/21/2026 00:21:41
UNCONS/FAINTING
06/21/2026 00:11:56
SICK PERSON
06/20/2026 22:35:49
911 Welfare - Misdials
06/20/2026 19:01:23
Animal Call-Other
06/20/2026 18:11:58
Parking Violation
06/20/2026 16:57:37
Parking Violation
06/20/2026 14:27:09
PRIV PROP IMPOUND
06/20/2026 12:50:43
PDA
Page 118
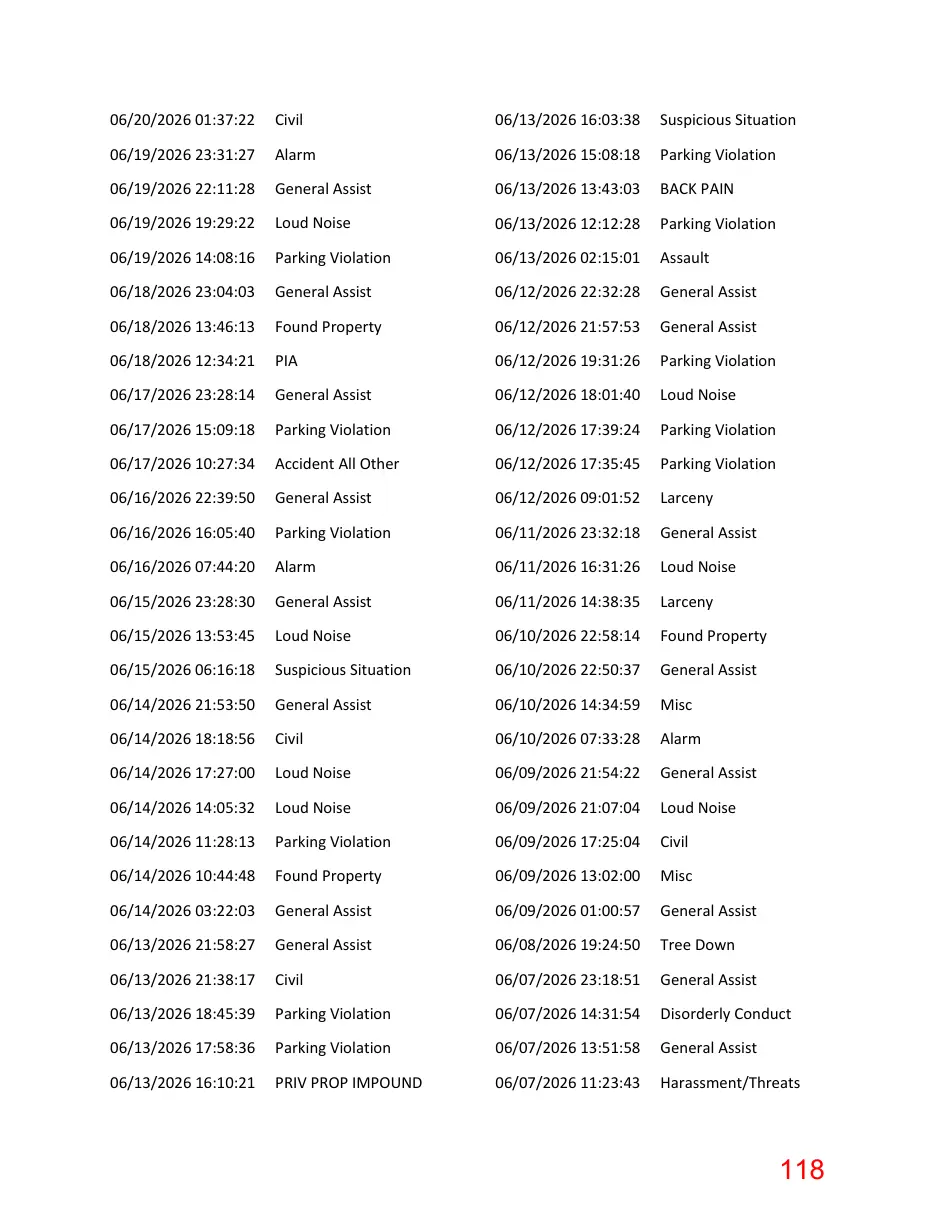
Text of page 118
06/20/2026 01:37:22
Civil
06/13/2026 16:03:38
Suspicious Situation
06/19/2026 23:31:27
Alarm
06/13/2026 15:08:18
Parking Violation
06/19/2026 22:11:28
General Assist
06/13/2026 13:43:03
BACK PAIN
06/19/2026 19:29:22
Loud Noise
06/13/2026 12:12:28
Parking Violation
06/19/2026 14:08:16
Parking Violation
06/13/2026 02:15:01
Assault
06/18/2026 23:04:03
General Assist
06/12/2026 22:32:28
General Assist
06/18/2026 13:46:13
Found Property
06/12/2026 21:57:53
General Assist
06/18/2026 12:34:21
PIA
06/12/2026 19:31:26
Parking Violation
06/17/2026 23:28:14
General Assist
06/12/2026 18:01:40
Loud Noise
06/17/2026 15:09:18
Parking Violation
06/12/2026 17:39:24
Parking Violation
06/17/2026 10:27:34
Accident All Other
06/12/2026 17:35:45
Parking Violation
06/16/2026 22:39:50
General Assist
06/12/2026 09:01:52
Larceny
06/16/2026 16:05:40
Parking Violation
06/11/2026 23:32:18
General Assist
06/16/2026 07:44:20
Alarm
06/11/2026 16:31:26
Loud Noise
06/15/2026 23:28:30
General Assist
06/11/2026 14:38:35
Larceny
06/15/2026 13:53:45
Loud Noise
06/10/2026 22:58:14
Found Property
06/15/2026 06:16:18
Suspicious Situation
06/10/2026 22:50:37
General Assist
06/14/2026 21:53:50
General Assist
06/10/2026 14:34:59
Misc
06/14/2026 18:18:56
Civil
06/10/2026 07:33:28
Alarm
06/14/2026 17:27:00
Loud Noise
06/09/2026 21:54:22
General Assist
06/14/2026 14:05:32
Loud Noise
06/09/2026 21:07:04
Loud Noise
06/14/2026 11:28:13
Parking Violation
06/09/2026 17:25:04
Civil
06/14/2026 10:44:48
Found Property
06/09/2026 13:02:00
Misc
06/14/2026 03:22:03
General Assist
06/09/2026 01:00:57
General Assist
06/13/2026 21:58:27
General Assist
06/08/2026 19:24:50
Tree Down
06/13/2026 21:38:17
Civil
06/07/2026 23:18:51
General Assist
06/13/2026 18:45:39
Parking Violation
06/07/2026 14:31:54
Disorderly Conduct
06/13/2026 17:58:36
Parking Violation
06/07/2026 13:51:58
General Assist
06/13/2026 16:10:21
PRIV PROP IMPOUND
06/07/2026 11:23:43
Harassment/Threats
Page 119
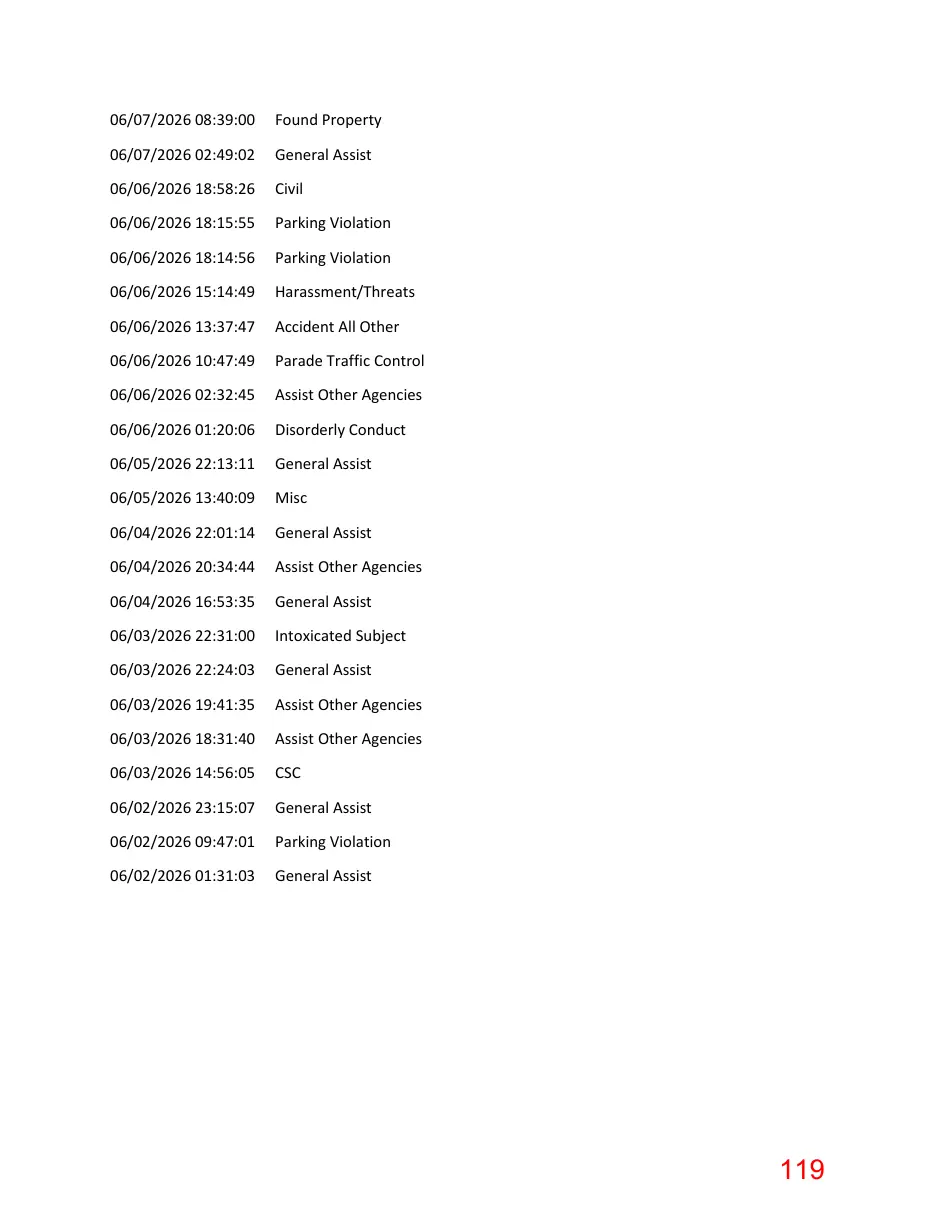
Text of page 119
06/07/2026 08:39:00
Found Property
06/07/2026 02:49:02
General Assist
06/06/2026 18:58:26
Civil
06/06/2026 18:15:55
Parking Violation
06/06/2026 18:14:56
Parking Violation
06/06/2026 15:14:49
Harassment/Threats
06/06/2026 13:37:47
Accident All Other
06/06/2026 10:47:49
Parade Traffic Control
06/06/2026 02:32:45
Assist Other Agencies
06/06/2026 01:20:06
Disorderly Conduct
06/05/2026 22:13:11
General Assist
06/05/2026 13:40:09
Misc
06/04/2026 22:01:14
General Assist
06/04/2026 20:34:44
Assist Other Agencies
06/04/2026 16:53:35
General Assist
06/03/2026 22:31:00
Intoxicated Subject
06/03/2026 22:24:03
General Assist
06/03/2026 19:41:35
Assist Other Agencies
06/03/2026 18:31:40
Assist Other Agencies
06/03/2026 14:56:05
CSC
06/02/2026 23:15:07
General Assist
06/02/2026 09:47:01
Parking Violation
06/02/2026 01:31:03
General Assist