Workshop Agenda item 6A
Audit Presentation, Fiscal Year 2023/2024
City Council Workshop, Wednesday, January 8, 2025
Download these 52 pages, 1.5 MB Whole packet, 90 pages, 2.7 MB
Page 2
Text of page 2
____________________________________________________________________________________
Memorandum To: City of Saugatuck Council From: Nicole Bredeweg, Treasurer/Finance Officer Date: January 6, 2025 RE: Audit Presentation Berthiaume & Company from Saginaw completed the 2023 – 2024 Annual Audit, including auditing the financial statements of the governmental activities, each major fund, and the aggregate remaining fund information. Mr. Ken Berthiaume will be presenting the audited financial statements to the City Council today via Zoom. We have hard copies of the audit at City Hall, or you can review the audit at the following link: https://treas-secure.state.mi.us/LAFDocSearch/ Once on this page, fill in the following dropdown cells: •
County: Allegan-03
Year: 2024
Municipality Type: City
Municipality: Saugatuck, City of
Click on the green Search button and the filed documents will appear. The audit is listed as ‘Audit-Financial Report’ 102 Butler Street P.O. Box 86 Saugatuck, MI 49453 Phone: 269-857-2603 Website: www.saugatuckcity.com
Page 3
Text of page 3
CITY OF SAUGATUCK Allegan County, Michigan
FINANCIAL STATEMENTS June 30, 2024
Page 4
Text of page 4
CITY OF SAUGATUCK
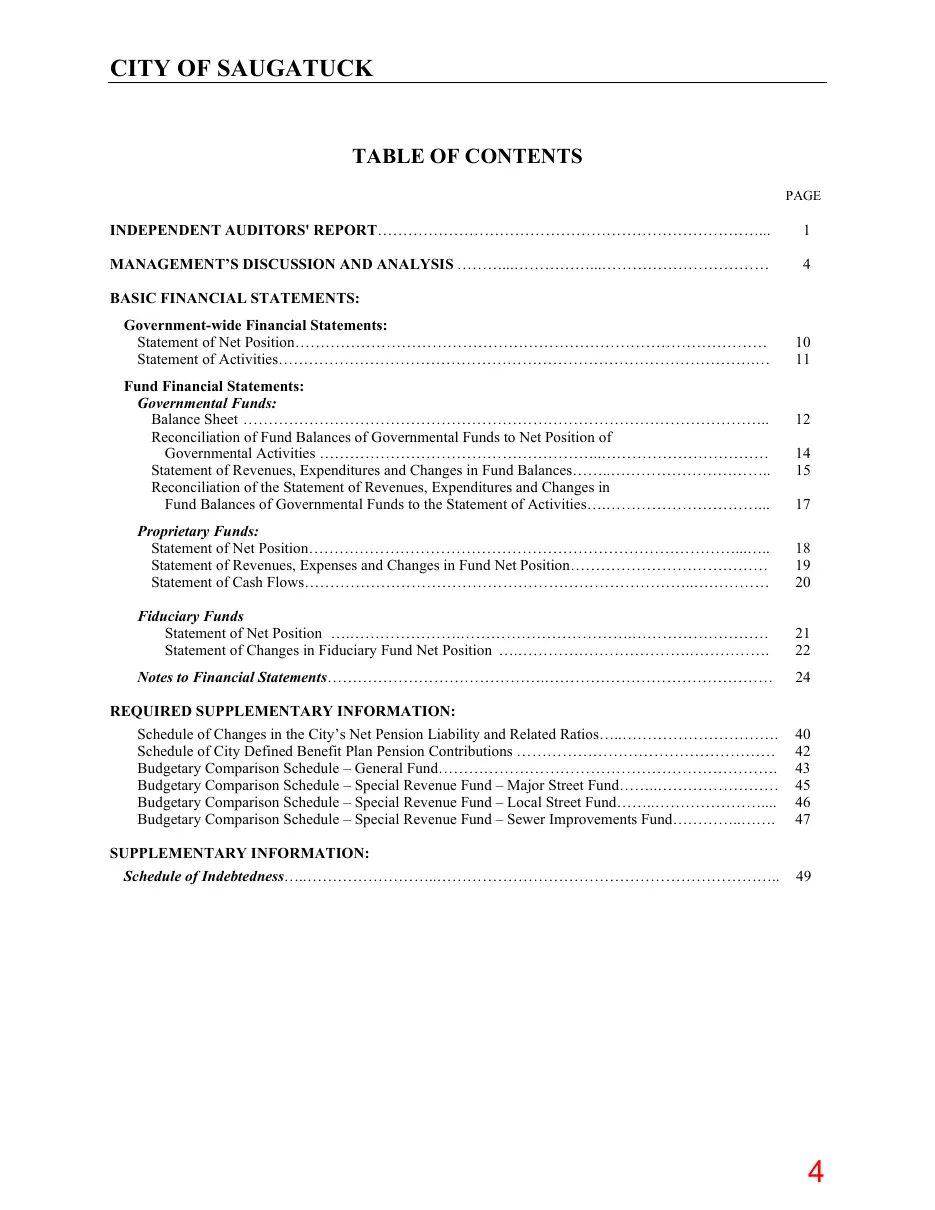
TABLE OF CONTENTS PAGE
INDEPENDENT AUDITORS' REPORT…………………………………………………………………...
MANAGEMENT’S DISCUSSION AND ANALYSIS ………...……………...……………………………
BASIC FINANCIAL STATEMENTS: Government-wide Financial Statements: Statement of Net Position………………………………………………………………………………… Statement of Activities………………………………………………………………………………….… Fund Financial Statements: Governmental Funds: Balance Sheet ………………………………………………………………………………………….. Reconciliation of Fund Balances of Governmental Funds to Net Position of Governmental Activities ………………………………………………..…………………………… Statement of Revenues, Expenditures and Changes in Fund Balances……..………………………….. Reconciliation of the Statement of Revenues, Expenditures and Changes in Fund Balances of Governmental Funds to the Statement of Activities….…………………………...
10 11
12 14 15 17
Proprietary Funds: Statement of Net Position…………………………………………………………………………...….. Statement of Revenues, Expenses and Changes in Fund Net Position………………………………… Statement of Cash Flows…………………………………………………………………..……………
18 19 20
Fiduciary Funds Statement of Net Position ….………………….…………………………….……………………… Statement of Changes in Fiduciary Fund Net Position ….…………………………….…………….
21 22
Notes to Financial Statements…………………………………….………………………………………
REQUIRED SUPPLEMENTARY INFORMATION: Schedule of Changes in the City’s Net Pension Liability and Related Ratios…..…………………………. Schedule of City Defined Benefit Plan Pension Contributions …………………………………………… Budgetary Comparison Schedule – General Fund…………………………………………………………. Budgetary Comparison Schedule – Special Revenue Fund – Major Street Fund……..…………………… Budgetary Comparison Schedule – Special Revenue Fund – Local Street Fund……..………………….... Budgetary Comparison Schedule – Special Revenue Fund – Sewer Improvements Fund…………..…….
40 42 43 45 46 47
SUPPLEMENTARY INFORMATION: Schedule of Indebtedness…..……………………..…………………………………………………………..
Page 5
Text of page 5
INDEPENDENT AUDITORS' REPORT To the Honorable Mayor and Members of City Council City of Saugatuck, Michigan Opinions We have audited the accompanying financial statements of the governmental activities, each major fund and the aggregate remaining fund information of City of Saugatuck as of and for the year ended June 30, 2024, and the related notes to the financial statements, which collectively comprise the City’s basic financial statements as listed in the table of contents. In our opinion, the financial statements referred to above present fairly, in all material respects, the respective financial position of the governmental activities, each major fund and the aggregate remaining fund information of City of Saugatuck as of June 30, 2024, and the respective changes in financial position for the year then ended in accordance with accounting principles generally accepted in the United States of America. Basis for Opinions We conducted our audit in accordance with auditing standards generally accepted in the United States of America. Our standards under those standards are further described in the Auditor’s Responsibilities for the Audit of the Financial Statements section of our report. We are required to be independent of City of Saugatuck and to meet our other ethical responsibilities, in accordance with the relevant ethical requirements relating to our audit. We believe that the audit evidence we have obtained is sufficient and appropriate to provide a basis for our audit opinions. Responsibilities of Management for the Financial Statements Management is responsible for the preparation and fair presentation of the financial statements in accordance with accounting principles generally accepted in the United States of America, and for the design, implementation, and maintenance of internal control relevant to the preparation and fair presentation of financial statements that are free from material misstatement, whether due to fraud or error. In preparing the financial statements, management is required to evaluate whether there are conditions or events, considered in the aggregate, that raise substantial doubt about City of Saugatuck’s ability to continue as a going concern for twelve months beyond the financial statement date, including any currently known information that may raise substantial doubt shortly thereafter. Auditor’s Responsibilities for the Audit of the Financial Statements Our objectives are to obtain reasonable assurance about whether the financial statements as a whole are free from material misstatement, whether due to fraud or error, and to issue an auditor’s report that includes our opinions. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with generally accepted auditing standards will always detect a material misstatement when it exists. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentations, or the override of internal control. Misstatements are considered material if there is substantial likelihood that individually or in the aggregate, they would influence the judgment made by a reasonable user based on financial statements. -1-
Page 6
Text of page 6
To the Honorable Mayor and Members of City Council City of Saugatuck, Michigan In performing an audit in accordance with generally accepted auditing standards, we:
Exercise professional judgment and maintain professional skepticism throughout the audit. Identify and assess the risks of material misstatement of the financial statements, whether due to fraud or error, and design and perform audit procedures responsive to those risks. Such procedures include examining, on a test basis, evidence regarding the amounts and disclosures in the financial statements. Obtain an understanding of internal control relevant to the audit in order to design audit procedures that are appropriate in the circumstances, but not for the purpose of expressing an opinion on the effectiveness of City of Saugatuck’s internal control. Accordingly, no such opinion is expressed. Evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management, as well as evaluate the overall presentation of the financial statements. Conclude whether, in our judgment, there are conditions or events, considered in the aggregate, that raise substantial doubt about City of Saugatuck’s ability to continue as a going concern for a reasonable period of time.
We are required to communicate with those charged with governance regarding, among other matters, the planned scope and timing of the audit, significant audit findings, and certain internal control-related matters that we identified during the audit. Required Supplementary Information Accounting principles generally accepted in the United States of America require that management’s discussion and analysis (pages 4 through 8), schedule of changes in the net pension liability and related ratios (pages 40 through 41), schedule of defined benefit plan pension contributions (page 42), and budgetary comparison information (pages 43 through 47) be presented to supplement the basic financial statements. Such information is the responsibility of management and, although not a part of the basic financial statements, is required by the Governmental Accounting Standards Board who considers it to be an essential part of financial reporting for placing the basic financial statements in an appropriate operational, economic, or historical context. We have applied certain limited procedures to the required supplementary information in accordance with auditing standards generally accepted in the United States of America, which consisted of inquiries of management about the methods of preparing the information and comparing the information for consistency with management’s responses to our inquiries, the basic financial statements, and other knowledge we obtained during our audit of the basic financial statements. We do not express an opinion or provide any assurance on the information because the limited procedures do not provide us with sufficient evidence to express an opinion or provide any assurance. Supplementary Information Our audit was conducted for the purpose of forming opinions on the financial statements that collectively comprise the City of Saugatuck’s basic financial statements. The accompanying supplementary information, as listed in the table of contents, is presented for purposes of additional analysis and are not a required part of the basic financial statements. Such information is the responsibility of management and was derived from and relates directly to the underlying accounting and other records used to prepare the basic financial statements. The information has been subjected to the auditing procedures applied in the audit of the basic financial statements and certain additional procedures, including comparing and reconciling such information directly to the underlying accounting and other records used to prepare the basic financial statements or to the basic financial statements themselves, and other additional procedures in accordance with auditing standards generally accepted in the United States of America. In our opinion, the supplementary information, as listed in the table of contents, is fairly stated, in all material respects, in relation to the basic financial statements as a whole.
Saginaw, Michigan December 13, 2024 -2-
Page 7
Text of page 7
MANAGEMENT’S DISCUSSION AND ANALYSIS
Page 8
Text of page 8
CITY OF SAUGATUCK MANAGEMENT’S DISCUSSION AND ANALYSIS June 30, 2024 As management of the City of Saugatuck (the “City”), we offer readers of the City’s financial statements this narrative overview and analysis of the financial activities of the City for the year ended June 30, 2024. We encourage readers to consider the information presented here in conjunction with additional information that we have furnished in the financial statements and the notes to the financial statements. FINANCIAL HIGHLIGHTS:
The City’s total net position is reported as $38,387,368 for the year ended June 30, 2024, compared to $36,867,402 for the year ended June 30, 2023.
In the City’s governmental activities, revenues generated were $5,418,590 while expenses totaled $3,906,229.
Total net position increased by $1,519,966.
OVERVIEW OF THE FINANCIAL STATEMENTS: This discussion and analysis is intended to serve as an introduction to the City’s basic financial statements. The City’s basic financial statements are comprised of three components: 1) governmentwide financial statements, 2) fund financial statements, and 3) notes to the financial statements. This report also contains required supplementary information and other supplementary information in addition to the basic financial statements themselves. Government-wide Financial Statements: The government-wide statements are designed to provide readers with a broad overview of the City’s finances, as a whole, in a manner similar to a private sector business. The statement of net position presents information on all of the City’s assets, liabilities, and deferred outflows and inflows, with the difference between these reported as net position. The statement of activities presents all of the City’s revenues and expenses, and is reported based on when the underlying event giving rise to the revenue or expense occurs, regardless of when cash is received or paid. The governmental activities of the City include general government administration, legislative, public works, street maintenance, public safety and recreation and cultural. Property taxes, state shared revenue, and charges for services finance most of these activities. Fund Financial Statements: The fund financial statements provide more detailed information about the City’s most significant funds, not the City as a whole. A fund is a grouping of related accounts that is used to maintain control over resources that have been segregated for specific activities or objectives. The City has three types of funds: Governmental Funds – Governmental funds are used to account for essentially the same functions reported as governmental activities in the government-wide financial statements. However, unlike the government-wide financial statements, governmental fund financial statements focus on near-term inflows and outflows of spendable resources, as well as on balances of spendable resources available at the end of the fiscal year. Such information may be useful in evaluating a government’s near-term financing requirements.
Page 9
Text of page 9
CITY OF SAUGATUCK MANAGEMENT’S DISCUSSION AND ANALYSIS June 30, 2024 Because the focus of governmental funds is narrower than that of the government-wide financial statements, it is useful to compare the information presented for governmental funds with similar information presented for governmental activities in the government-wide financial statements. By doing so, readers may better understand the long-term impact of the government’s near-term financing decisions. Both the governmental fund balance sheet and the governmental fund statement of revenues, expenditures, and changes in fund balances provide a reconciliation to facilitate this comparison between governmental funds and governmental activities. The City maintains five (5) individual governmental funds. Separate information is presented for the General Fund, Major Street Fund, Local Street Fund, Sewer Improvements Fund, and Debt Service Fund which are considered to be “major” funds. The City has elected to report all governmental funds as major. The City adopts an annual budget for its General Fund and special revenue funds. Budgetary comparison statements or schedules have been provided herein to demonstrate compliance with those budgets for the General Fund and all major special revenue funds. Proprietary Funds – Proprietary funds are used to report services where the City charges a fee to the customer to recover most or all of the cost of the service rendered. Proprietary funds provide both longand short-term financial information. The two types of proprietary funds are enterprise and internal service funds. The City has no enterprise funds.
Internal service funds are used to report activities that provide supplies and services to the City’s other programs. The City’s internal service fund is the Motor Pool Fund. Because these services solely benefit governmental rather than business-type functions, they have been included within governmental activities in the government-wide financial statements.
Fiduciary Funds – Fiduciary funds are used to account for the resources held for the benefit of parties outside the government. Fiduciary funds are not reflected in the government-wide financial statements because the resources of the funds are not available to support the City’s own programs. Notes to the Financial Statements: The notes provide additional information that is essential to a full understanding of the data provided in the government-wide and fund financial statements. Other Information: In addition to the basic financial statements and accompanying notes, this report also presents certain required supplementary information concerning the City. CITY OF SAUGATUCK AS A WHOLE: The City’s total net position for the year ended June 30, 2024 is $38,387,368. Unrestricted net position, that part of net position that can be used to finance day-to-day operations, is $7,557,577.
Page 10
Text of page 10
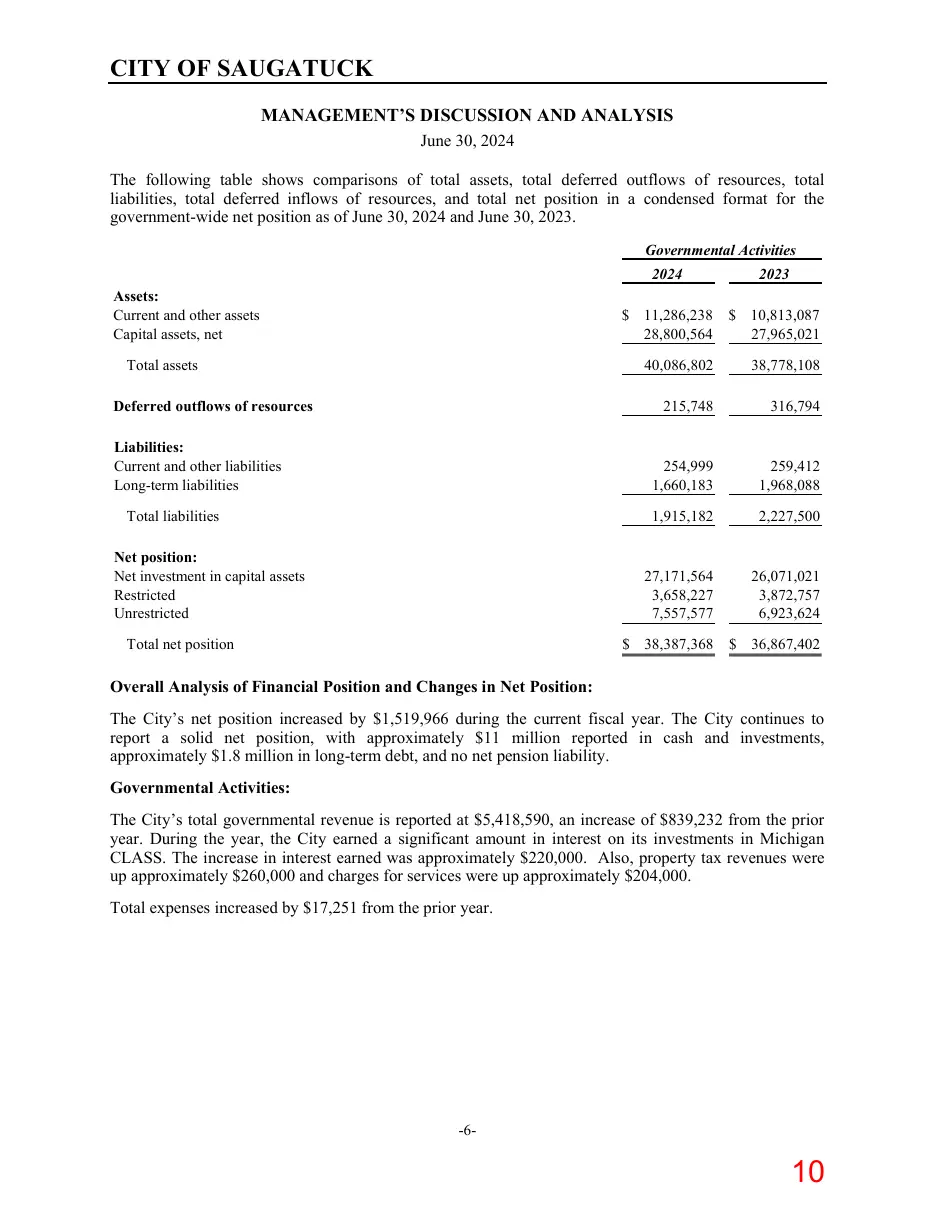
CITY OF SAUGATUCK MANAGEMENT’S DISCUSSION AND ANALYSIS June 30, 2024 The following table shows comparisons of total assets, total deferred outflows of resources, total liabilities, total deferred inflows of resources, and total net position in a condensed format for the government-wide net position as of June 30, 2024 and June 30, 2023. Governmental Activities Assets: Current and other assets Capital assets, net Total assets
Deferred outflows of resources Liabilities: Current and other liabilities Long-term liabilities Total liabilities Net position: Net investment in capital assets Restricted Unrestricted Total net position
2024
2023
$ 11,286,238 28,800,564
$ 10,813,087 27,965,021
40,086,802
38,778,108
215,748
316,794
254,999 1,660,183
259,412 1,968,088
1,915,182
2,227,500
27,171,564 3,658,227 7,557,577
26,071,021 3,872,757 6,923,624
$ 38,387,368
$ 36,867,402
Overall Analysis of Financial Position and Changes in Net Position: The City’s net position increased by $1,519,966 during the current fiscal year. The City continues to report a solid net position, with approximately $11 million reported in cash and investments, approximately $1.8 million in long-term debt, and no net pension liability. Governmental Activities: The City’s total governmental revenue is reported at $5,418,590, an increase of $839,232 from the prior year. During the year, the City earned a significant amount in interest on its investments in Michigan CLASS. The increase in interest earned was approximately $220,000. Also, property tax revenues were up approximately $260,000 and charges for services were up approximately $204,000. Total expenses increased by $17,251 from the prior year.
Page 11
Text of page 11
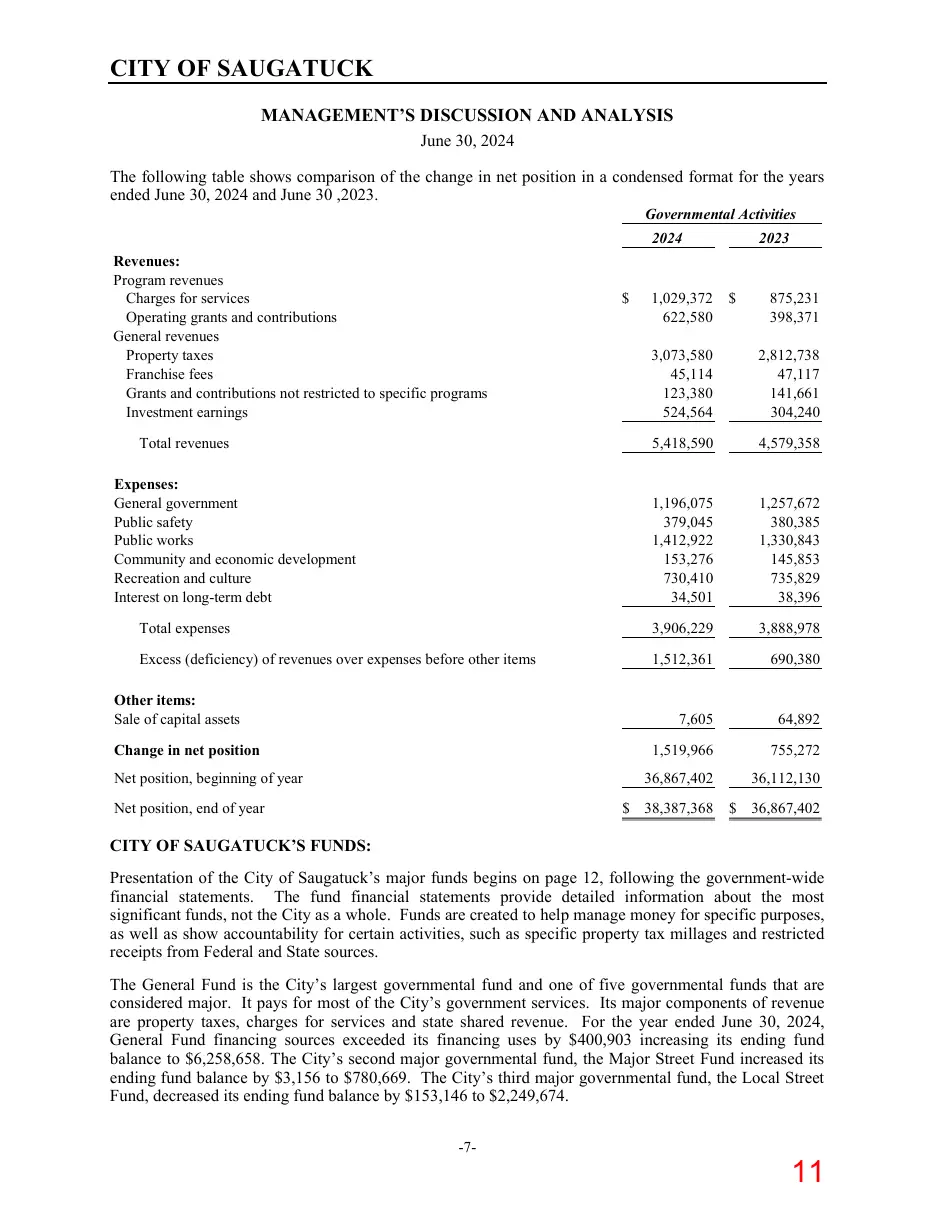
CITY OF SAUGATUCK MANAGEMENT’S DISCUSSION AND ANALYSIS June 30, 2024 The following table shows comparison of the change in net position in a condensed format for the years ended June 30, 2024 and June 30 ,2023. Governmental Activities 2024 Revenues: Program revenues Charges for services Operating grants and contributions General revenues Property taxes Franchise fees Grants and contributions not restricted to specific programs Investment earnings
1,029,372 622,580
2023
875,231 398,371
3,073,580 45,114 123,380 524,564
2,812,738 47,117 141,661 304,240
5,418,590
4,579,358
1,196,075 379,045 1,412,922 153,276 730,410 34,501
1,257,672 380,385 1,330,843 145,853 735,829 38,396
Total expenses
3,906,229
3,888,978
Excess (deficiency) of revenues over expenses before other items
1,512,361
690,380
7,605
64,892
Change in net position
1,519,966
755,272
Net position, beginning of year
36,867,402
36,112,130
$ 38,387,368
$ 36,867,402
Total revenues Expenses: General government Public safety Public works Community and economic development Recreation and culture Interest on long-term debt
Other items: Sale of capital assets
Net position, end of year
CITY OF SAUGATUCK’S FUNDS: Presentation of the City of Saugatuck’s major funds begins on page 12, following the government-wide financial statements. The fund financial statements provide detailed information about the most significant funds, not the City as a whole. Funds are created to help manage money for specific purposes, as well as show accountability for certain activities, such as specific property tax millages and restricted receipts from Federal and State sources. The General Fund is the City’s largest governmental fund and one of five governmental funds that are considered major. It pays for most of the City’s government services. Its major components of revenue are property taxes, charges for services and state shared revenue. For the year ended June 30, 2024, General Fund financing sources exceeded its financing uses by $400,903 increasing its ending fund balance to $6,258,658. The City’s second major governmental fund, the Major Street Fund increased its ending fund balance by $3,156 to $780,669. The City’s third major governmental fund, the Local Street Fund, decreased its ending fund balance by $153,146 to $2,249,674. -7-
Page 12
Text of page 12
CITY OF SAUGATUCK MANAGEMENT’S DISCUSSION AND ANALYSIS June 30, 2024 The City’s fourth major governmental fund, the Sewer Improvements Fund, increased its ending fund balance by $52,893 to $574,514. The City’s fifth major governmental fund, the Debt Service Fund, decreased its ending fund balance by $3,766 to $53,370. Overall Analysis of Financial Position and Change in General Fund Fund Balance: The General Fund fund balance of $6,258,658 as of June 30, 2024 is considered, by management, to be very healthy in comparison to the annual General Fund expenditures budget of approximately $4 million. The City’s revenues and expenditures were monitored during the current year through a budget process and the operating results were as expected. General Fund Budgetary Highlights: The General Fund budget, as originally adopted, projected no change in fund balance. During the year, the City made budget amendments, which projected a decrease in fund balance of $34,965. The actual results for the year yielded a net increase in fund balance of $400,903. Capital Assets and Debt Administration: At June 30, 2024, the City of Saugatuck had $28,800,564 invested in capital assets including land, buildings, equipment, land improvements, and infrastructure, net of accumulated depreciation. At June 30, 2023, this total was $27,965,021. Additional information about the City’s capital assets is presented in Note 1 and Note 5 of the Notes to the Financial Statements. At June 30, 2024, the City of Saugatuck’s total long-term indebtedness (not including compensated absences or net pension liability) was $1,629,000 which was backed by the full faith and credit of the City. Additional information about the City’s indebtedness is presented in Note 6 of the Notes to the Financial Statements. Economic Factors and Next Year’s Budget: The City Administration and Council worked to enhance revenues and manage expenditures to sustain valued services. Recent actions include increasing Oval Beach fees to fund beach operations and improvements. Budget line items are regularly reviewed for opportunities to reduce costs and make necessary adjustments. In 2025, the City has sufficient revenues to provide essential services and maintain streets and parks while carefully monitoring costs to preserve financial stability. The Department of Public Works and the Parks and Public Works Committee have recommended, and Council approved, several capital improvement projects for next year. The replacement of the bathrooms and upper platform at Mt. Baldhead Park may reduce the committed park fund balance from the previous Council directive. The installation of a traffic signal at Lake and Blue Star for the Blue Star Trail, repaving certain streets, and planning for the Maple Street Project (new water main, road replacement, installation of sidewalks, and stormwater improvements) will use a combination of road, water/sewer, and general fund revenues and possibly some fund balance for the projects. The City continues to have a fully funded status for the MERS defined benefit pension plan, satisfying the State of Michigan directive. The Council and Administration is committed to continuing its focus on maintaining a fully funded employee defined benefit pension plan. Contacting the City’s Financial Management: This financial report is designed to provide a general overview of the City’s finances for all those with an interest in the government’s finances. If you have questions about this report or need additional financial information, contact the City Treasurer, 102 Butler Street, P.O. Box 86, Saugatuck, Michigan 49453.
Page 13
Text of page 13
BASIC FINANCIAL STATEMENTS
Page 14
Text of page 14
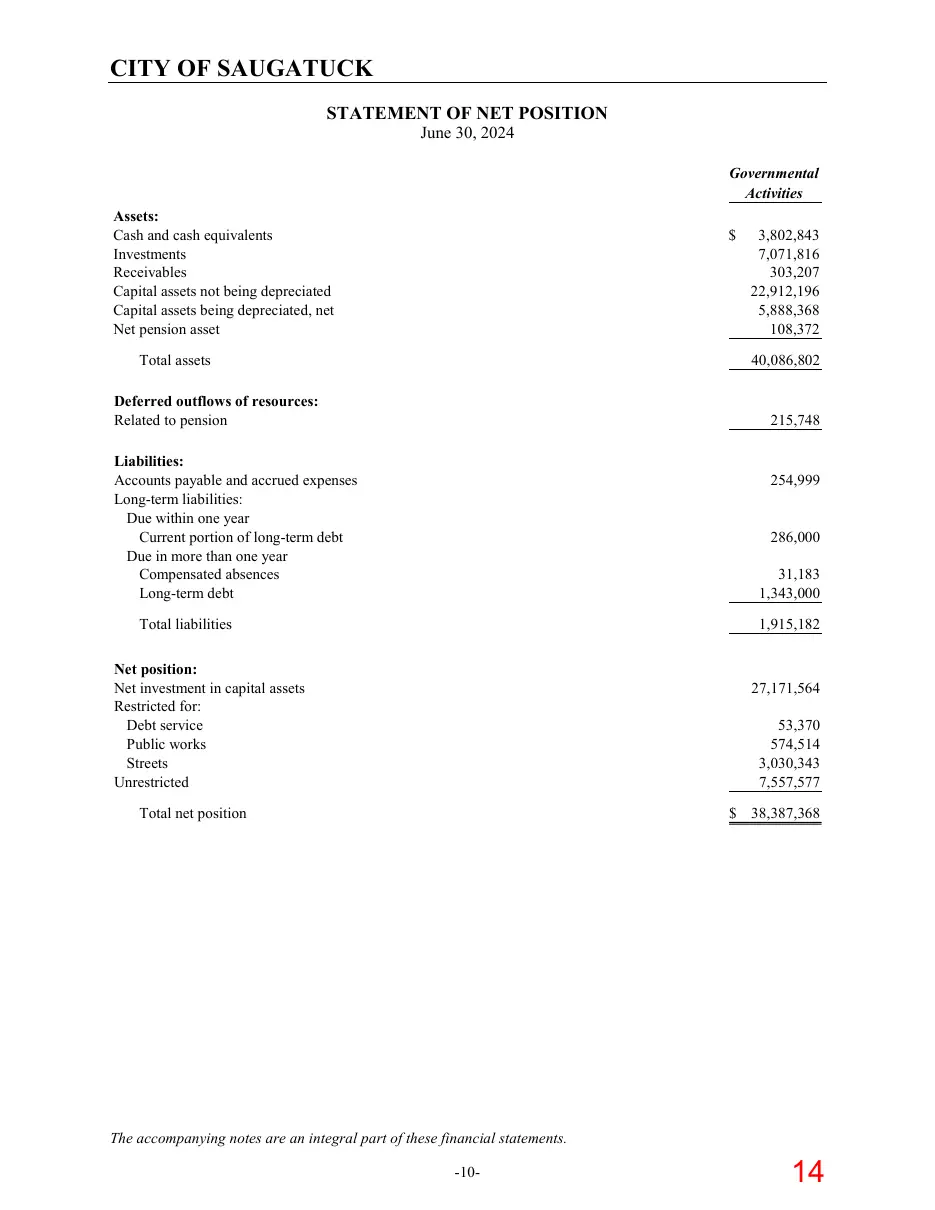
CITY OF SAUGATUCK STATEMENT OF NET POSITION June 30, 2024 Governmental Activities Assets: Cash and cash equivalents Investments Receivables Capital assets not being depreciated Capital assets being depreciated, net Net pension asset
Total assets
3,802,843 7,071,816 303,207 22,912,196 5,888,368 108,372 40,086,802
Deferred outflows of resources: Related to pension
215,748
Liabilities: Accounts payable and accrued expenses Long-term liabilities: Due within one year Current portion of long-term debt Due in more than one year Compensated absences Long-term debt
254,999
286,000 31,183 1,343,000
Total liabilities
1,915,182
Net position: Net investment in capital assets Restricted for: Debt service Public works Streets Unrestricted
27,171,564 53,370 574,514 3,030,343 7,557,577
Total net position
$ 38,387,368
The accompanying notes are an integral part of these financial statements. -10-
Page 15
Text of page 15
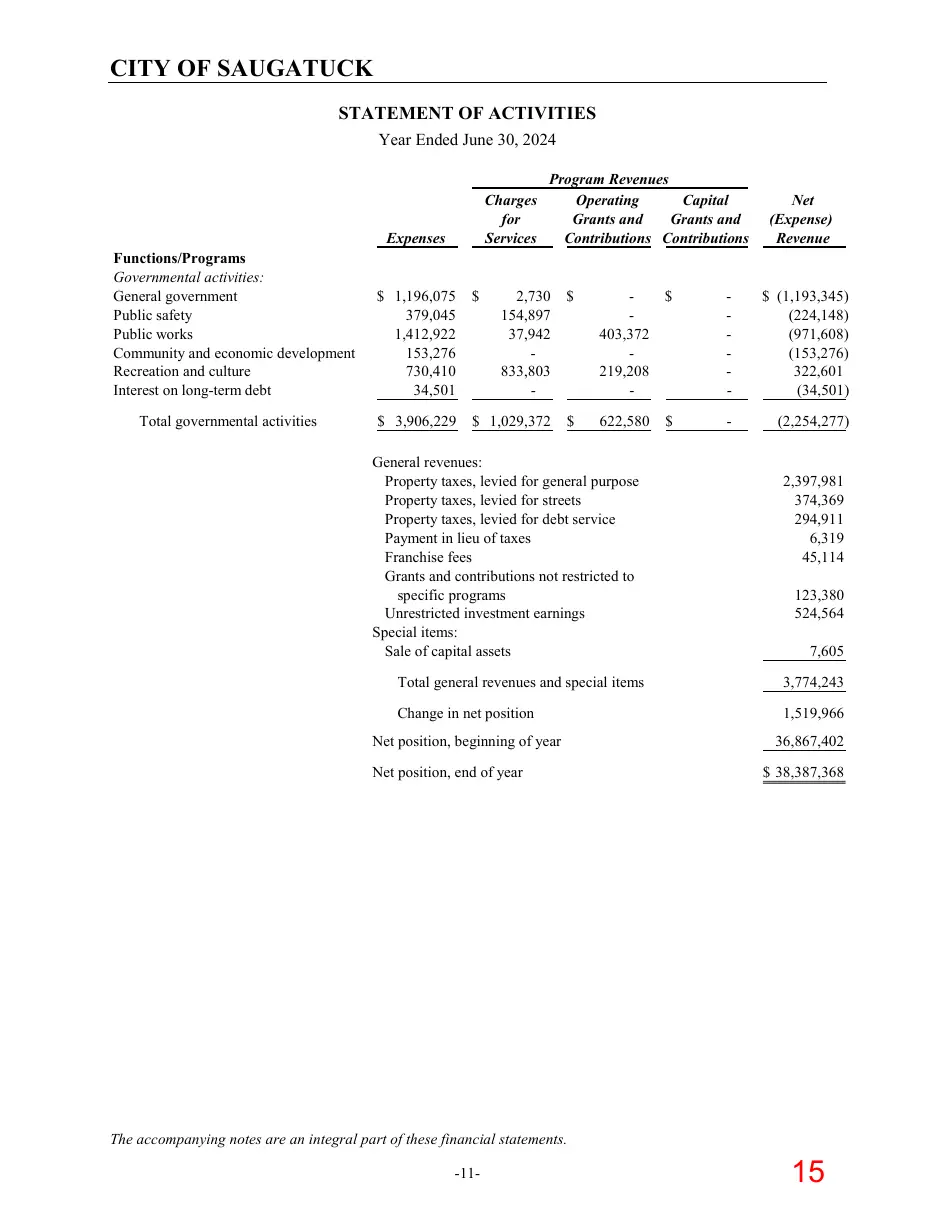
CITY OF SAUGATUCK STATEMENT OF ACTIVITIES Year Ended June 30, 2024
Charges for Services
Expenses
Program Revenues Operating Capital Grants and Grants and Contributions Contributions
Net (Expense) Revenue
Functions/Programs Governmental activities: General government Public safety Public works Community and economic development Recreation and culture Interest on long-term debt
$ 1,196,075 379,045 1,412,922 153,276 730,410 34,501
2,730 154,897 37,942 833,803 -
403,372 219,208 -
$ (1,193,345) (224,148) (971,608) (153,276) 322,601 (34,501)
Total governmental activities
$ 3,906,229
$ 1,029,372
622,580
(2,254,277)
General revenues: Property taxes, levied for general purpose Property taxes, levied for streets Property taxes, levied for debt service Payment in lieu of taxes Franchise fees Grants and contributions not restricted to specific programs Unrestricted investment earnings Special items: Sale of capital assets
2,397,981 374,369 294,911 6,319 45,114 123,380 524,564 7,605
Total general revenues and special items
3,774,243
Change in net position
1,519,966
Net position, beginning of year
36,867,402
Net position, end of year
$ 38,387,368
The accompanying notes are an integral part of these financial statements. -11-
Page 16
Text of page 16
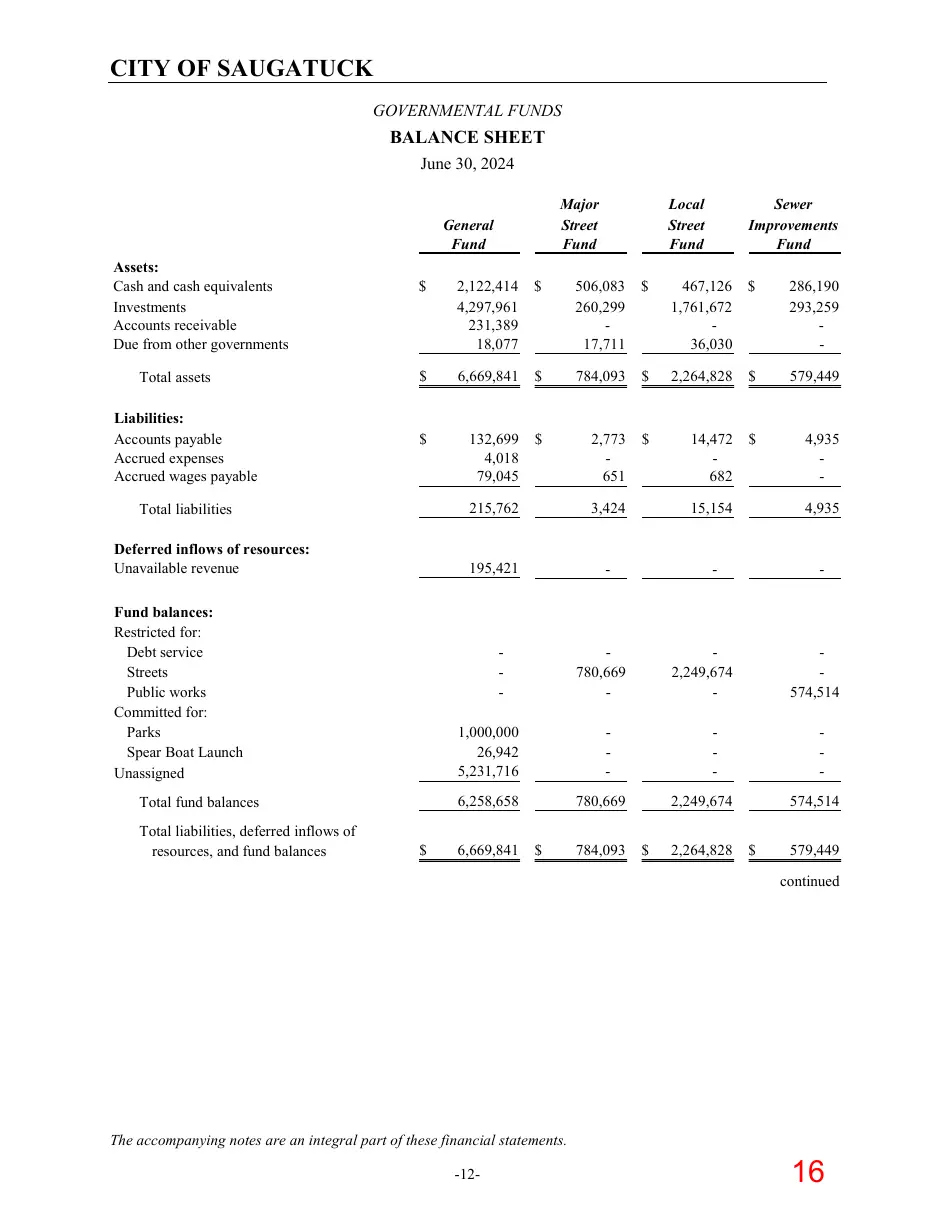
CITY OF SAUGATUCK GOVERNMENTAL FUNDS
BALANCE SHEET June 30, 2024 Major Street Fund
General Fund Assets: Cash and cash equivalents Investments Accounts receivable Due from other governments Total assets Liabilities: Accounts payable Accrued expenses Accrued wages payable
Sewer Improvements Fund
2,122,414 4,297,961 231,389 18,077
506,083 260,299 17,711
467,126 $ 1,761,672 36,030
286,190 293,259 -
6,669,841
784,093
2,264,828
579,449
132,699 4,018 79,045
2,773 651
14,472 682
4,935 -
Total liabilities Deferred inflows of resources: Unavailable revenue Fund balances: Restricted for: Debt service Streets Public works Committed for: Parks Spear Boat Launch Unassigned Total fund balances Total liabilities, deferred inflows of resources, and fund balances
Local Street Fund
215,762
3,424
15,154
4,935
195,421
780,669 -
1,000,000 26,942 5,231,716
6,258,658
780,669
6,669,841
784,093
2,249,674 -
574,514
2,249,674 $
2,264,828
574,514 $
579,449 continued
The accompanying notes are an integral part of these financial statements. -12-
Page 17
Text of page 17
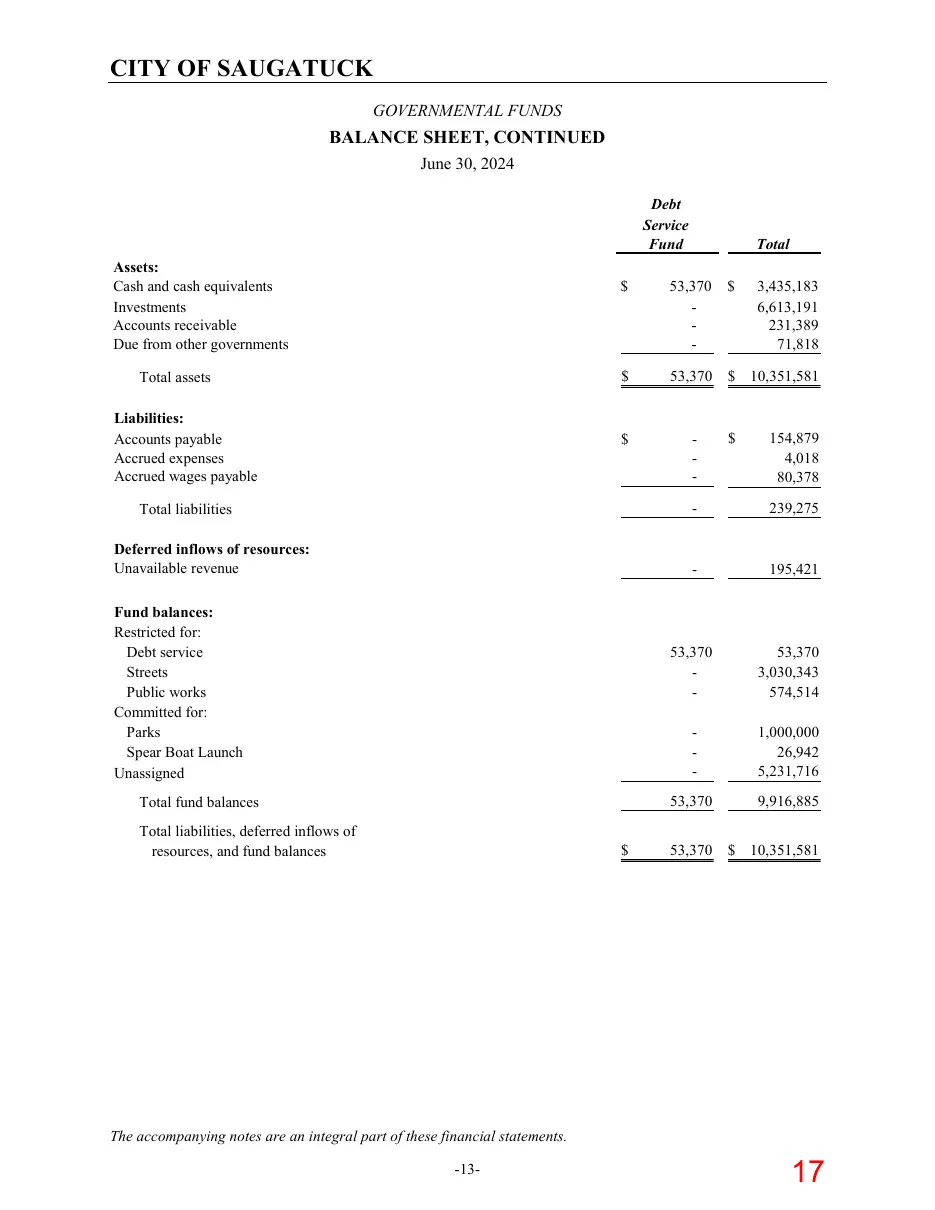
CITY OF SAUGATUCK GOVERNMENTAL FUNDS
BALANCE SHEET, CONTINUED June 30, 2024 Debt Service Fund Assets: Cash and cash equivalents Investments Accounts receivable Due from other governments Total assets Liabilities: Accounts payable Accrued expenses Accrued wages payable
53,370 -
53,370
$ 10,351,581
Total liabilities Deferred inflows of resources: Unavailable revenue Fund balances: Restricted for: Debt service Streets Public works Committed for: Parks Spear Boat Launch Unassigned Total fund balances Total liabilities, deferred inflows of resources, and fund balances
Total
3,435,183 6,613,191 231,389 71,818
154,879 4,018 80,378
239,275
195,421
53,370 -
53,370 3,030,343 574,514
1,000,000 26,942 5,231,716
53,370
9,916,885
53,370
$ 10,351,581
The accompanying notes are an integral part of these financial statements. -13-
Page 18
Text of page 18
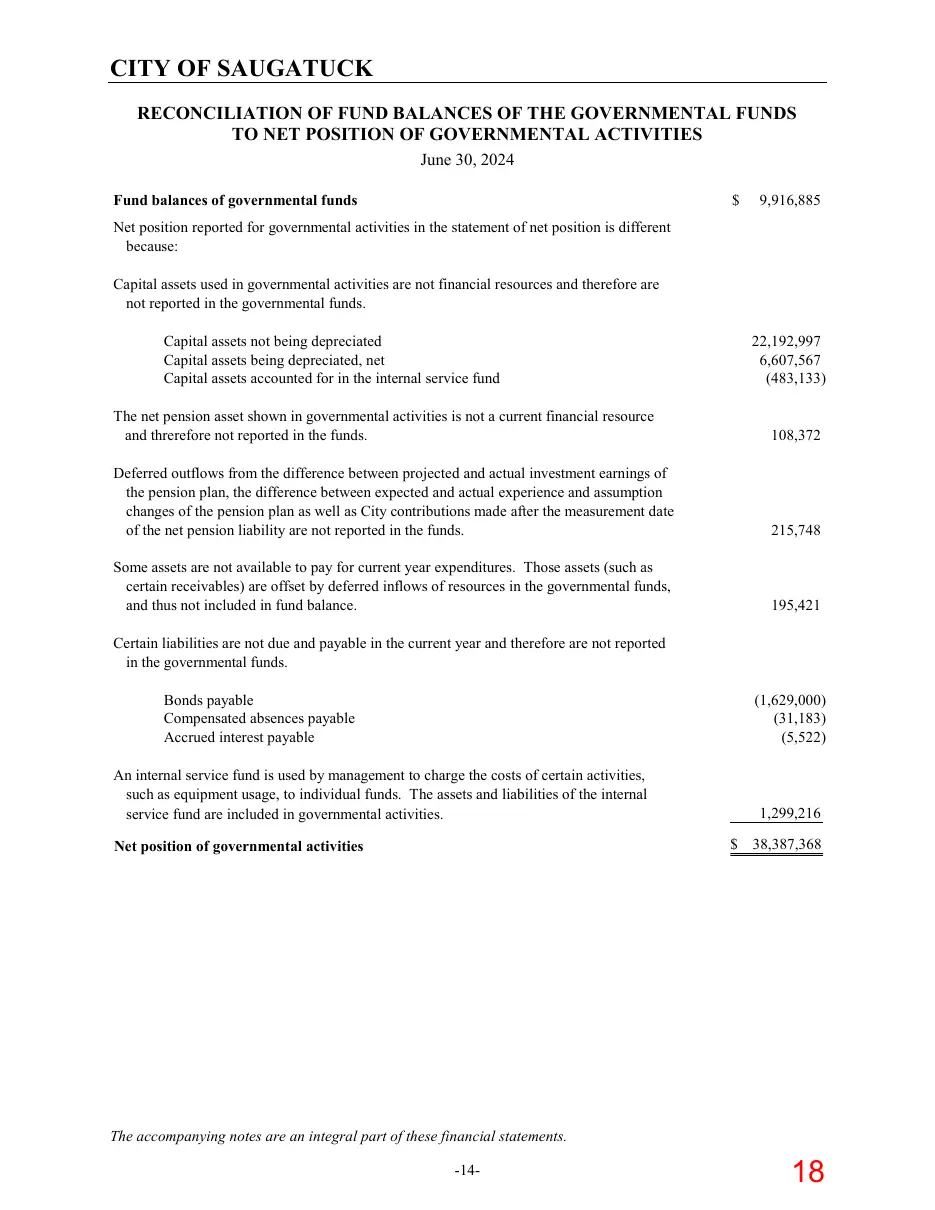
CITY OF SAUGATUCK RECONCILIATION OF FUND BALANCES OF THE GOVERNMENTAL FUNDS TO NET POSITION OF GOVERNMENTAL ACTIVITIES June 30, 2024 $
Fund balances of governmental funds
9,916,885
Net position reported for governmental activities in the statement of net position is different because: Capital assets used in governmental activities are not financial resources and therefore are not reported in the governmental funds. Capital assets not being depreciated Capital assets being depreciated, net Capital assets accounted for in the internal service fund
22,192,997 6,607,567 (483,133)
The net pension asset shown in governmental activities is not a current financial resource and threrefore not reported in the funds.
108,372
Deferred outflows from the difference between projected and actual investment earnings of the pension plan, the difference between expected and actual experience and assumption changes of the pension plan as well as City contributions made after the measurement date of the net pension liability are not reported in the funds.
215,748
Some assets are not available to pay for current year expenditures. Those assets (such as certain receivables) are offset by deferred inflows of resources in the governmental funds, and thus not included in fund balance.
195,421
Certain liabilities are not due and payable in the current year and therefore are not reported in the governmental funds. Bonds payable Compensated absences payable Accrued interest payable
(1,629,000) (31,183) (5,522)
An internal service fund is used by management to charge the costs of certain activities, such as equipment usage, to individual funds. The assets and liabilities of the internal service fund are included in governmental activities.
1,299,216 $ 38,387,368
Net position of governmental activities
The accompanying notes are an integral part of these financial statements. -14-
Page 19
Text of page 19
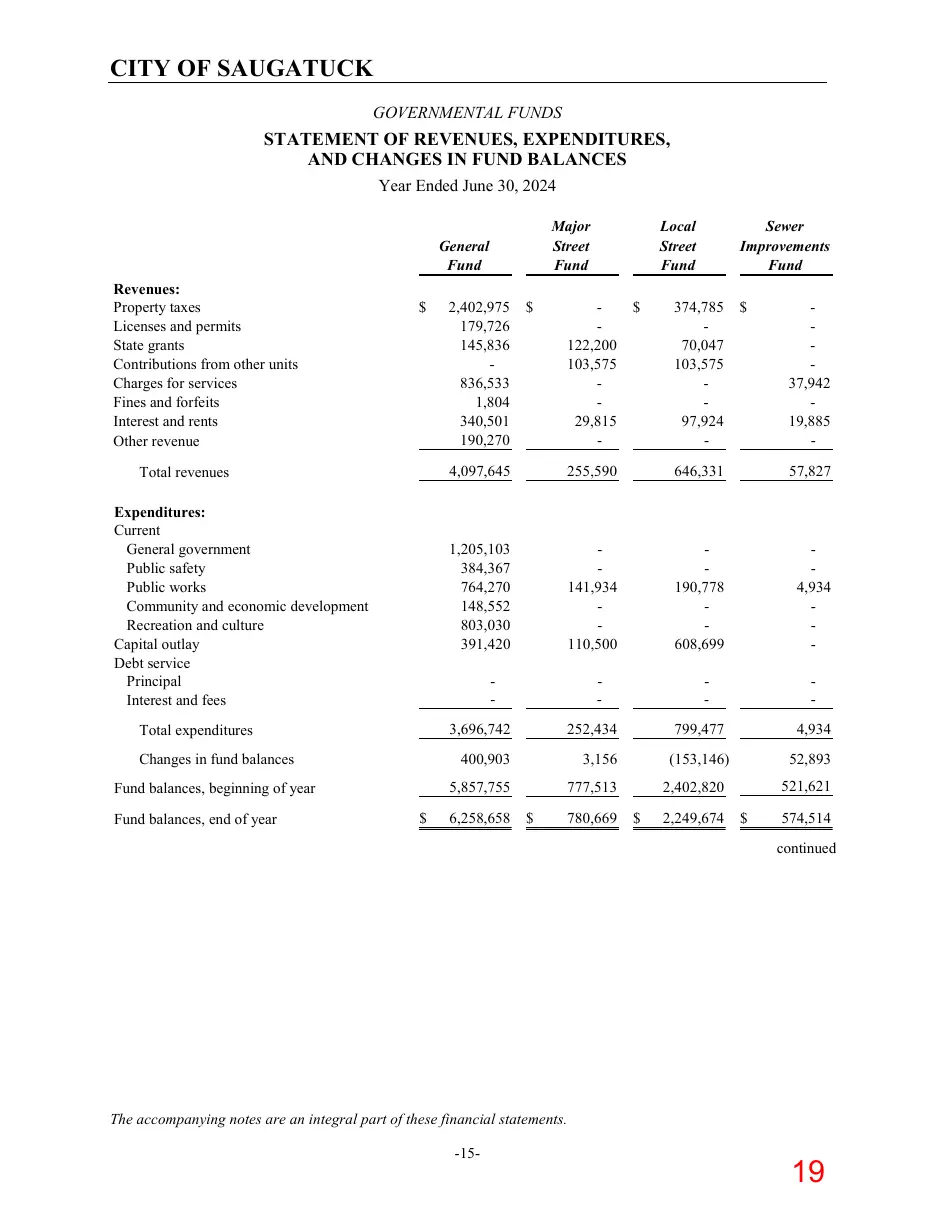
CITY OF SAUGATUCK GOVERNMENTAL FUNDS
STATEMENT OF REVENUES, EXPENDITURES, AND CHANGES IN FUND BALANCES Year Ended June 30, 2024 Major Street Fund
General Fund Revenues: Property taxes Licenses and permits State grants Contributions from other units Charges for services Fines and forfeits Interest and rents Other revenue
2,402,975 179,726 145,836 836,533 1,804 340,501 190,270
Local Street Fund
122,200 103,575 29,815 -
Sewer Improvements Fund
374,785 70,047 103,575 97,924 -
37,942 19,885 -
4,097,645
255,590
646,331
57,827
1,205,103 384,367 764,270 148,552 803,030 391,420
141,934 110,500
190,778 608,699
4,934 -
3,696,742
252,434
799,477
4,934
Changes in fund balances
400,903
3,156
(153,146)
52,893
Fund balances, beginning of year
5,857,755
777,513
2,402,820
521,621
Total revenues Expenditures: Current General government Public safety Public works Community and economic development Recreation and culture Capital outlay Debt service Principal Interest and fees
Total expenditures
Fund balances, end of year
6,258,658
780,669
2,249,674
574,514 continued
The accompanying notes are an integral part of these financial statements. -15-
Page 20
Text of page 20
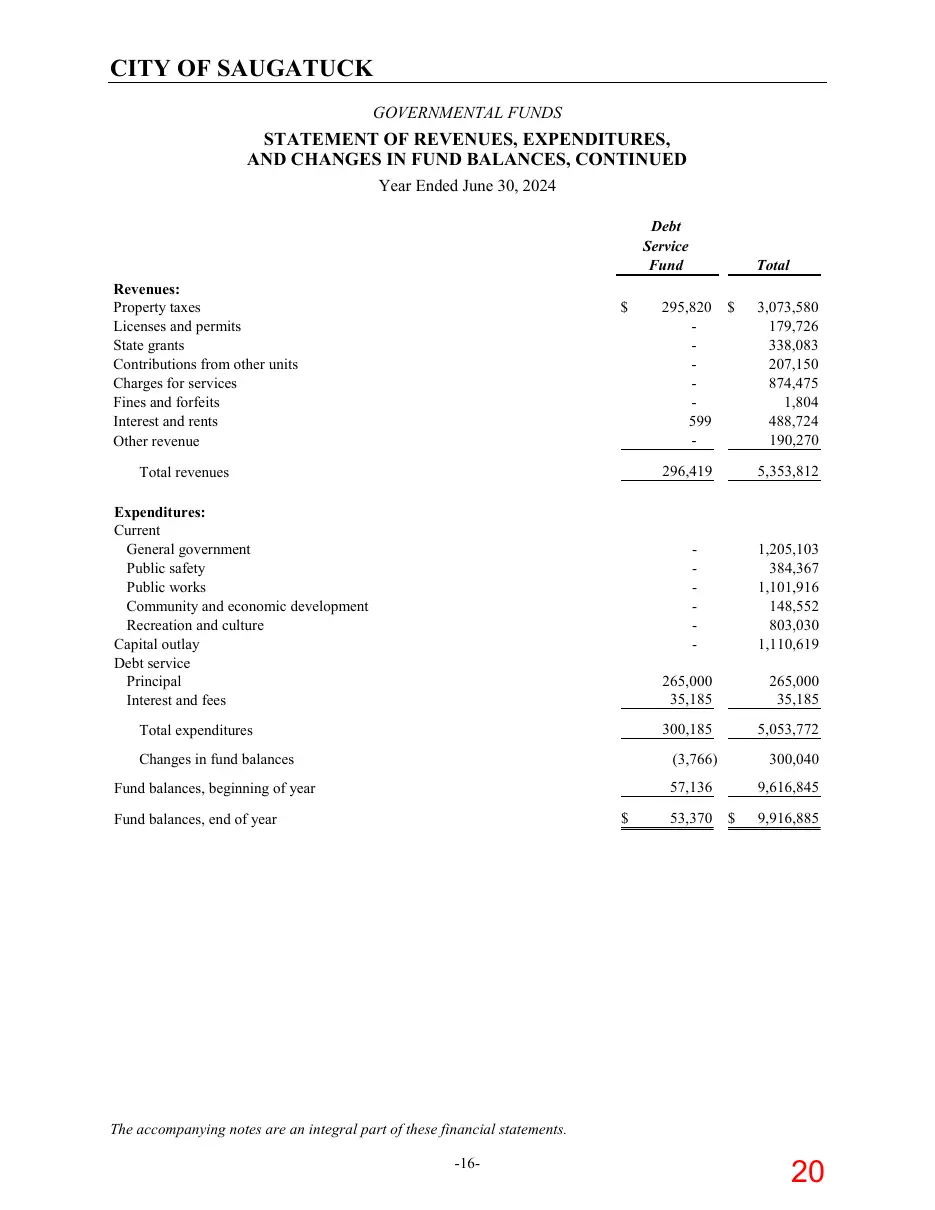
CITY OF SAUGATUCK GOVERNMENTAL FUNDS
STATEMENT OF REVENUES, EXPENDITURES, AND CHANGES IN FUND BALANCES, CONTINUED Year Ended June 30, 2024 Debt Service Fund Revenues: Property taxes Licenses and permits State grants Contributions from other units Charges for services Fines and forfeits Interest and rents Other revenue
Total
295,820 599 -
3,073,580 179,726 338,083 207,150 874,475 1,804 488,724 190,270
296,419
5,353,812
1,205,103 384,367 1,101,916 148,552 803,030 1,110,619
265,000 35,185
265,000 35,185
Total expenditures
300,185
5,053,772
Changes in fund balances
(3,766)
300,040
Fund balances, beginning of year
57,136
9,616,845
Total revenues Expenditures: Current General government Public safety Public works Community and economic development Recreation and culture Capital outlay Debt service Principal Interest and fees
Fund balances, end of year
53,370
9,916,885
The accompanying notes are an integral part of these financial statements. -16-
Page 21
Text of page 21
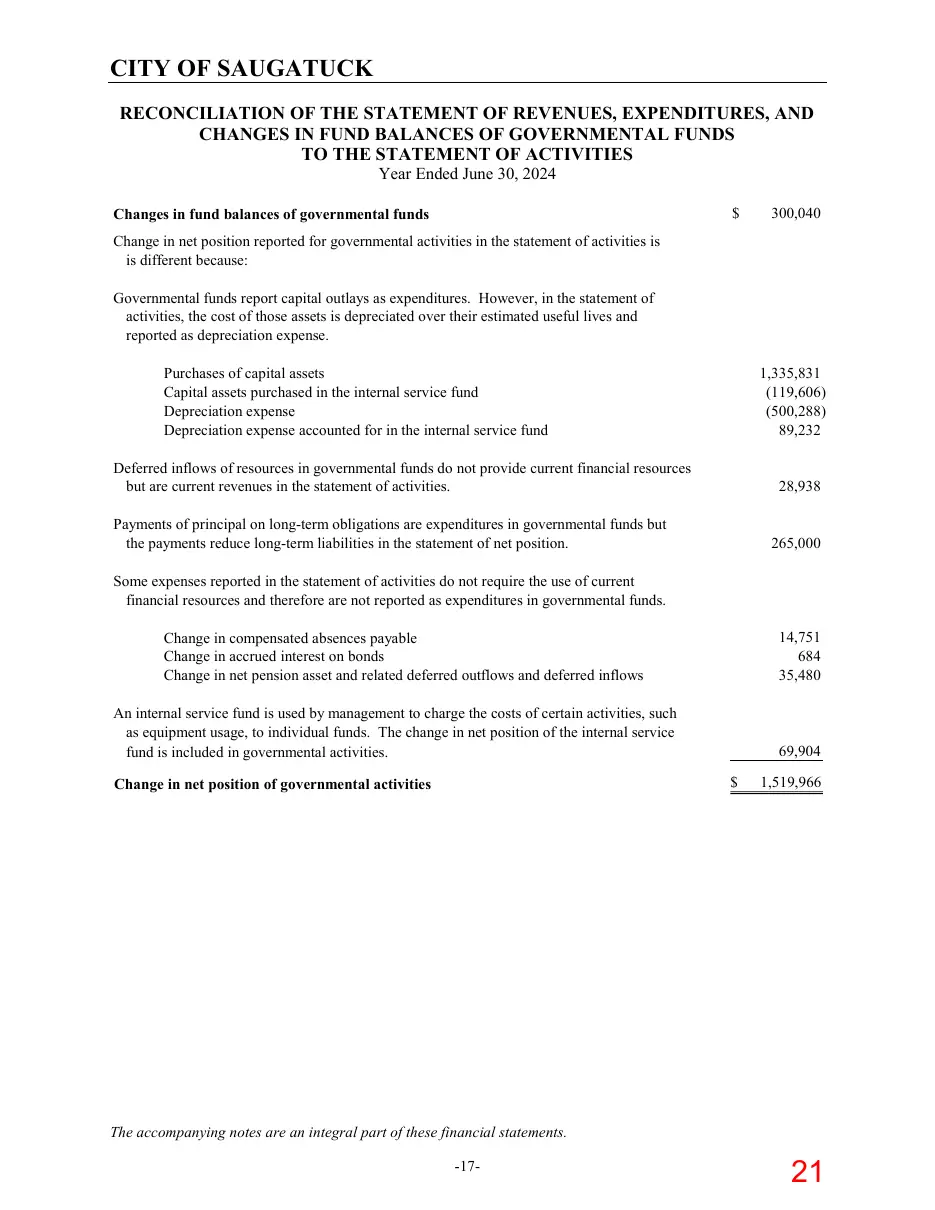
CITY OF SAUGATUCK RECONCILIATION OF THE STATEMENT OF REVENUES, EXPENDITURES, AND CHANGES IN FUND BALANCES OF GOVERNMENTAL FUNDS TO THE STATEMENT OF ACTIVITIES Year Ended June 30, 2024
Changes in fund balances of governmental funds
300,040
Change in net position reported for governmental activities in the statement of activities is is different because: Governmental funds report capital outlays as expenditures. However, in the statement of activities, the cost of those assets is depreciated over their estimated useful lives and reported as depreciation expense. Purchases of capital assets Capital assets purchased in the internal service fund Depreciation expense Depreciation expense accounted for in the internal service fund
1,335,831 (119,606) (500,288) 89,232
Deferred inflows of resources in governmental funds do not provide current financial resources but are current revenues in the statement of activities.
28,938
Payments of principal on long-term obligations are expenditures in governmental funds but the payments reduce long-term liabilities in the statement of net position.
265,000
Some expenses reported in the statement of activities do not require the use of current financial resources and therefore are not reported as expenditures in governmental funds. Change in compensated absences payable Change in accrued interest on bonds Change in net pension asset and related deferred outflows and deferred inflows
14,751 684 35,480
An internal service fund is used by management to charge the costs of certain activities, such as equipment usage, to individual funds. The change in net position of the internal service fund is included in governmental activities.
69,904 $
Change in net position of governmental activities
1,519,966
The accompanying notes are an integral part of these financial statements. -17-
Page 22
Text of page 22
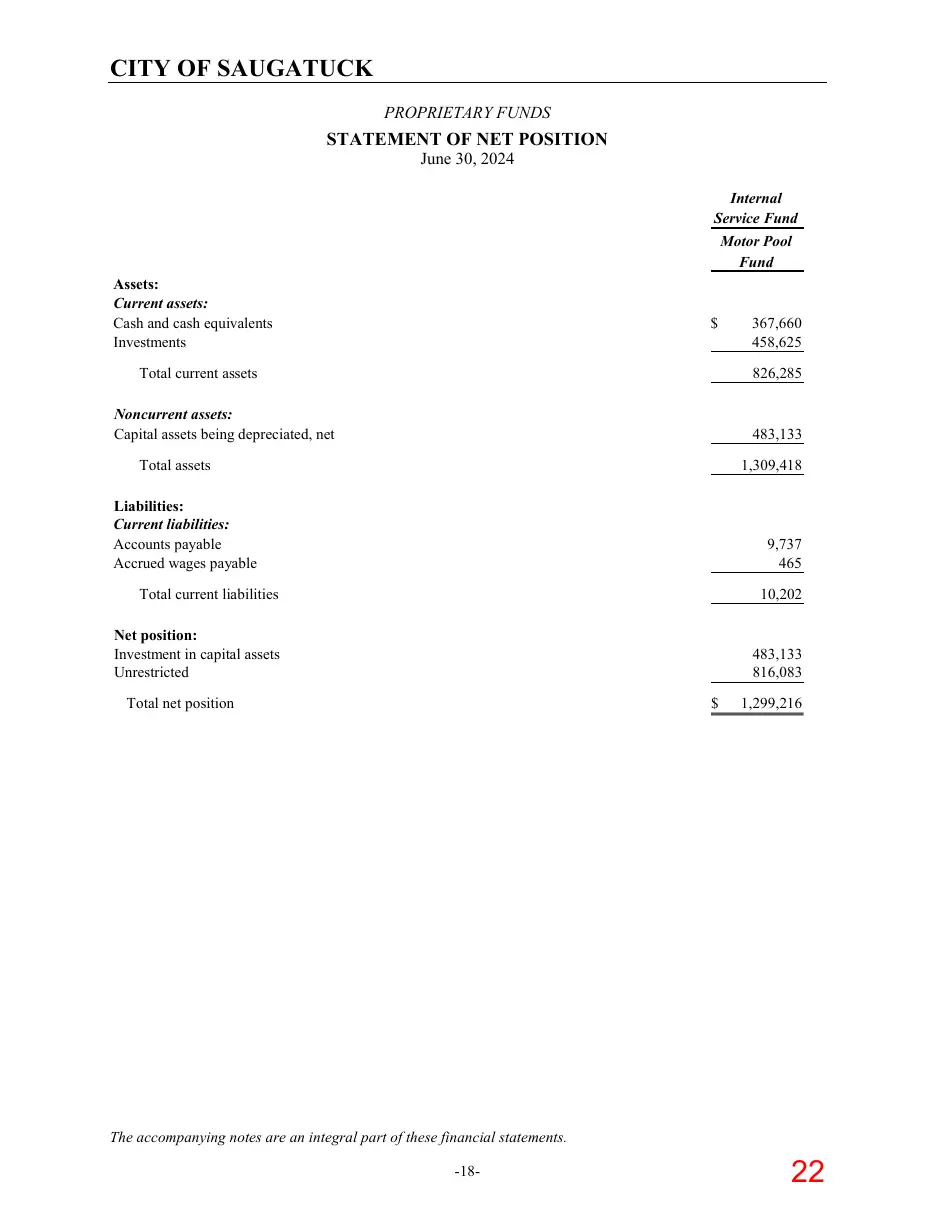
CITY OF SAUGATUCK PROPRIETARY FUNDS
STATEMENT OF NET POSITION June 30, 2024
Internal Service Fund Motor Pool Fund Assets: Current assets: Cash and cash equivalents Investments
Total current assets
367,660 458,625 826,285
Noncurrent assets: Capital assets being depreciated, net
483,133
Total assets
1,309,418
Liabilities: Current liabilities: Accounts payable Accrued wages payable
9,737 465
Total current liabilities
10,202
Net position: Investment in capital assets Unrestricted
483,133 816,083
Total net position
1,299,216
The accompanying notes are an integral part of these financial statements. -18-
Page 23
Text of page 23
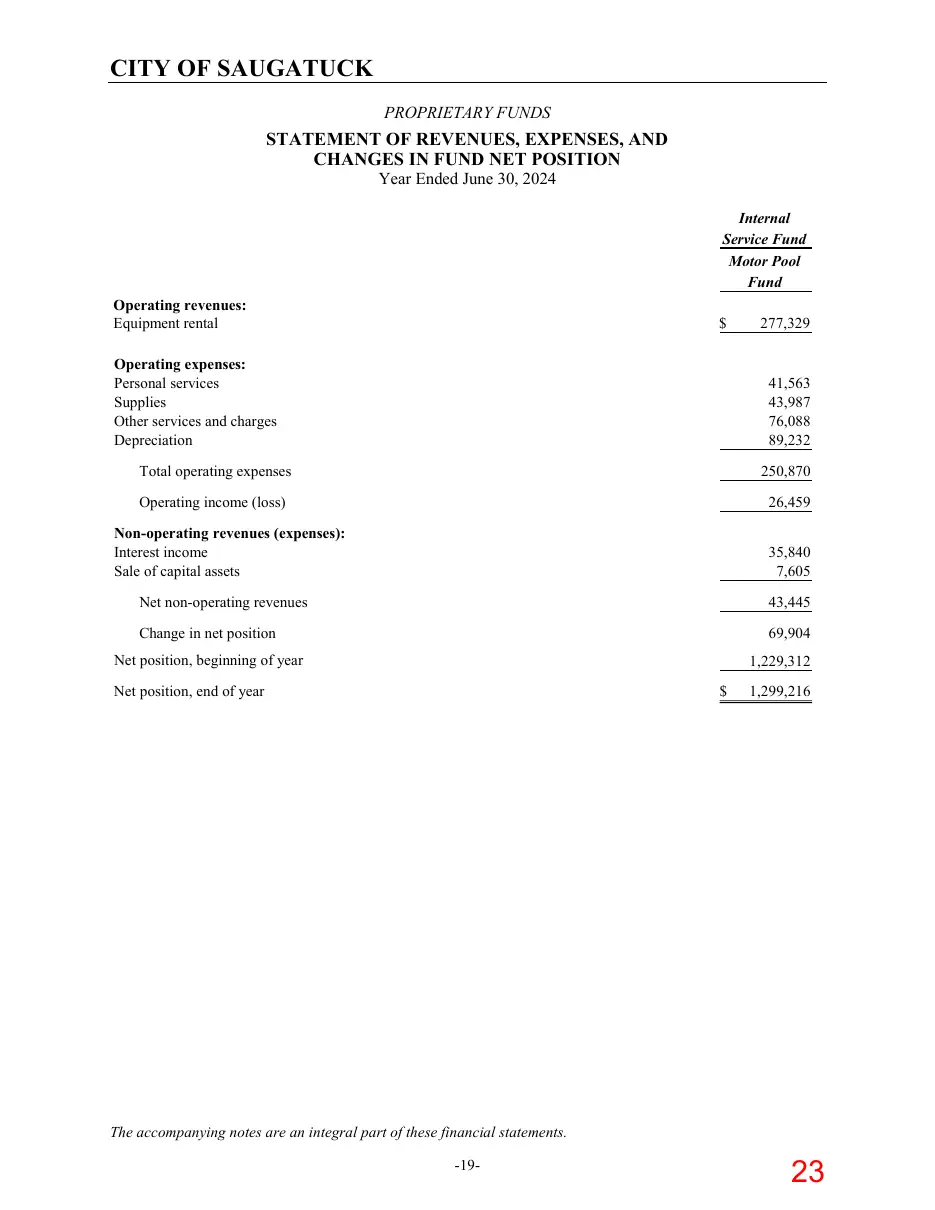
CITY OF SAUGATUCK PROPRIETARY FUNDS
STATEMENT OF REVENUES, EXPENSES, AND CHANGES IN FUND NET POSITION Year Ended June 30, 2024
Internal Service Fund Motor Pool Fund Operating revenues: Equipment rental
Operating expenses: Personal services Supplies Other services and charges Depreciation
277,329
41,563 43,987 76,088 89,232
Total operating expenses
250,870
Operating income (loss)
26,459
Non-operating revenues (expenses): Interest income Sale of capital assets
35,840 7,605
Net non-operating revenues
43,445
Change in net position
69,904
Net position, beginning of year
1,229,312
Net position, end of year
1,299,216
The accompanying notes are an integral part of these financial statements. -19-
Page 24
Text of page 24
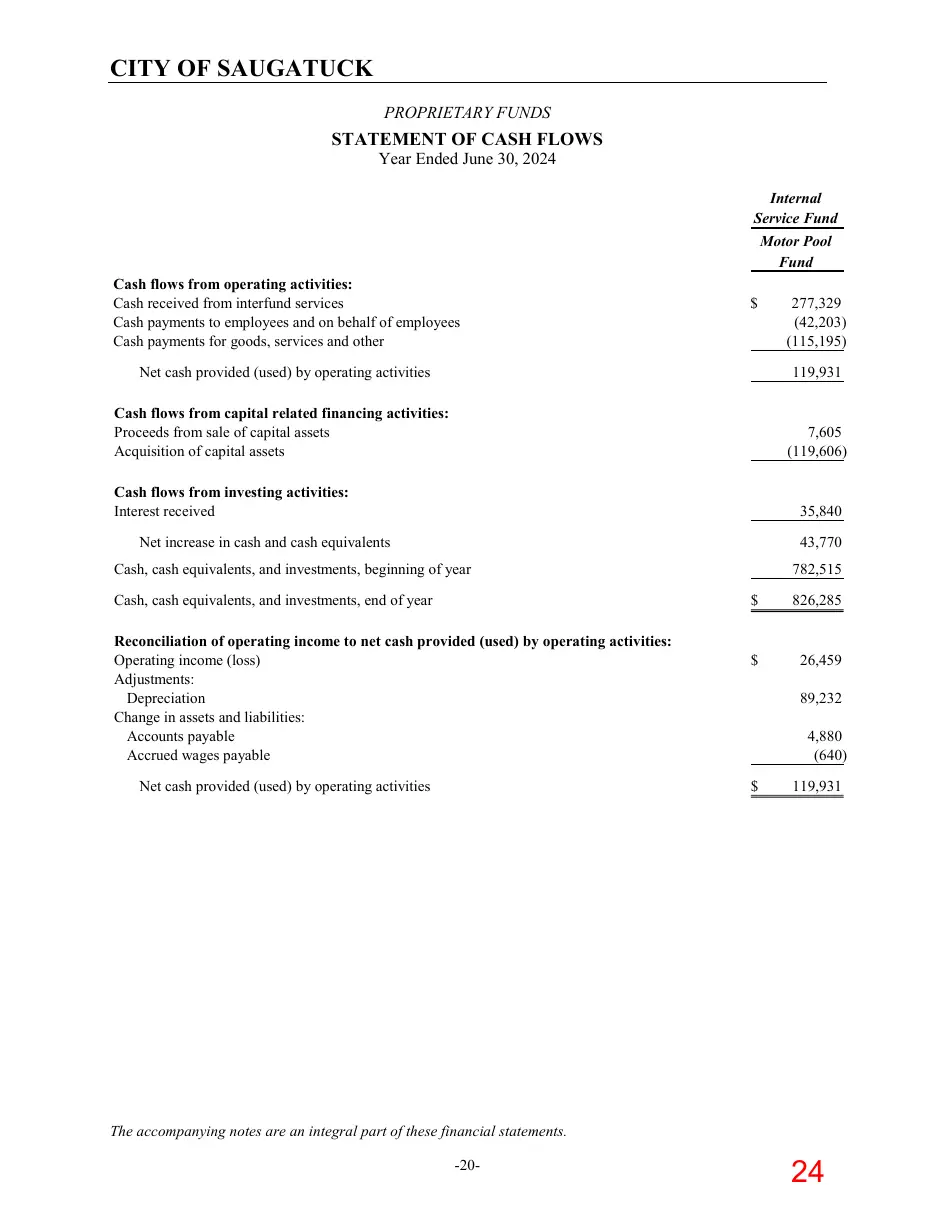
CITY OF SAUGATUCK PROPRIETARY FUNDS
STATEMENT OF CASH FLOWS Year Ended June 30, 2024
Internal Service Fund Motor Pool Fund Cash flows from operating activities: Cash received from interfund services Cash payments to employees and on behalf of employees Cash payments for goods, services and other
277,329 (42,203) (115,195)
Net cash provided (used) by operating activities
119,931
Cash flows from capital related financing activities: Proceeds from sale of capital assets Acquisition of capital assets
7,605 (119,606)
Cash flows from investing activities: Interest received
35,840
Net increase in cash and cash equivalents
43,770
Cash, cash equivalents, and investments, beginning of year Cash, cash equivalents, and investments, end of year Reconciliation of operating income to net cash provided (used) by operating activities: Operating income (loss) Adjustments: Depreciation Change in assets and liabilities: Accounts payable Accrued wages payable Net cash provided (used) by operating activities
782,515 $
826,285
26,459 89,232 4,880 (640)
119,931
The accompanying notes are an integral part of these financial statements. -20-
Page 25
Text of page 25
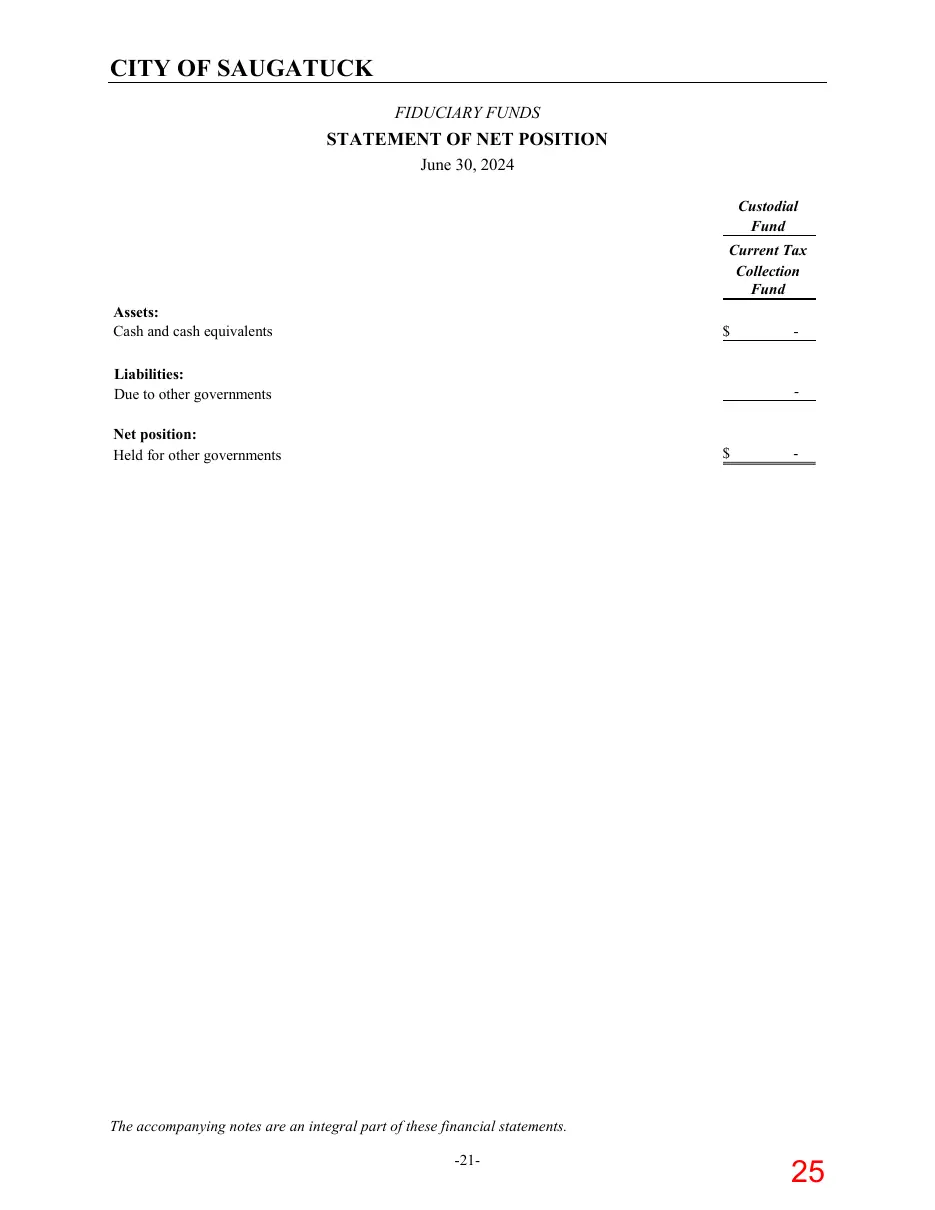
CITY OF SAUGATUCK FIDUCIARY FUNDS
STATEMENT OF NET POSITION June 30, 2024 Custodial Fund Current Tax Collection Fund Assets: Cash and cash equivalents
Liabilities: Due to other governments
Net position: Held for other governments
The accompanying notes are an integral part of these financial statements. -21-
Page 26
Text of page 26
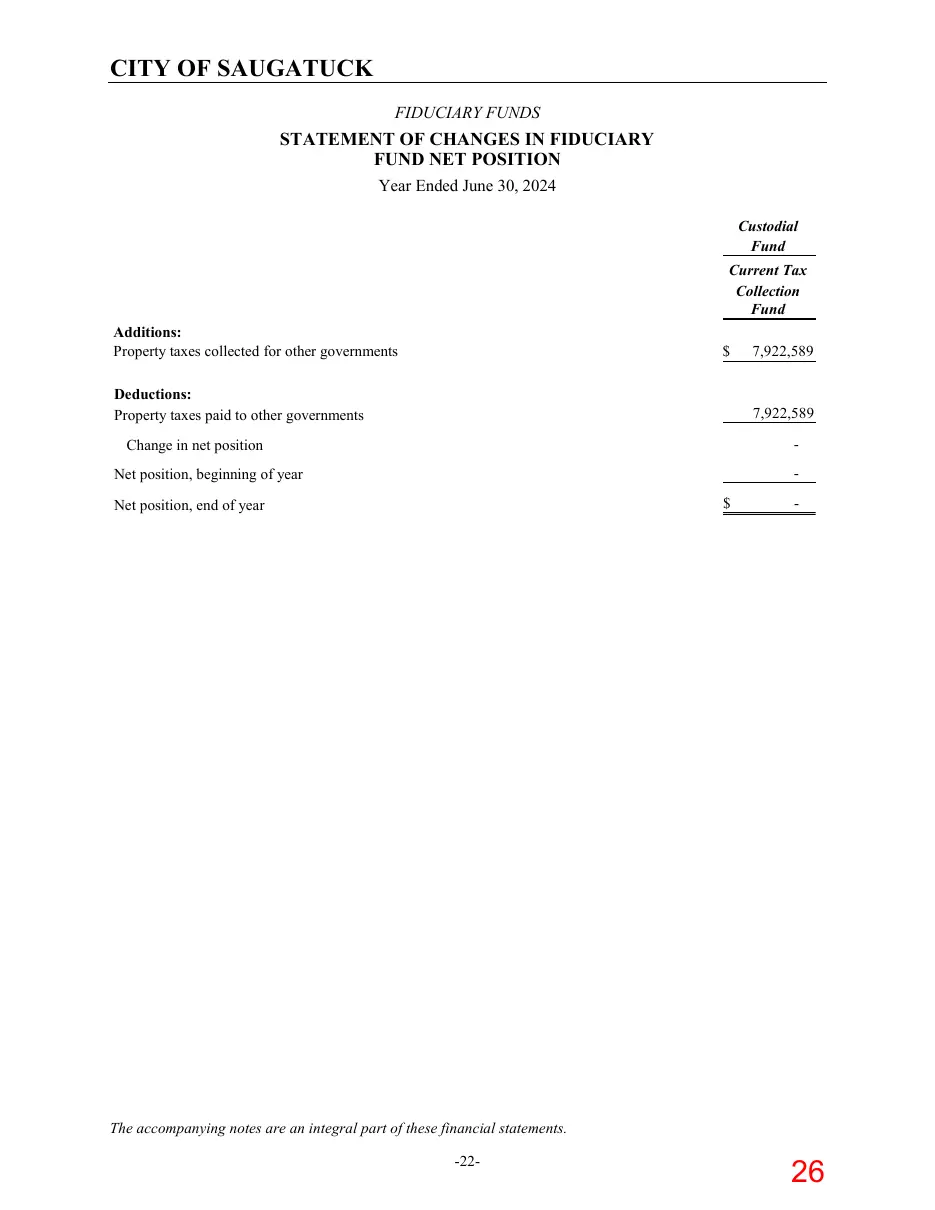
CITY OF SAUGATUCK FIDUCIARY FUNDS
STATEMENT OF CHANGES IN FIDUCIARY FUND NET POSITION Year Ended June 30, 2024 Custodial Fund Current Tax Collection Fund Additions: Property taxes collected for other governments
Deductions: Property taxes paid to other governments
7,922,589
7,922,589 -
Change in net position
Net position, beginning of year $
Net position, end of year
The accompanying notes are an integral part of these financial statements. -22-
Page 27
Text of page 27
NOTES TO FINANCIAL STATEMENTS
Page 28
Text of page 28
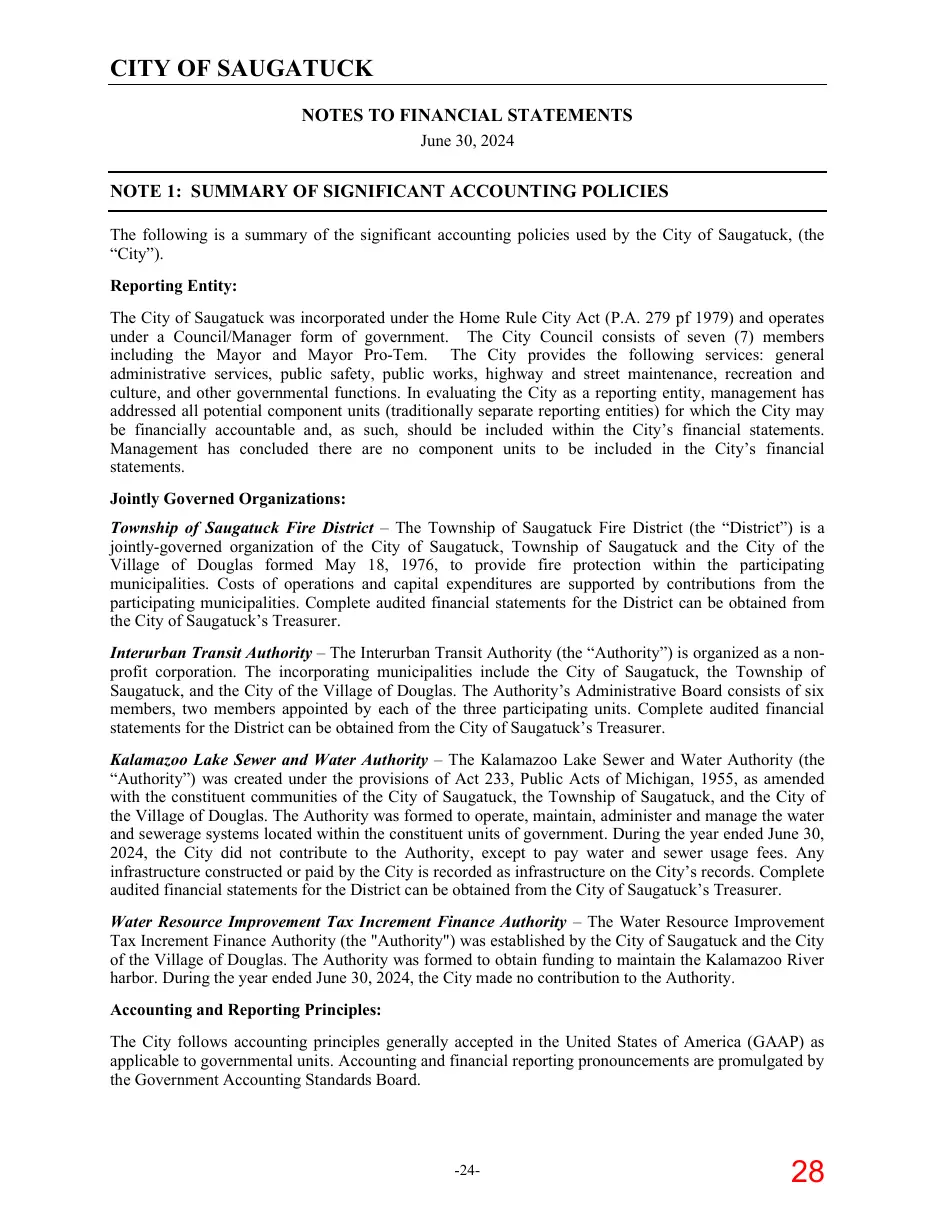
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES The following is a summary of the significant accounting policies used by the City of Saugatuck, (the “City”). Reporting Entity: The City of Saugatuck was incorporated under the Home Rule City Act (P.A. 279 pf 1979) and operates under a Council/Manager form of government. The City Council consists of seven (7) members including the Mayor and Mayor Pro-Tem. The City provides the following services: general administrative services, public safety, public works, highway and street maintenance, recreation and culture, and other governmental functions. In evaluating the City as a reporting entity, management has addressed all potential component units (traditionally separate reporting entities) for which the City may be financially accountable and, as such, should be included within the City’s financial statements. Management has concluded there are no component units to be included in the City’s financial statements. Jointly Governed Organizations: Township of Saugatuck Fire District – The Township of Saugatuck Fire District (the “District”) is a jointly-governed organization of the City of Saugatuck, Township of Saugatuck and the City of the Village of Douglas formed May 18, 1976, to provide fire protection within the participating municipalities. Costs of operations and capital expenditures are supported by contributions from the participating municipalities. Complete audited financial statements for the District can be obtained from the City of Saugatuck’s Treasurer. Interurban Transit Authority – The Interurban Transit Authority (the “Authority”) is organized as a nonprofit corporation. The incorporating municipalities include the City of Saugatuck, the Township of Saugatuck, and the City of the Village of Douglas. The Authority’s Administrative Board consists of six members, two members appointed by each of the three participating units. Complete audited financial statements for the District can be obtained from the City of Saugatuck’s Treasurer. Kalamazoo Lake Sewer and Water Authority – The Kalamazoo Lake Sewer and Water Authority (the “Authority”) was created under the provisions of Act 233, Public Acts of Michigan, 1955, as amended with the constituent communities of the City of Saugatuck, the Township of Saugatuck, and the City of the Village of Douglas. The Authority was formed to operate, maintain, administer and manage the water and sewerage systems located within the constituent units of government. During the year ended June 30, 2024, the City did not contribute to the Authority, except to pay water and sewer usage fees. Any infrastructure constructed or paid by the City is recorded as infrastructure on the City’s records. Complete audited financial statements for the District can be obtained from the City of Saugatuck’s Treasurer. Water Resource Improvement Tax Increment Finance Authority – The Water Resource Improvement Tax Increment Finance Authority (the "Authority") was established by the City of Saugatuck and the City of the Village of Douglas. The Authority was formed to obtain funding to maintain the Kalamazoo River harbor. During the year ended June 30, 2024, the City made no contribution to the Authority. Accounting and Reporting Principles: The City follows accounting principles generally accepted in the United States of America (GAAP) as applicable to governmental units. Accounting and financial reporting pronouncements are promulgated by the Government Accounting Standards Board.
-24-
Page 29
Text of page 29
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
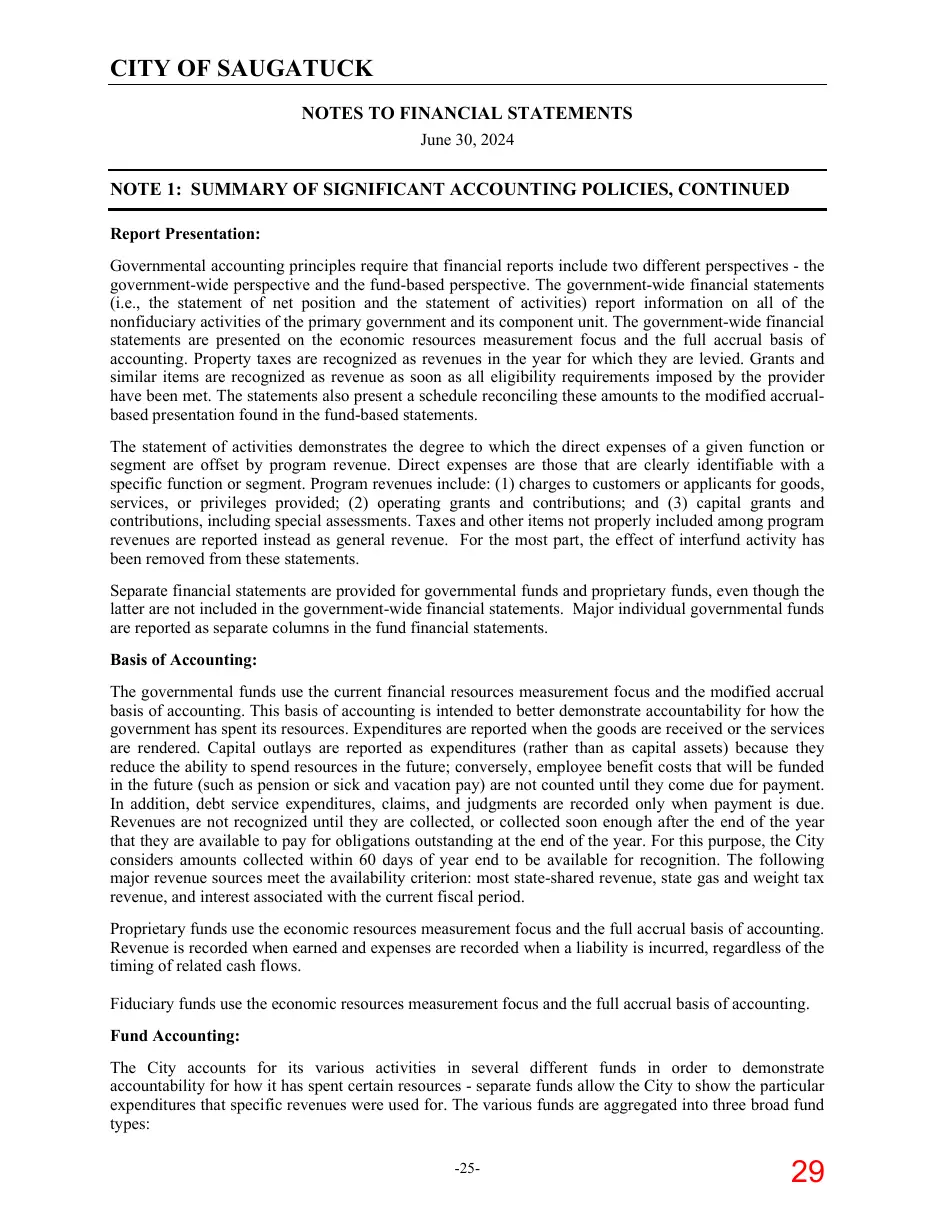
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES, CONTINUED Report Presentation: Governmental accounting principles require that financial reports include two different perspectives - the government-wide perspective and the fund-based perspective. The government-wide financial statements (i.e., the statement of net position and the statement of activities) report information on all of the nonfiduciary activities of the primary government and its component unit. The government-wide financial statements are presented on the economic resources measurement focus and the full accrual basis of accounting. Property taxes are recognized as revenues in the year for which they are levied. Grants and similar items are recognized as revenue as soon as all eligibility requirements imposed by the provider have been met. The statements also present a schedule reconciling these amounts to the modified accrualbased presentation found in the fund-based statements. The statement of activities demonstrates the degree to which the direct expenses of a given function or segment are offset by program revenue. Direct expenses are those that are clearly identifiable with a specific function or segment. Program revenues include: (1) charges to customers or applicants for goods, services, or privileges provided; (2) operating grants and contributions; and (3) capital grants and contributions, including special assessments. Taxes and other items not properly included among program revenues are reported instead as general revenue. For the most part, the effect of interfund activity has been removed from these statements. Separate financial statements are provided for governmental funds and proprietary funds, even though the latter are not included in the government-wide financial statements. Major individual governmental funds are reported as separate columns in the fund financial statements. Basis of Accounting: The governmental funds use the current financial resources measurement focus and the modified accrual basis of accounting. This basis of accounting is intended to better demonstrate accountability for how the government has spent its resources. Expenditures are reported when the goods are received or the services are rendered. Capital outlays are reported as expenditures (rather than as capital assets) because they reduce the ability to spend resources in the future; conversely, employee benefit costs that will be funded in the future (such as pension or sick and vacation pay) are not counted until they come due for payment. In addition, debt service expenditures, claims, and judgments are recorded only when payment is due. Revenues are not recognized until they are collected, or collected soon enough after the end of the year that they are available to pay for obligations outstanding at the end of the year. For this purpose, the City considers amounts collected within 60 days of year end to be available for recognition. The following major revenue sources meet the availability criterion: most state-shared revenue, state gas and weight tax revenue, and interest associated with the current fiscal period. Proprietary funds use the economic resources measurement focus and the full accrual basis of accounting. Revenue is recorded when earned and expenses are recorded when a liability is incurred, regardless of the timing of related cash flows. Fiduciary funds use the economic resources measurement focus and the full accrual basis of accounting. Fund Accounting: The City accounts for its various activities in several different funds in order to demonstrate accountability for how it has spent certain resources - separate funds allow the City to show the particular expenditures that specific revenues were used for. The various funds are aggregated into three broad fund types: -25-
Page 30
Text of page 30
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
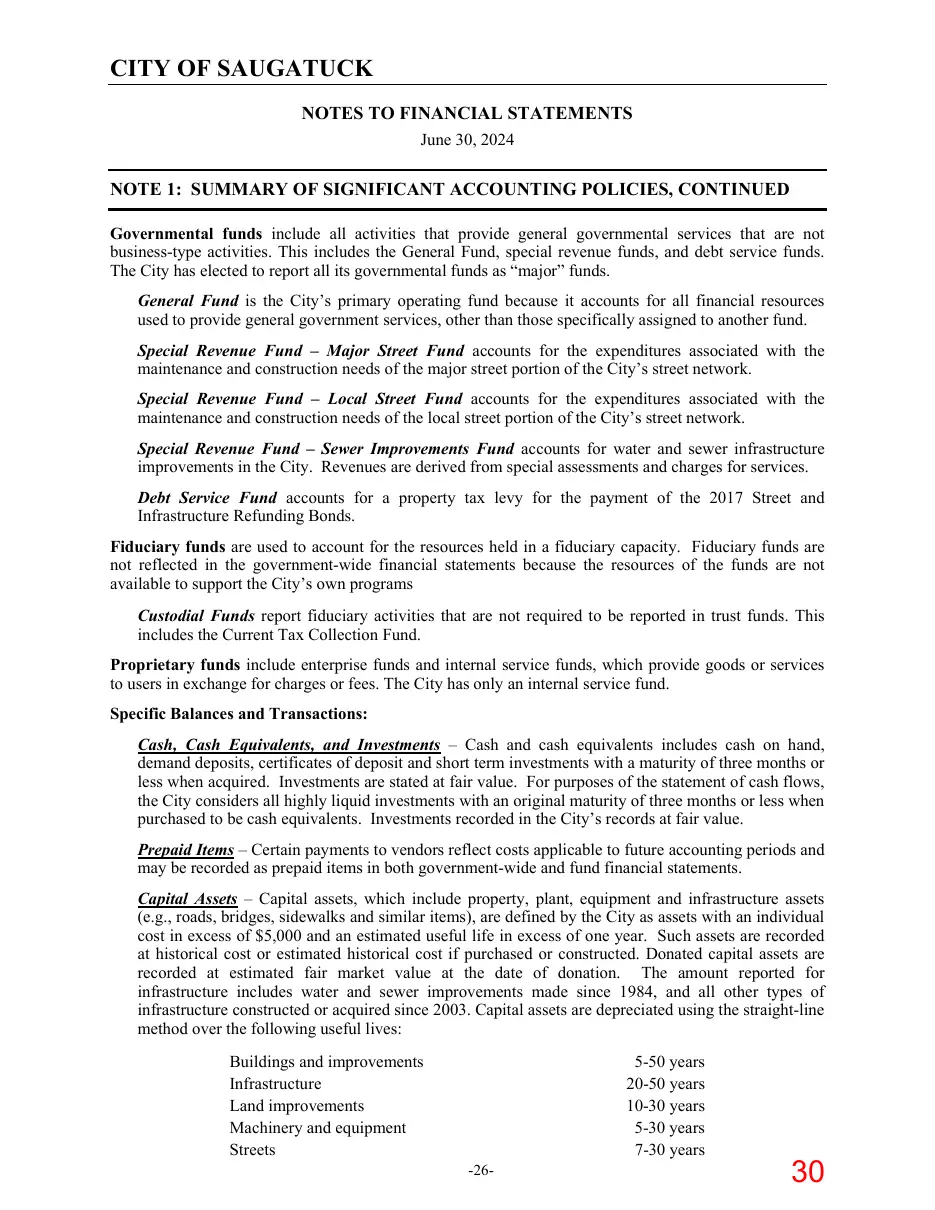
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES, CONTINUED Governmental funds include all activities that provide general governmental services that are not business-type activities. This includes the General Fund, special revenue funds, and debt service funds. The City has elected to report all its governmental funds as “major” funds. General Fund is the City’s primary operating fund because it accounts for all financial resources used to provide general government services, other than those specifically assigned to another fund. Special Revenue Fund – Major Street Fund accounts for the expenditures associated with the maintenance and construction needs of the major street portion of the City’s street network. Special Revenue Fund – Local Street Fund accounts for the expenditures associated with the maintenance and construction needs of the local street portion of the City’s street network. Special Revenue Fund – Sewer Improvements Fund accounts for water and sewer infrastructure improvements in the City. Revenues are derived from special assessments and charges for services. Debt Service Fund accounts for a property tax levy for the payment of the 2017 Street and Infrastructure Refunding Bonds. Fiduciary funds are used to account for the resources held in a fiduciary capacity. Fiduciary funds are not reflected in the government-wide financial statements because the resources of the funds are not available to support the City’s own programs Custodial Funds report fiduciary activities that are not required to be reported in trust funds. This includes the Current Tax Collection Fund. Proprietary funds include enterprise funds and internal service funds, which provide goods or services to users in exchange for charges or fees. The City has only an internal service fund. Specific Balances and Transactions: Cash, Cash Equivalents, and Investments – Cash and cash equivalents includes cash on hand, demand deposits, certificates of deposit and short term investments with a maturity of three months or less when acquired. Investments are stated at fair value. For purposes of the statement of cash flows, the City considers all highly liquid investments with an original maturity of three months or less when purchased to be cash equivalents. Investments recorded in the City’s records at fair value. Prepaid Items – Certain payments to vendors reflect costs applicable to future accounting periods and may be recorded as prepaid items in both government-wide and fund financial statements. Capital Assets – Capital assets, which include property, plant, equipment and infrastructure assets (e.g., roads, bridges, sidewalks and similar items), are defined by the City as assets with an individual cost in excess of $5,000 and an estimated useful life in excess of one year. Such assets are recorded at historical cost or estimated historical cost if purchased or constructed. Donated capital assets are recorded at estimated fair market value at the date of donation. The amount reported for infrastructure includes water and sewer improvements made since 1984, and all other types of infrastructure constructed or acquired since 2003. Capital assets are depreciated using the straight-line method over the following useful lives: Buildings and improvements Infrastructure Land improvements Machinery and equipment Streets
5-50 years 20-50 years 10-30 years 5-30 years 7-30 years -26-
Page 31
Text of page 31
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
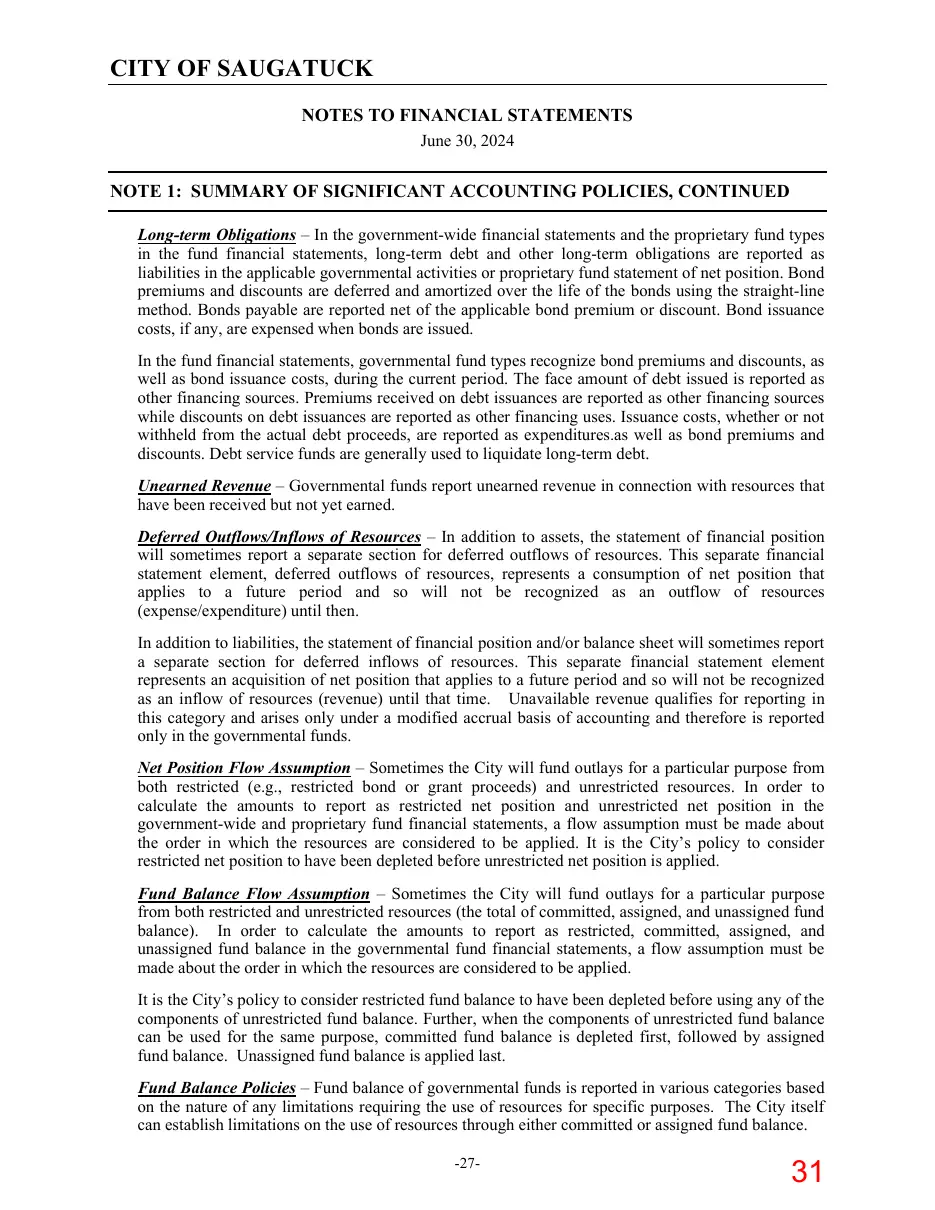
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES, CONTINUED Long-term Obligations – In the government-wide financial statements and the proprietary fund types in the fund financial statements, long-term debt and other long-term obligations are reported as liabilities in the applicable governmental activities or proprietary fund statement of net position. Bond premiums and discounts are deferred and amortized over the life of the bonds using the straight-line method. Bonds payable are reported net of the applicable bond premium or discount. Bond issuance costs, if any, are expensed when bonds are issued. In the fund financial statements, governmental fund types recognize bond premiums and discounts, as well as bond issuance costs, during the current period. The face amount of debt issued is reported as other financing sources. Premiums received on debt issuances are reported as other financing sources while discounts on debt issuances are reported as other financing uses. Issuance costs, whether or not withheld from the actual debt proceeds, are reported as expenditures.as well as bond premiums and discounts. Debt service funds are generally used to liquidate long-term debt. Unearned Revenue – Governmental funds report unearned revenue in connection with resources that have been received but not yet earned. Deferred Outflows/Inflows of Resources – In addition to assets, the statement of financial position will sometimes report a separate section for deferred outflows of resources. This separate financial statement element, deferred outflows of resources, represents a consumption of net position that applies to a future period and so will not be recognized as an outflow of resources (expense/expenditure) until then. In addition to liabilities, the statement of financial position and/or balance sheet will sometimes report a separate section for deferred inflows of resources. This separate financial statement element represents an acquisition of net position that applies to a future period and so will not be recognized as an inflow of resources (revenue) until that time. Unavailable revenue qualifies for reporting in this category and arises only under a modified accrual basis of accounting and therefore is reported only in the governmental funds. Net Position Flow Assumption – Sometimes the City will fund outlays for a particular purpose from both restricted (e.g., restricted bond or grant proceeds) and unrestricted resources. In order to calculate the amounts to report as restricted net position and unrestricted net position in the government-wide and proprietary fund financial statements, a flow assumption must be made about the order in which the resources are considered to be applied. It is the City’s policy to consider restricted net position to have been depleted before unrestricted net position is applied. Fund Balance Flow Assumption – Sometimes the City will fund outlays for a particular purpose from both restricted and unrestricted resources (the total of committed, assigned, and unassigned fund balance). In order to calculate the amounts to report as restricted, committed, assigned, and unassigned fund balance in the governmental fund financial statements, a flow assumption must be made about the order in which the resources are considered to be applied. It is the City’s policy to consider restricted fund balance to have been depleted before using any of the components of unrestricted fund balance. Further, when the components of unrestricted fund balance can be used for the same purpose, committed fund balance is depleted first, followed by assigned fund balance. Unassigned fund balance is applied last. Fund Balance Policies – Fund balance of governmental funds is reported in various categories based on the nature of any limitations requiring the use of resources for specific purposes. The City itself can establish limitations on the use of resources through either committed or assigned fund balance. -27-
Page 32
Text of page 32
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
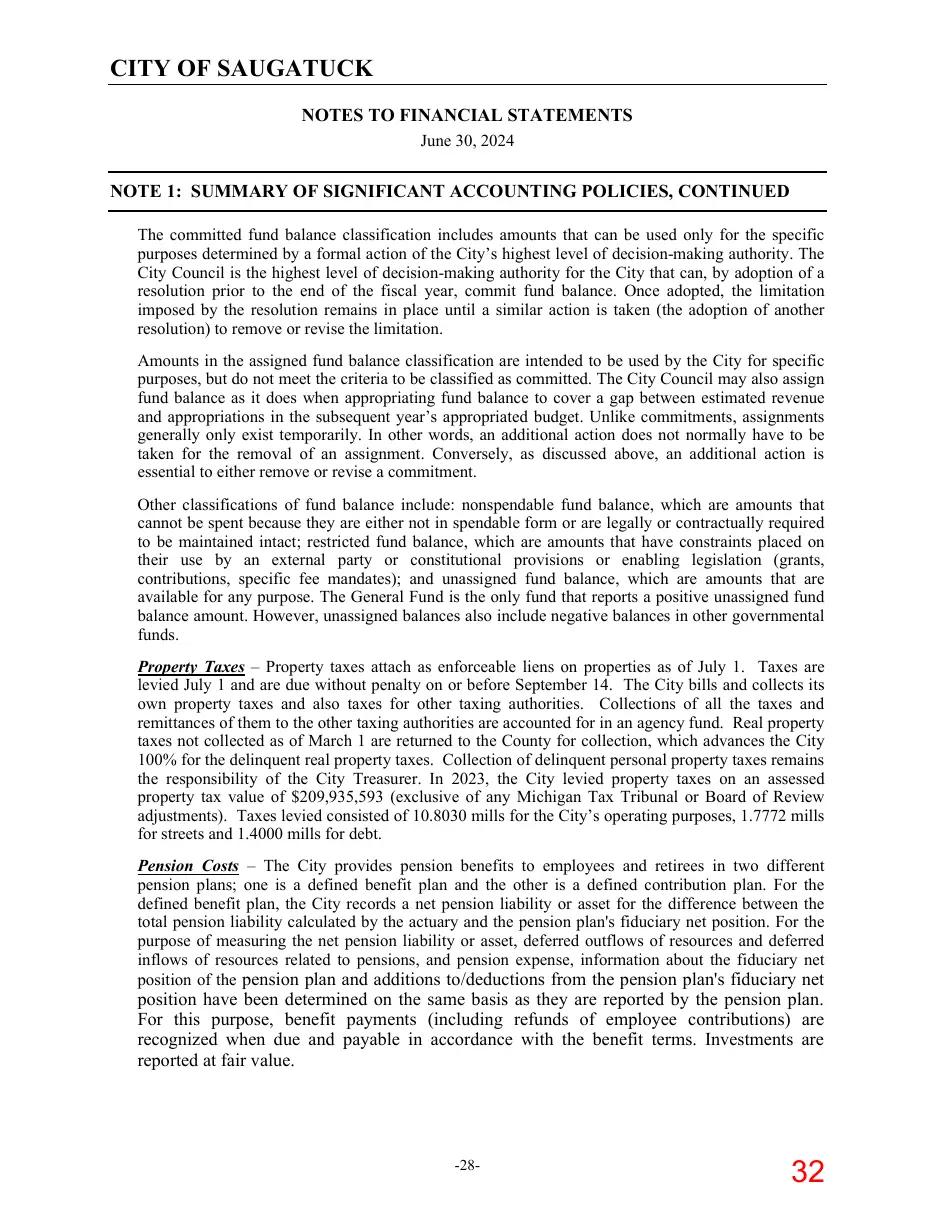
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES, CONTINUED The committed fund balance classification includes amounts that can be used only for the specific purposes determined by a formal action of the City’s highest level of decision-making authority. The City Council is the highest level of decision-making authority for the City that can, by adoption of a resolution prior to the end of the fiscal year, commit fund balance. Once adopted, the limitation imposed by the resolution remains in place until a similar action is taken (the adoption of another resolution) to remove or revise the limitation. Amounts in the assigned fund balance classification are intended to be used by the City for specific purposes, but do not meet the criteria to be classified as committed. The City Council may also assign fund balance as it does when appropriating fund balance to cover a gap between estimated revenue and appropriations in the subsequent year’s appropriated budget. Unlike commitments, assignments generally only exist temporarily. In other words, an additional action does not normally have to be taken for the removal of an assignment. Conversely, as discussed above, an additional action is essential to either remove or revise a commitment. Other classifications of fund balance include: nonspendable fund balance, which are amounts that cannot be spent because they are either not in spendable form or are legally or contractually required to be maintained intact; restricted fund balance, which are amounts that have constraints placed on their use by an external party or constitutional provisions or enabling legislation (grants, contributions, specific fee mandates); and unassigned fund balance, which are amounts that are available for any purpose. The General Fund is the only fund that reports a positive unassigned fund balance amount. However, unassigned balances also include negative balances in other governmental funds. Property Taxes – Property taxes attach as enforceable liens on properties as of July 1. Taxes are levied July 1 and are due without penalty on or before September 14. The City bills and collects its own property taxes and also taxes for other taxing authorities. Collections of all the taxes and remittances of them to the other taxing authorities are accounted for in an agency fund. Real property taxes not collected as of March 1 are returned to the County for collection, which advances the City 100% for the delinquent real property taxes. Collection of delinquent personal property taxes remains the responsibility of the City Treasurer. In 2023, the City levied property taxes on an assessed property tax value of $209,935,593 (exclusive of any Michigan Tax Tribunal or Board of Review adjustments). Taxes levied consisted of 10.8030 mills for the City’s operating purposes, 1.7772 mills for streets and 1.4000 mills for debt. Pension Costs – The City provides pension benefits to employees and retirees in two different pension plans; one is a defined benefit plan and the other is a defined contribution plan. For the defined benefit plan, the City records a net pension liability or asset for the difference between the total pension liability calculated by the actuary and the pension plan's fiduciary net position. For the purpose of measuring the net pension liability or asset, deferred outflows of resources and deferred inflows of resources related to pensions, and pension expense, information about the fiduciary net position of the pension plan and additions to/deductions from the pension plan's fiduciary net
position have been determined on the same basis as they are reported by the pension plan. For this purpose, benefit payments (including refunds of employee contributions) are recognized when due and payable in accordance with the benefit terms. Investments are reported at fair value.
-28-
Page 33
Text of page 33
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
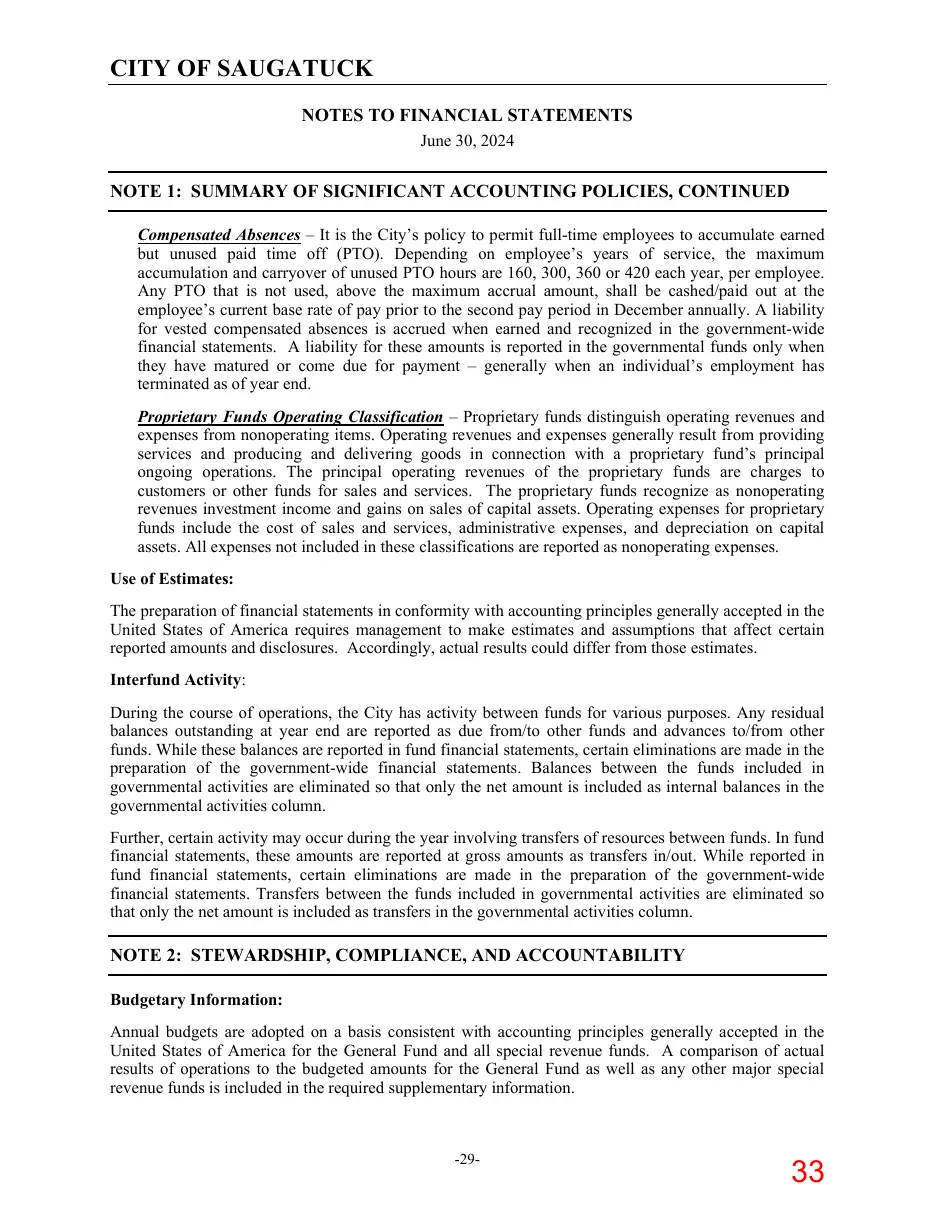
NOTE 1: SUMMARY OF SIGNIFICANT ACCOUNTING POLICIES, CONTINUED Compensated Absences – It is the City’s policy to permit full-time employees to accumulate earned but unused paid time off (PTO). Depending on employee’s years of service, the maximum accumulation and carryover of unused PTO hours are 160, 300, 360 or 420 each year, per employee. Any PTO that is not used, above the maximum accrual amount, shall be cashed/paid out at the employee’s current base rate of pay prior to the second pay period in December annually. A liability for vested compensated absences is accrued when earned and recognized in the government-wide financial statements. A liability for these amounts is reported in the governmental funds only when they have matured or come due for payment – generally when an individual’s employment has terminated as of year end. Proprietary Funds Operating Classification – Proprietary funds distinguish operating revenues and expenses from nonoperating items. Operating revenues and expenses generally result from providing services and producing and delivering goods in connection with a proprietary fund’s principal ongoing operations. The principal operating revenues of the proprietary funds are charges to customers or other funds for sales and services. The proprietary funds recognize as nonoperating revenues investment income and gains on sales of capital assets. Operating expenses for proprietary funds include the cost of sales and services, administrative expenses, and depreciation on capital assets. All expenses not included in these classifications are reported as nonoperating expenses. Use of Estimates: The preparation of financial statements in conformity with accounting principles generally accepted in the United States of America requires management to make estimates and assumptions that affect certain reported amounts and disclosures. Accordingly, actual results could differ from those estimates. Interfund Activity: During the course of operations, the City has activity between funds for various purposes. Any residual balances outstanding at year end are reported as due from/to other funds and advances to/from other funds. While these balances are reported in fund financial statements, certain eliminations are made in the preparation of the government-wide financial statements. Balances between the funds included in governmental activities are eliminated so that only the net amount is included as internal balances in the governmental activities column. Further, certain activity may occur during the year involving transfers of resources between funds. In fund financial statements, these amounts are reported at gross amounts as transfers in/out. While reported in fund financial statements, certain eliminations are made in the preparation of the government-wide financial statements. Transfers between the funds included in governmental activities are eliminated so that only the net amount is included as transfers in the governmental activities column.
NOTE 2: STEWARDSHIP, COMPLIANCE, AND ACCOUNTABILITY Budgetary Information: Annual budgets are adopted on a basis consistent with accounting principles generally accepted in the United States of America for the General Fund and all special revenue funds. A comparison of actual results of operations to the budgeted amounts for the General Fund as well as any other major special revenue funds is included in the required supplementary information.
-29-
Page 34
Text of page 34
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
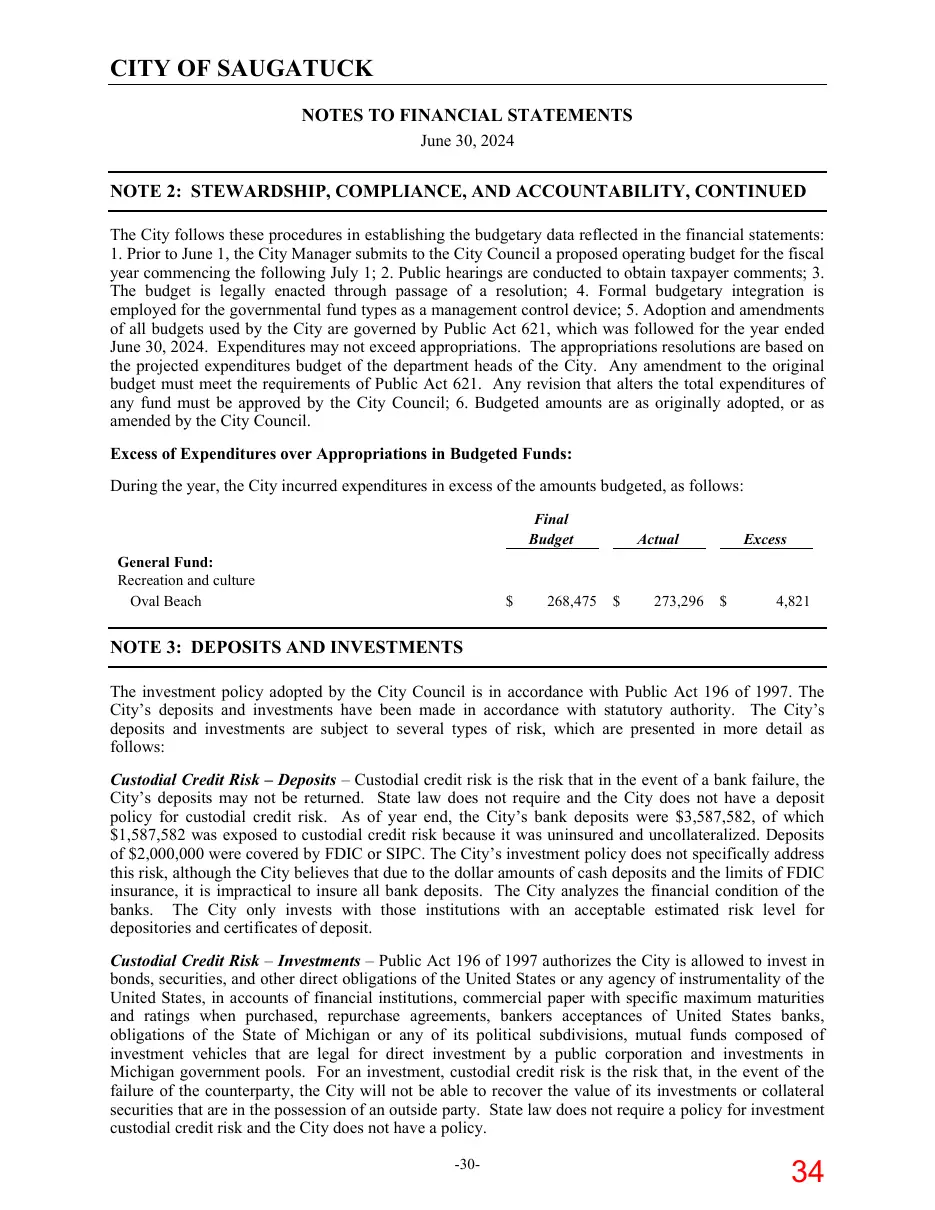
NOTE 2: STEWARDSHIP, COMPLIANCE, AND ACCOUNTABILITY, CONTINUED The City follows these procedures in establishing the budgetary data reflected in the financial statements: 1. Prior to June 1, the City Manager submits to the City Council a proposed operating budget for the fiscal year commencing the following July 1; 2. Public hearings are conducted to obtain taxpayer comments; 3. The budget is legally enacted through passage of a resolution; 4. Formal budgetary integration is employed for the governmental fund types as a management control device; 5. Adoption and amendments of all budgets used by the City are governed by Public Act 621, which was followed for the year ended June 30, 2024. Expenditures may not exceed appropriations. The appropriations resolutions are based on the projected expenditures budget of the department heads of the City. Any amendment to the original budget must meet the requirements of Public Act 621. Any revision that alters the total expenditures of any fund must be approved by the City Council; 6. Budgeted amounts are as originally adopted, or as amended by the City Council. Excess of Expenditures over Appropriations in Budgeted Funds: During the year, the City incurred expenditures in excess of the amounts budgeted, as follows: Final Budget General Fund: Recreation and culture Oval Beach
268,475
Actual
273,296
Excess
4,821
NOTE 3: DEPOSITS AND INVESTMENTS The investment policy adopted by the City Council is in accordance with Public Act 196 of 1997. The City’s deposits and investments have been made in accordance with statutory authority. The City’s deposits and investments are subject to several types of risk, which are presented in more detail as follows: Custodial Credit Risk – Deposits – Custodial credit risk is the risk that in the event of a bank failure, the City’s deposits may not be returned. State law does not require and the City does not have a deposit policy for custodial credit risk. As of year end, the City’s bank deposits were $3,587,582, of which $1,587,582 was exposed to custodial credit risk because it was uninsured and uncollateralized. Deposits of $2,000,000 were covered by FDIC or SIPC. The City’s investment policy does not specifically address this risk, although the City believes that due to the dollar amounts of cash deposits and the limits of FDIC insurance, it is impractical to insure all bank deposits. The City analyzes the financial condition of the banks. The City only invests with those institutions with an acceptable estimated risk level for depositories and certificates of deposit. Custodial Credit Risk – Investments – Public Act 196 of 1997 authorizes the City is allowed to invest in bonds, securities, and other direct obligations of the United States or any agency of instrumentality of the United States, in accounts of financial institutions, commercial paper with specific maximum maturities and ratings when purchased, repurchase agreements, bankers acceptances of United States banks, obligations of the State of Michigan or any of its political subdivisions, mutual funds composed of investment vehicles that are legal for direct investment by a public corporation and investments in Michigan government pools. For an investment, custodial credit risk is the risk that, in the event of the failure of the counterparty, the City will not be able to recover the value of its investments or collateral securities that are in the possession of an outside party. State law does not require a policy for investment custodial credit risk and the City does not have a policy. -30-
Page 35
Text of page 35
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
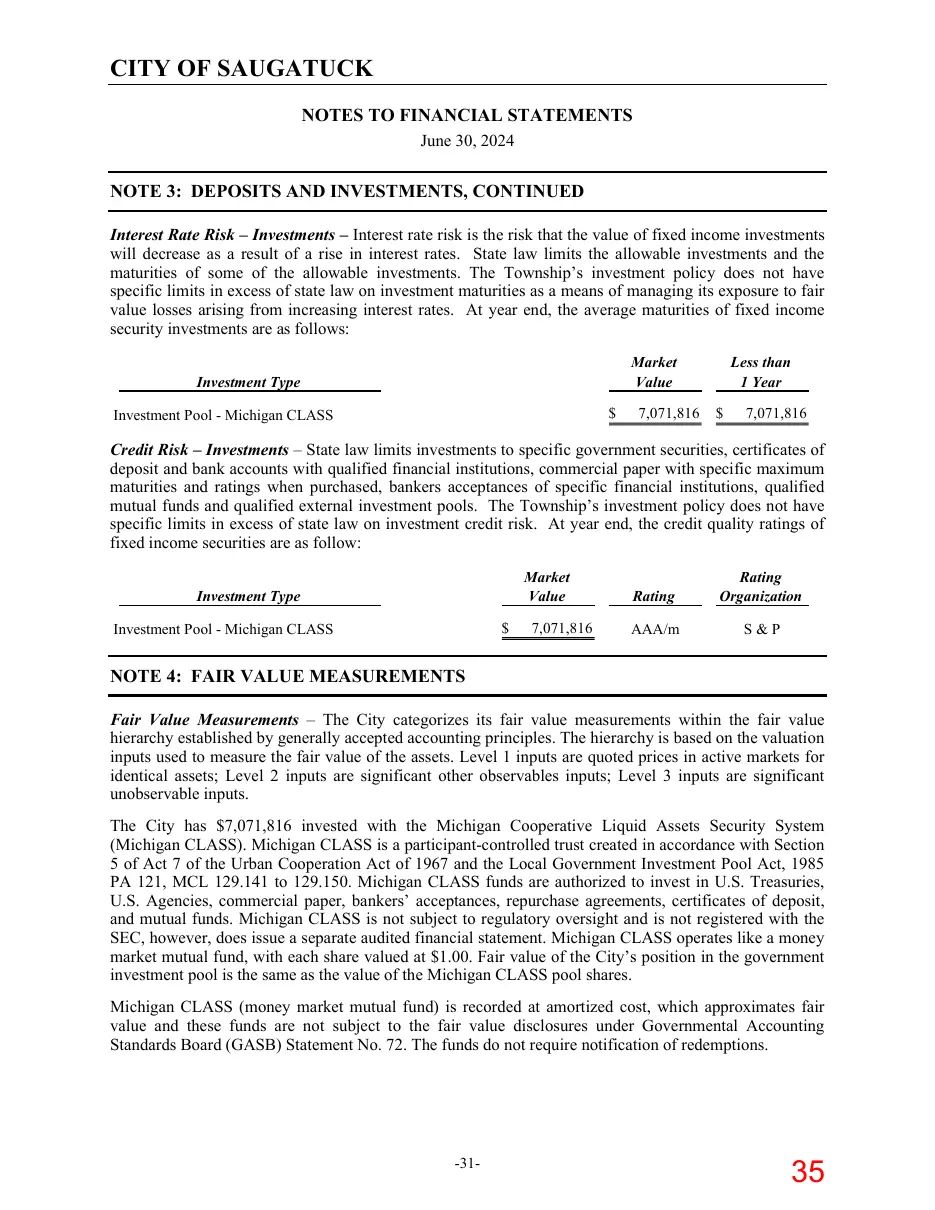
NOTE 3: DEPOSITS AND INVESTMENTS, CONTINUED Interest Rate Risk – Investments – Interest rate risk is the risk that the value of fixed income investments will decrease as a result of a rise in interest rates. State law limits the allowable investments and the maturities of some of the allowable investments. The Township’s investment policy does not have specific limits in excess of state law on investment maturities as a means of managing its exposure to fair value losses arising from increasing interest rates. At year end, the average maturities of fixed income security investments are as follows: Market Value
Investment Type $
Investment Pool - Michigan CLASS
7,071,816
Less than 1 Year $
7,071,816
Credit Risk – Investments – State law limits investments to specific government securities, certificates of deposit and bank accounts with qualified financial institutions, commercial paper with specific maximum maturities and ratings when purchased, bankers acceptances of specific financial institutions, qualified mutual funds and qualified external investment pools. The Township’s investment policy does not have specific limits in excess of state law on investment credit risk. At year end, the credit quality ratings of fixed income securities are as follow: Investment Type $
Investment Pool - Michigan CLASS
Market Value
Rating
Rating Organization
7,071,816
AAA/m
S&P
NOTE 4: FAIR VALUE MEASUREMENTS Fair Value Measurements – The City categorizes its fair value measurements within the fair value hierarchy established by generally accepted accounting principles. The hierarchy is based on the valuation inputs used to measure the fair value of the assets. Level 1 inputs are quoted prices in active markets for identical assets; Level 2 inputs are significant other observables inputs; Level 3 inputs are significant unobservable inputs. The City has $7,071,816 invested with the Michigan Cooperative Liquid Assets Security System (Michigan CLASS). Michigan CLASS is a participant-controlled trust created in accordance with Section 5 of Act 7 of the Urban Cooperation Act of 1967 and the Local Government Investment Pool Act, 1985 PA 121, MCL 129.141 to 129.150. Michigan CLASS funds are authorized to invest in U.S. Treasuries, U.S. Agencies, commercial paper, bankers’ acceptances, repurchase agreements, certificates of deposit, and mutual funds. Michigan CLASS is not subject to regulatory oversight and is not registered with the SEC, however, does issue a separate audited financial statement. Michigan CLASS operates like a money market mutual fund, with each share valued at $1.00. Fair value of the City’s position in the government investment pool is the same as the value of the Michigan CLASS pool shares. Michigan CLASS (money market mutual fund) is recorded at amortized cost, which approximates fair value and these funds are not subject to the fair value disclosures under Governmental Accounting Standards Board (GASB) Statement No. 72. The funds do not require notification of redemptions.
-31-
Page 36
Text of page 36
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
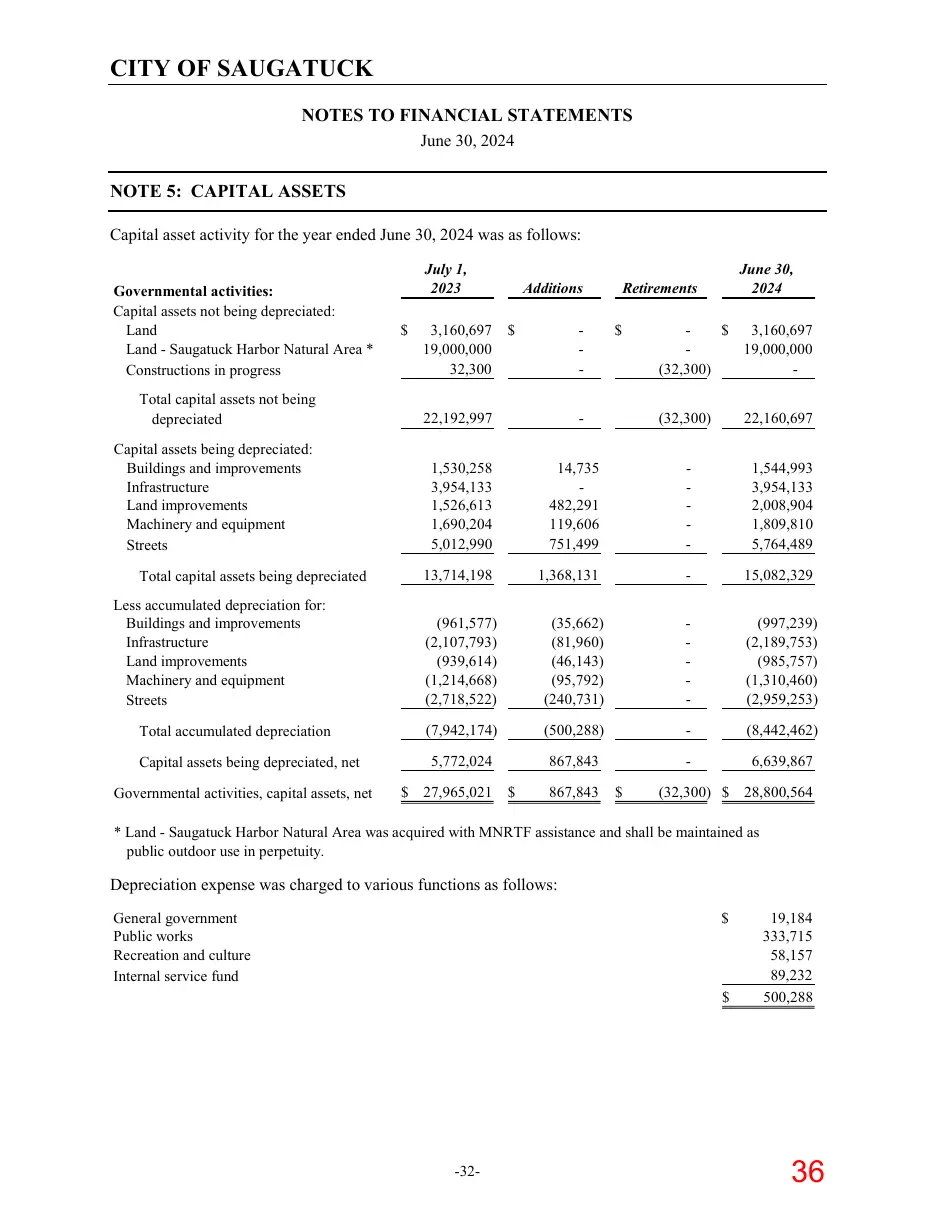
NOTE 5: CAPITAL ASSETS Capital asset activity for the year ended June 30, 2024 was as follows: Governmental activities: Capital assets not being depreciated: Land Land - Saugatuck Harbor Natural Area * Constructions in progress
July 1, 2023 $
3,160,697 19,000,000 32,300
Additions $
June 30, 2024
Retirements $
$ 3,160,697 19,000,000 (32,300) -
Total capital assets not being depreciated
22,192,997
(32,300)
22,160,697
Capital assets being depreciated: Buildings and improvements Infrastructure Land improvements Machinery and equipment Streets
1,530,258 3,954,133 1,526,613 1,690,204 5,012,990
14,735 482,291 119,606 751,499
1,544,993 3,954,133 2,008,904 1,809,810 5,764,489
13,714,198
1,368,131
15,082,329
Less accumulated depreciation for: Buildings and improvements Infrastructure Land improvements Machinery and equipment Streets
(961,577) (2,107,793) (939,614) (1,214,668) (2,718,522)
(35,662) (81,960) (46,143) (95,792) (240,731)
(997,239) (2,189,753) (985,757) (1,310,460) (2,959,253)
Total accumulated depreciation
(7,942,174)
(500,288)
(8,442,462)
Capital assets being depreciated, net
5,772,024
867,843
6,639,867
Total capital assets being depreciated
Governmental activities, capital assets, net
$ 27,965,021
867,843
(32,300) $ 28,800,564
* Land - Saugatuck Harbor Natural Area was acquired with MNRTF assistance and shall be maintained as public outdoor use in perpetuity.
Depreciation expense was charged to various functions as follows: General government Public works Recreation and culture Internal service fund
-32-
19,184 333,715 58,157 89,232 500,288
Page 37
Text of page 37
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
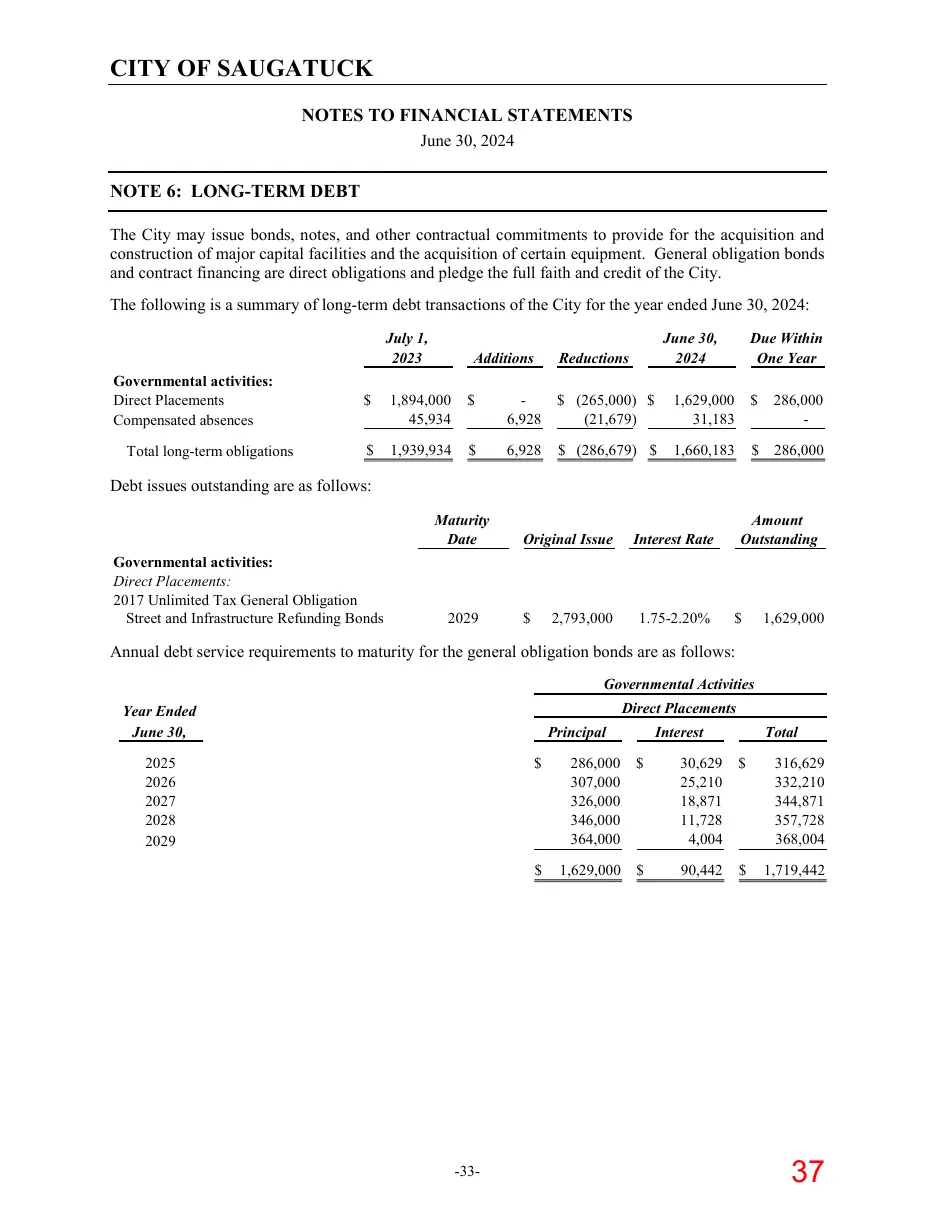
NOTE 6: LONG-TERM DEBT The City may issue bonds, notes, and other contractual commitments to provide for the acquisition and construction of major capital facilities and the acquisition of certain equipment. General obligation bonds and contract financing are direct obligations and pledge the full faith and credit of the City. The following is a summary of long-term debt transactions of the City for the year ended June 30, 2024: July 1, 2023 Governmental activities: Direct Placements Compensated absences Total long-term obligations
Additions
Reductions
June 30, 2024
Due Within One Year
1,894,000 45,934
6,928
$ (265,000) $ (21,679)
1,629,000 31,183
286,000 -
1,939,934
6,928
$ (286,679) $
1,660,183
$ 286,000
Debt issues outstanding are as follows: Maturity Date Governmental activities: Direct Placements: 2017 Unlimited Tax General Obligation Street and Infrastructure Refunding Bonds
2029
Original Issue
Interest Rate
Amount Outstanding
1.75-2.20%
2,793,000
1,629,000
Annual debt service requirements to maturity for the general obligation bonds are as follows: Governmental Activities
Direct Placements
Year Ended June 30,
Principal
2025 2026 2027 2028 2029
-33-
Interest
Total
286,000 307,000 326,000 346,000 364,000
30,629 25,210 18,871 11,728 4,004
316,629 332,210 344,871 357,728 368,004
1,629,000
90,442
1,719,442
Page 38
Text of page 38
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
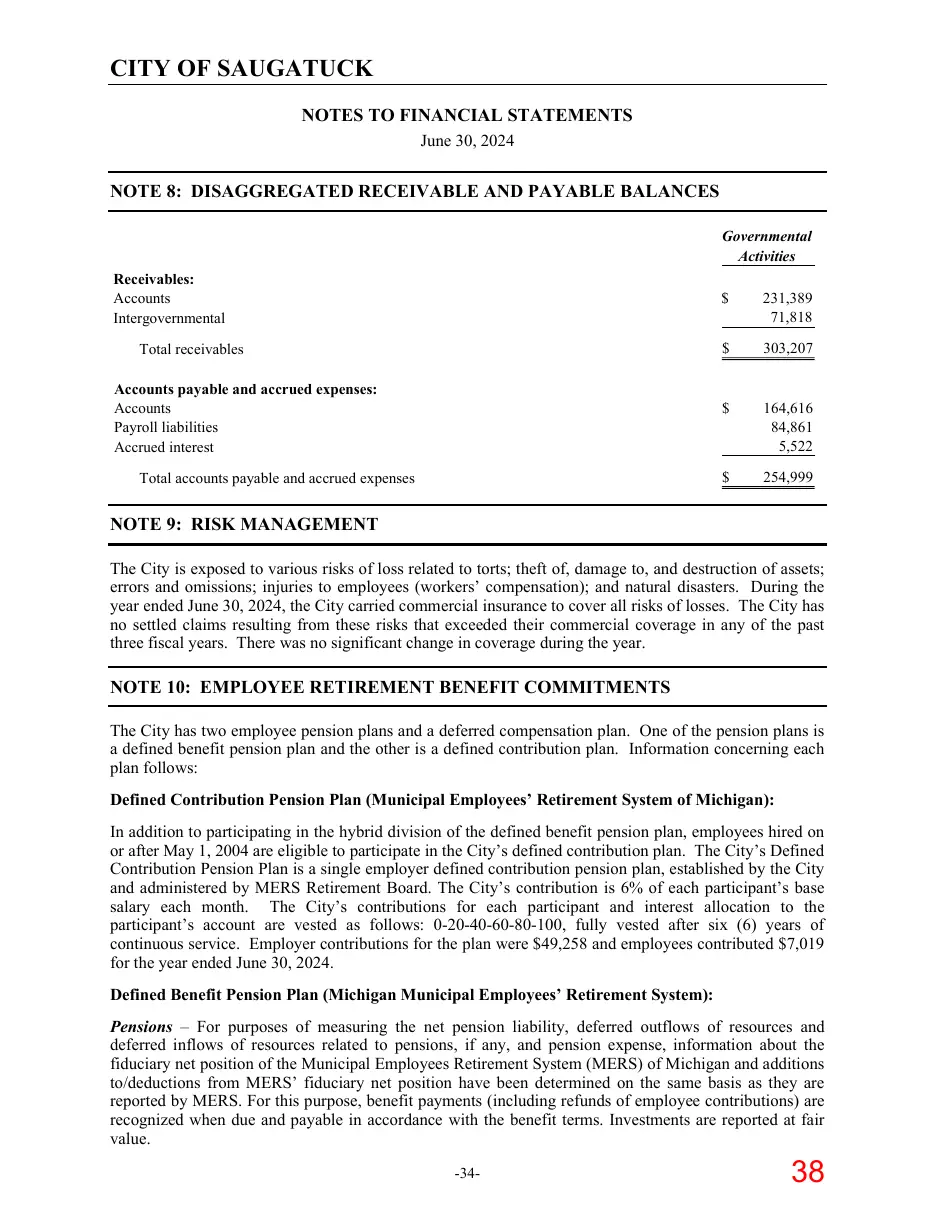
NOTE 8: DISAGGREGATED RECEIVABLE AND PAYABLE BALANCES Governmental Activities Receivables: Accounts Intergovernmental Total receivables Accounts payable and accrued expenses: Accounts Payroll liabilities Accrued interest Total accounts payable and accrued expenses
231,389 71,818
303,207
164,616 84,861 5,522
254,999
NOTE 9: RISK MANAGEMENT The City is exposed to various risks of loss related to torts; theft of, damage to, and destruction of assets; errors and omissions; injuries to employees (workers’ compensation); and natural disasters. During the year ended June 30, 2024, the City carried commercial insurance to cover all risks of losses. The City has no settled claims resulting from these risks that exceeded their commercial coverage in any of the past three fiscal years. There was no significant change in coverage during the year.
NOTE 10: EMPLOYEE RETIREMENT BENEFIT COMMITMENTS The City has two employee pension plans and a deferred compensation plan. One of the pension plans is a defined benefit pension plan and the other is a defined contribution plan. Information concerning each plan follows: Defined Contribution Pension Plan (Municipal Employees’ Retirement System of Michigan): In addition to participating in the hybrid division of the defined benefit pension plan, employees hired on or after May 1, 2004 are eligible to participate in the City’s defined contribution plan. The City’s Defined Contribution Pension Plan is a single employer defined contribution pension plan, established by the City and administered by MERS Retirement Board. The City’s contribution is 6% of each participant’s base salary each month. The City’s contributions for each participant and interest allocation to the participant’s account are vested as follows: 0-20-40-60-80-100, fully vested after six (6) years of continuous service. Employer contributions for the plan were $49,258 and employees contributed $7,019 for the year ended June 30, 2024. Defined Benefit Pension Plan (Michigan Municipal Employees’ Retirement System): Pensions – For purposes of measuring the net pension liability, deferred outflows of resources and deferred inflows of resources related to pensions, if any, and pension expense, information about the fiduciary net position of the Municipal Employees Retirement System (MERS) of Michigan and additions to/deductions from MERS’ fiduciary net position have been determined on the same basis as they are reported by MERS. For this purpose, benefit payments (including refunds of employee contributions) are recognized when due and payable in accordance with the benefit terms. Investments are reported at fair value. -34-
Page 39
Text of page 39
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
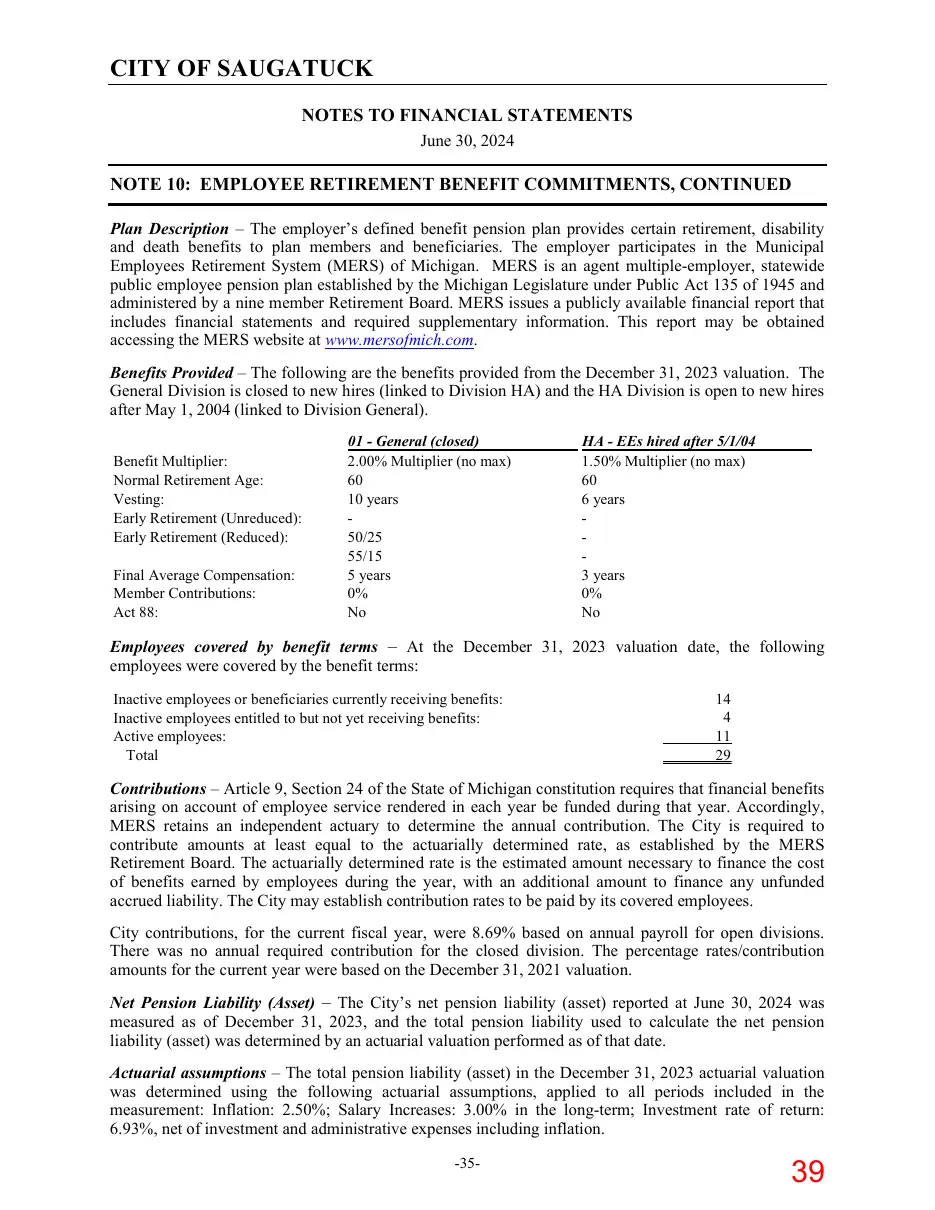
NOTE 10: EMPLOYEE RETIREMENT BENEFIT COMMITMENTS, CONTINUED Plan Description – The employer’s defined benefit pension plan provides certain retirement, disability and death benefits to plan members and beneficiaries. The employer participates in the Municipal Employees Retirement System (MERS) of Michigan. MERS is an agent multiple-employer, statewide public employee pension plan established by the Michigan Legislature under Public Act 135 of 1945 and administered by a nine member Retirement Board. MERS issues a publicly available financial report that includes financial statements and required supplementary information. This report may be obtained accessing the MERS website at www.mersofmich.com. Benefits Provided – The following are the benefits provided from the December 31, 2023 valuation. The General Division is closed to new hires (linked to Division HA) and the HA Division is open to new hires after May 1, 2004 (linked to Division General). Benefit Multiplier: Normal Retirement Age: Vesting: Early Retirement (Unreduced): Early Retirement (Reduced): Final Average Compensation: Member Contributions: Act 88:
01 - General (closed) 2.00% Multiplier (no max) 60 10 years 50/25 55/15 5 years 0% No
HA - EEs hired after 5/1/04 1.50% Multiplier (no max) 60 6 years 3 years 0% No
Employees covered by benefit terms – At the December 31, 2023 valuation date, the following employees were covered by the benefit terms: Inactive employees or beneficiaries currently receiving benefits: Inactive employees entitled to but not yet receiving benefits: Active employees: Total
14 4 11 29
Contributions – Article 9, Section 24 of the State of Michigan constitution requires that financial benefits arising on account of employee service rendered in each year be funded during that year. Accordingly, MERS retains an independent actuary to determine the annual contribution. The City is required to contribute amounts at least equal to the actuarially determined rate, as established by the MERS Retirement Board. The actuarially determined rate is the estimated amount necessary to finance the cost of benefits earned by employees during the year, with an additional amount to finance any unfunded accrued liability. The City may establish contribution rates to be paid by its covered employees. City contributions, for the current fiscal year, were 8.69% based on annual payroll for open divisions. There was no annual required contribution for the closed division. The percentage rates/contribution amounts for the current year were based on the December 31, 2021 valuation. Net Pension Liability (Asset) – The City’s net pension liability (asset) reported at June 30, 2024 was measured as of December 31, 2023, and the total pension liability used to calculate the net pension liability (asset) was determined by an actuarial valuation performed as of that date. Actuarial assumptions – The total pension liability (asset) in the December 31, 2023 actuarial valuation was determined using the following actuarial assumptions, applied to all periods included in the measurement: Inflation: 2.50%; Salary Increases: 3.00% in the long-term; Investment rate of return: 6.93%, net of investment and administrative expenses including inflation. -35-
Page 40
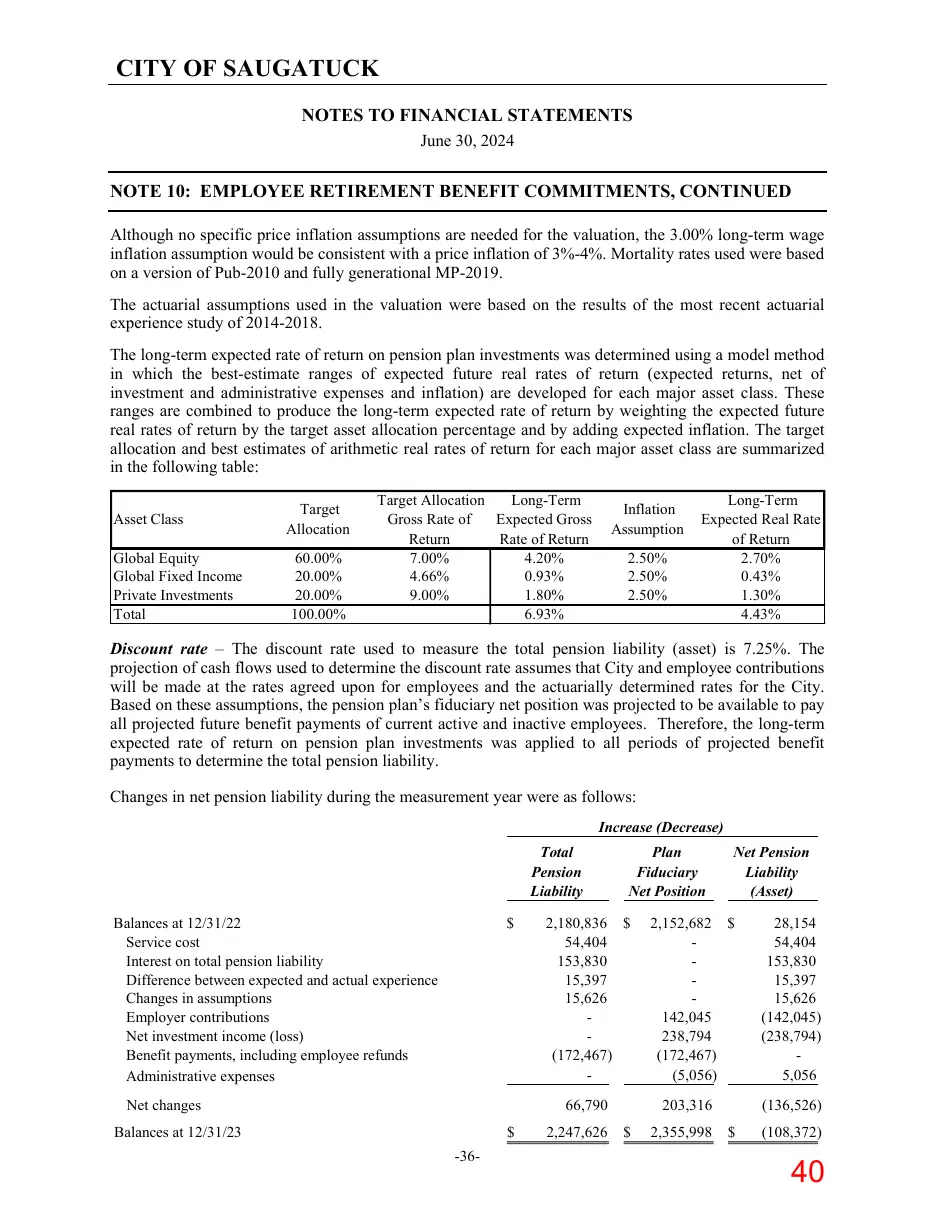
Text of page 40
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
NOTE 10: EMPLOYEE RETIREMENT BENEFIT COMMITMENTS, CONTINUED Although no specific price inflation assumptions are needed for the valuation, the 3.00% long-term wage inflation assumption would be consistent with a price inflation of 3%-4%. Mortality rates used were based on a version of Pub-2010 and fully generational MP-2019. The actuarial assumptions used in the valuation were based on the results of the most recent actuarial experience study of 2014-2018. The long-term expected rate of return on pension plan investments was determined using a model method in which the best-estimate ranges of expected future real rates of return (expected returns, net of investment and administrative expenses and inflation) are developed for each major asset class. These ranges are combined to produce the long-term expected rate of return by weighting the expected future real rates of return by the target asset allocation percentage and by adding expected inflation. The target allocation and best estimates of arithmetic real rates of return for each major asset class are summarized in the following table: Asset Class
Target Allocation
Global Equity Global Fixed Income Private Investments Total
60.00% 20.00% 20.00% 100.00%
Target Allocation Long-Term Gross Rate of Expected Gross Return Rate of Return 7.00% 4.20% 4.66% 0.93% 9.00% 1.80% 6.93%
Inflation Assumption 2.50% 2.50% 2.50%
Long-Term Expected Real Rate of Return 2.70% 0.43% 1.30% 4.43%
Discount rate – The discount rate used to measure the total pension liability (asset) is 7.25%. The projection of cash flows used to determine the discount rate assumes that City and employee contributions will be made at the rates agreed upon for employees and the actuarially determined rates for the City. Based on these assumptions, the pension plan’s fiduciary net position was projected to be available to pay all projected future benefit payments of current active and inactive employees. Therefore, the long-term expected rate of return on pension plan investments was applied to all periods of projected benefit payments to determine the total pension liability. Changes in net pension liability during the measurement year were as follows: Increase (Decrease) Total Pension Liability Balances at 12/31/22 Service cost Interest on total pension liability Difference between expected and actual experience Changes in assumptions Employer contributions Net investment income (loss) Benefit payments, including employee refunds Administrative expenses
Net changes Balances at 12/31/23
$ -36-
Plan Fiduciary Net Position
Net Pension Liability (Asset)
2,180,836 $ 54,404 153,830 15,397 15,626 (172,467) -
2,152,682 $ 142,045 238,794 (172,467) (5,056)
28,154 54,404 153,830 15,397 15,626 (142,045) (238,794) 5,056
66,790
203,316
(136,526)
2,247,626
2,355,998
(108,372)
Page 41
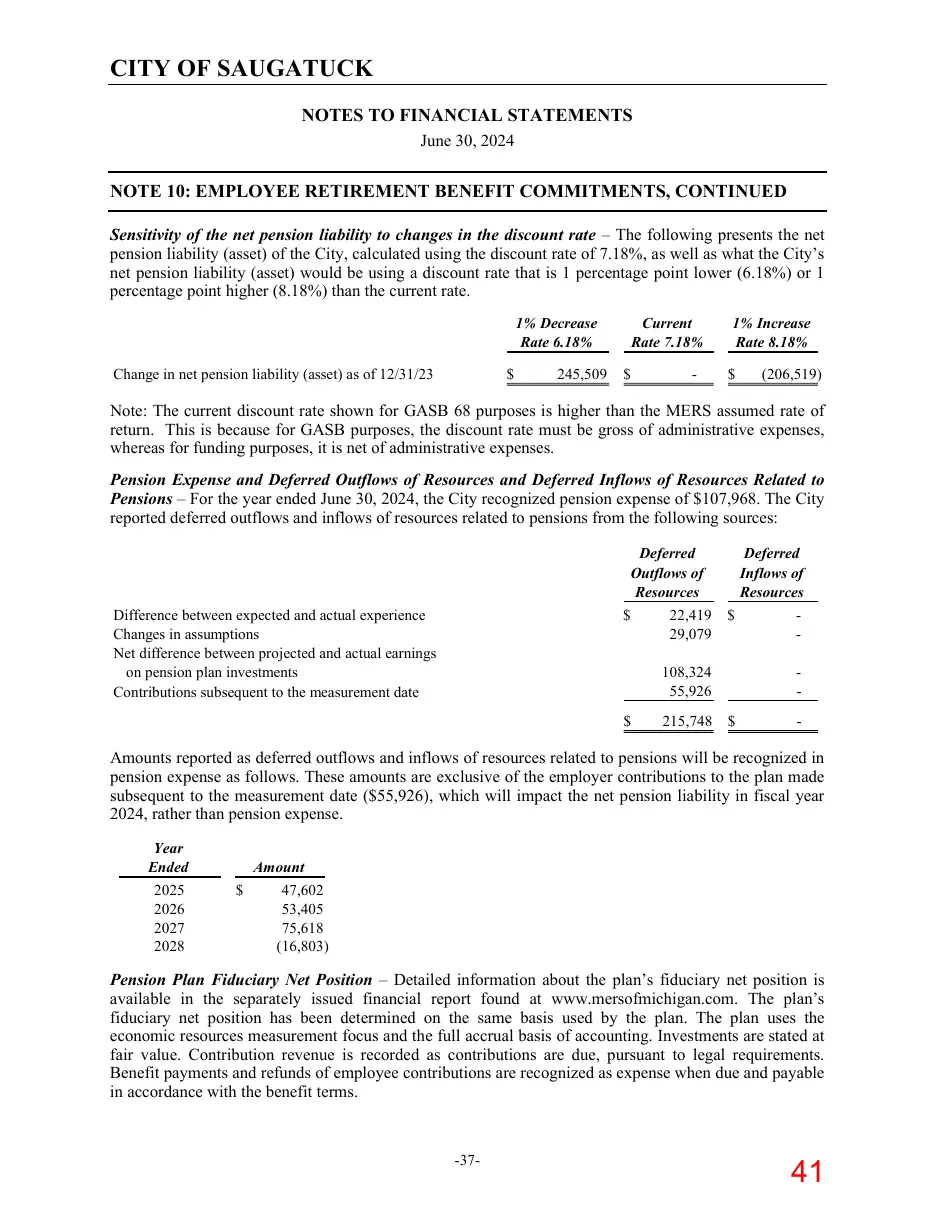
Text of page 41
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
NOTE 10: EMPLOYEE RETIREMENT BENEFIT COMMITMENTS, CONTINUED Sensitivity of the net pension liability to changes in the discount rate – The following presents the net pension liability (asset) of the City, calculated using the discount rate of 7.18%, as well as what the City’s net pension liability (asset) would be using a discount rate that is 1 percentage point lower (6.18%) or 1 percentage point higher (8.18%) than the current rate. 1% Decrease Rate 6.18% Change in net pension liability (asset) as of 12/31/23
245,509
Current Rate 7.18% $
1% Increase Rate 8.18% $
(206,519)
Note: The current discount rate shown for GASB 68 purposes is higher than the MERS assumed rate of return. This is because for GASB purposes, the discount rate must be gross of administrative expenses, whereas for funding purposes, it is net of administrative expenses. Pension Expense and Deferred Outflows of Resources and Deferred Inflows of Resources Related to Pensions – For the year ended June 30, 2024, the City recognized pension expense of $107,968. The City reported deferred outflows and inflows of resources related to pensions from the following sources: Deferred Outflows of Resources Difference between expected and actual experience Changes in assumptions Net difference between projected and actual earnings on pension plan investments Contributions subsequent to the measurement date
22,419 29,079
Deferred Inflows of Resources $
108,324 55,926 $
215,748
Amounts reported as deferred outflows and inflows of resources related to pensions will be recognized in pension expense as follows. These amounts are exclusive of the employer contributions to the plan made subsequent to the measurement date ($55,926), which will impact the net pension liability in fiscal year 2024, rather than pension expense. Year Ended 2025 2026 2027 2028
Amount $
47,602 53,405 75,618 (16,803)
Pension Plan Fiduciary Net Position – Detailed information about the plan’s fiduciary net position is available in the separately issued financial report found at www.mersofmichigan.com. The plan’s fiduciary net position has been determined on the same basis used by the plan. The plan uses the economic resources measurement focus and the full accrual basis of accounting. Investments are stated at fair value. Contribution revenue is recorded as contributions are due, pursuant to legal requirements. Benefit payments and refunds of employee contributions are recognized as expense when due and payable in accordance with the benefit terms.
-37-
Page 42
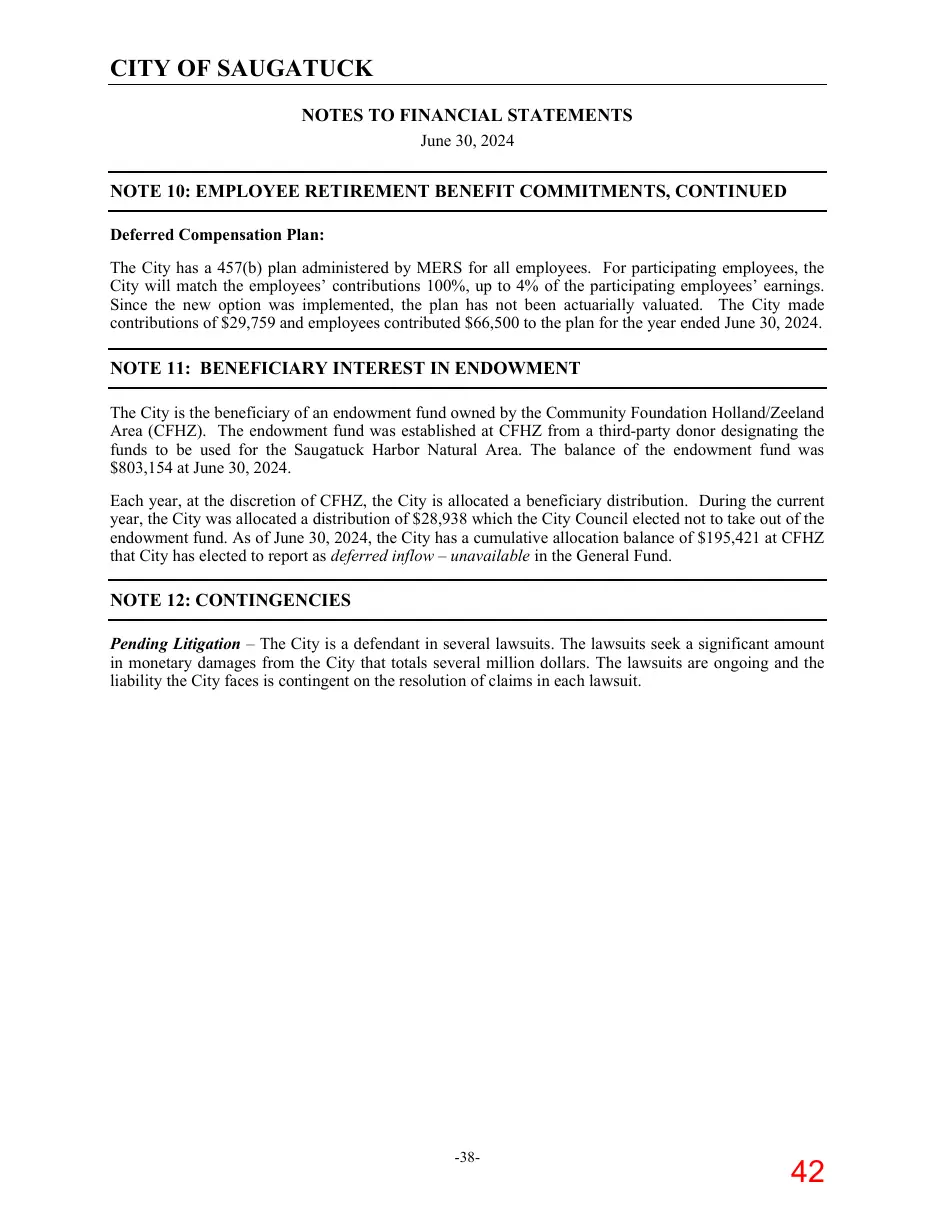
Text of page 42
CITY OF SAUGATUCK NOTES TO FINANCIAL STATEMENTS June 30, 2024
NOTE 10: EMPLOYEE RETIREMENT BENEFIT COMMITMENTS, CONTINUED Deferred Compensation Plan: The City has a 457(b) plan administered by MERS for all employees. For participating employees, the City will match the employees’ contributions 100%, up to 4% of the participating employees’ earnings. Since the new option was implemented, the plan has not been actuarially valuated. The City made contributions of $29,759 and employees contributed $66,500 to the plan for the year ended June 30, 2024.
NOTE 11: BENEFICIARY INTEREST IN ENDOWMENT The City is the beneficiary of an endowment fund owned by the Community Foundation Holland/Zeeland Area (CFHZ). The endowment fund was established at CFHZ from a third-party donor designating the funds to be used for the Saugatuck Harbor Natural Area. The balance of the endowment fund was $803,154 at June 30, 2024. Each year, at the discretion of CFHZ, the City is allocated a beneficiary distribution. During the current year, the City was allocated a distribution of $28,938 which the City Council elected not to take out of the endowment fund. As of June 30, 2024, the City has a cumulative allocation balance of $195,421 at CFHZ that City has elected to report as deferred inflow – unavailable in the General Fund.
NOTE 12: CONTINGENCIES Pending Litigation – The City is a defendant in several lawsuits. The lawsuits seek a significant amount in monetary damages from the City that totals several million dollars. The lawsuits are ongoing and the liability the City faces is contingent on the resolution of claims in each lawsuit.
-38-
Page 43
Text of page 43
REQUIRED SUPPLEMENTARY INFORMATION
Page 44
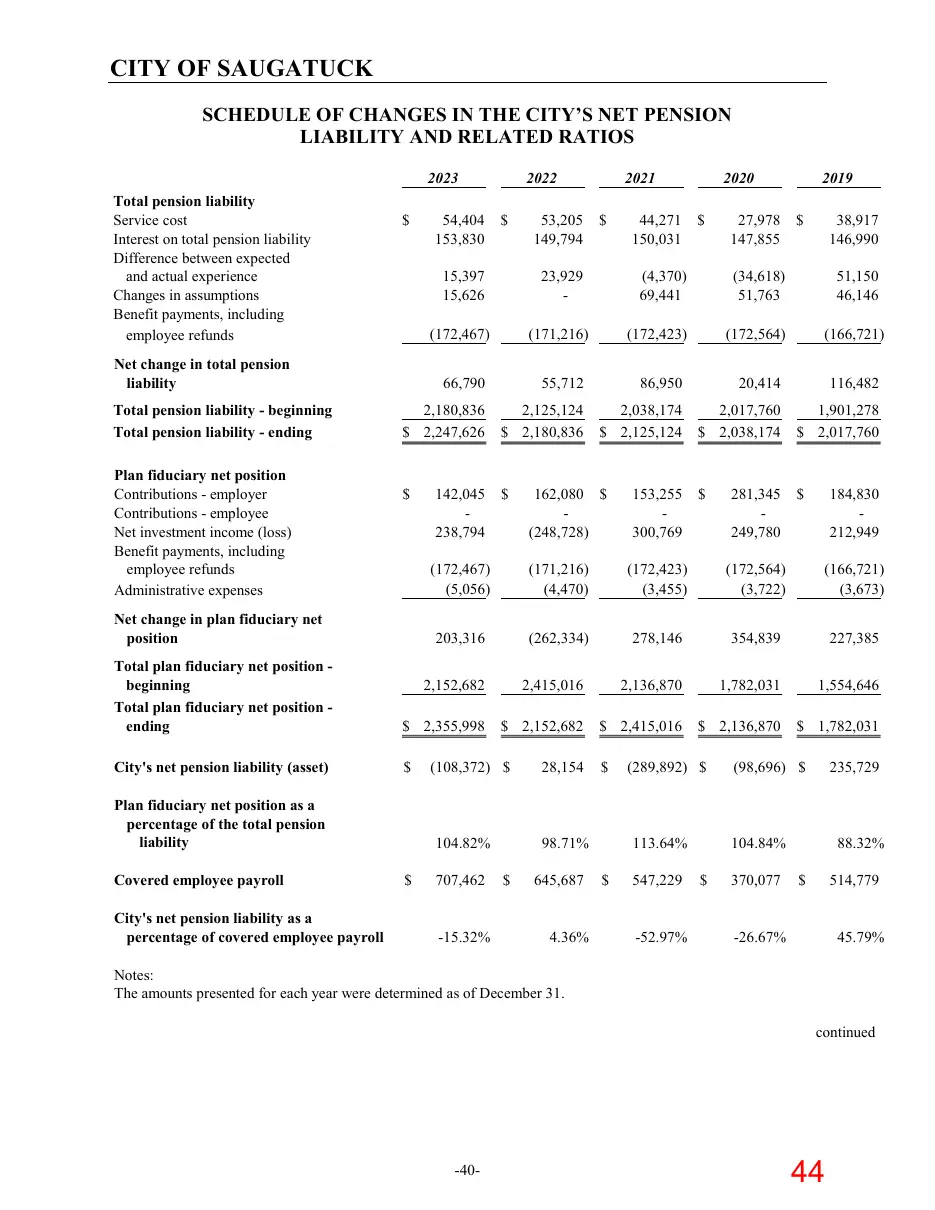
Text of page 44
CITY OF SAUGATUCK SCHEDULE OF CHANGES IN THE CITY’S NET PENSION LIABILITY AND RELATED RATIOS 2023 Total pension liability Service cost Interest on total pension liability Difference between expected and actual experience Changes in assumptions Benefit payments, including employee refunds
Plan fiduciary net position Contributions - employer Contributions - employee Net investment income (loss) Benefit payments, including employee refunds Administrative expenses
53,205 149,794
2021 $
44,271 150,031
2020 $
27,978 147,855
2019 $
38,917 146,990
15,397 15,626
23,929 -
(4,370) 69,441
(34,618) 51,763
51,150 46,146
(172,467)
(171,216)
(172,423)
(172,564)
(166,721)
66,790
55,712
86,950
20,414
116,482
2,180,836 $ 2,247,626
2,125,124 $ 2,180,836
2,038,174 $ 2,125,124
2,017,760 $ 2,038,174
1,901,278 $ 2,017,760
Net change in total pension liability Total pension liability - beginning Total pension liability - ending
54,404 153,830
2022
Net change in plan fiduciary net position
142,045 238,794
162,080 $ (248,728)
153,255 300,769
281,345 249,780
184,830 212,949
(172,467) (5,056)
(171,216) (4,470)
(172,423) (3,455)
(172,564) (3,722)
(166,721) (3,673)
203,316
(262,334)
278,146
354,839
227,385
Total plan fiduciary net position beginning Total plan fiduciary net position ending
2,152,682
2,415,016
2,136,870
1,782,031
1,554,646
$ 2,355,998
$ 2,152,682
$ 2,415,016
$ 2,136,870
$ 1,782,031
City's net pension liability (asset)
Plan fiduciary net position as a percentage of the total pension liability Covered employee payroll City's net pension liability as a percentage of covered employee payroll
(108,372) $
28,154
104.82%
98.71%
707,462
-15.32%
645,687
4.36%
(289,892) $
(98,696) $
235,729
113.64%
104.84%
88.32%
547,229
-52.97%
370,077
514,779
-26.67%
45.79%
Notes: The amounts presented for each year were determined as of December 31. continued
-40-
Page 45
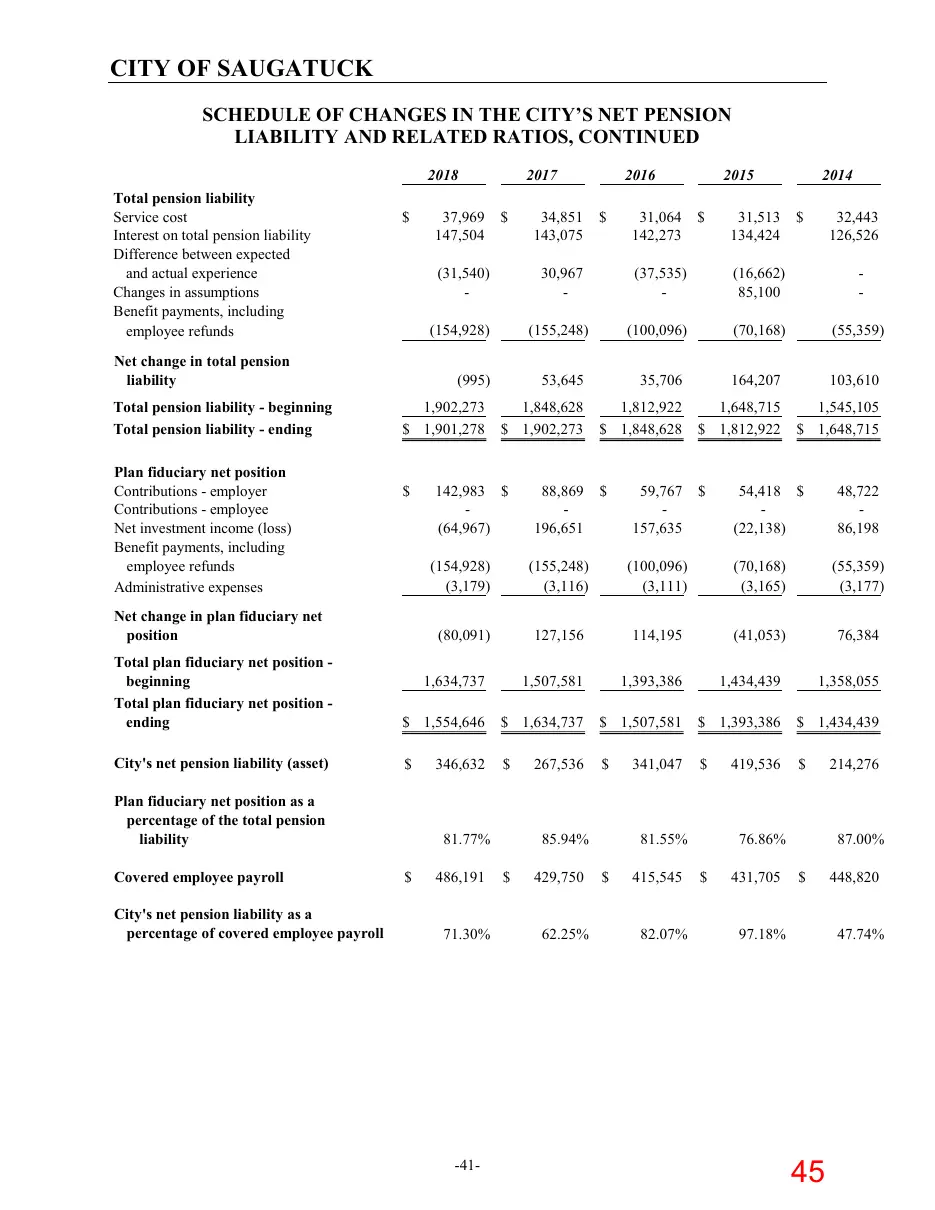
Text of page 45
CITY OF SAUGATUCK SCHEDULE OF CHANGES IN THE CITY’S NET PENSION LIABILITY AND RELATED RATIOS, CONTINUED 2018 Total pension liability Service cost Interest on total pension liability Difference between expected and actual experience Changes in assumptions Benefit payments, including employee refunds
Plan fiduciary net position Contributions - employer Contributions - employee Net investment income (loss) Benefit payments, including employee refunds Administrative expenses
34,851 143,075
2016 $
31,064 142,273
2015 $
31,513 134,424
2014 $
32,443 126,526
(31,540) -
30,967 -
(37,535) -
(16,662) 85,100
(154,928)
(155,248)
(100,096)
(70,168)
(55,359)
(995)
53,645
35,706
164,207
103,610
1,902,273 $ 1,901,278
1,848,628 $ 1,902,273
1,812,922 $ 1,848,628
1,648,715 $ 1,812,922
1,545,105 $ 1,648,715
Net change in total pension liability
Total pension liability - beginning Total pension liability - ending
37,969 147,504
2017
Net change in plan fiduciary net position
142,983 $ (64,967)
88,869 196,651
(154,928) (3,179)
(155,248) (3,116)
(80,091)
59,767 157,635
54,418 $ (22,138)
48,722 86,198
(100,096) (3,111)
(70,168) (3,165)
(55,359) (3,177)
127,156
114,195
(41,053)
76,384
Total plan fiduciary net position beginning Total plan fiduciary net position ending
1,634,737
1,507,581
1,393,386
1,434,439
1,358,055
$ 1,554,646
$ 1,634,737
$ 1,507,581
$ 1,393,386
$ 1,434,439
City's net pension liability (asset)
Plan fiduciary net position as a percentage of the total pension liability Covered employee payroll City's net pension liability as a percentage of covered employee payroll
346,632
81.77% $
486,191
71.30%
-41-
267,536
85.94% $
429,750
62.25%
341,047
81.55% $
415,545
82.07%
419,536
76.86% $
431,705
214,276
87.00% $
97.18%
448,820
47.74%
Page 46
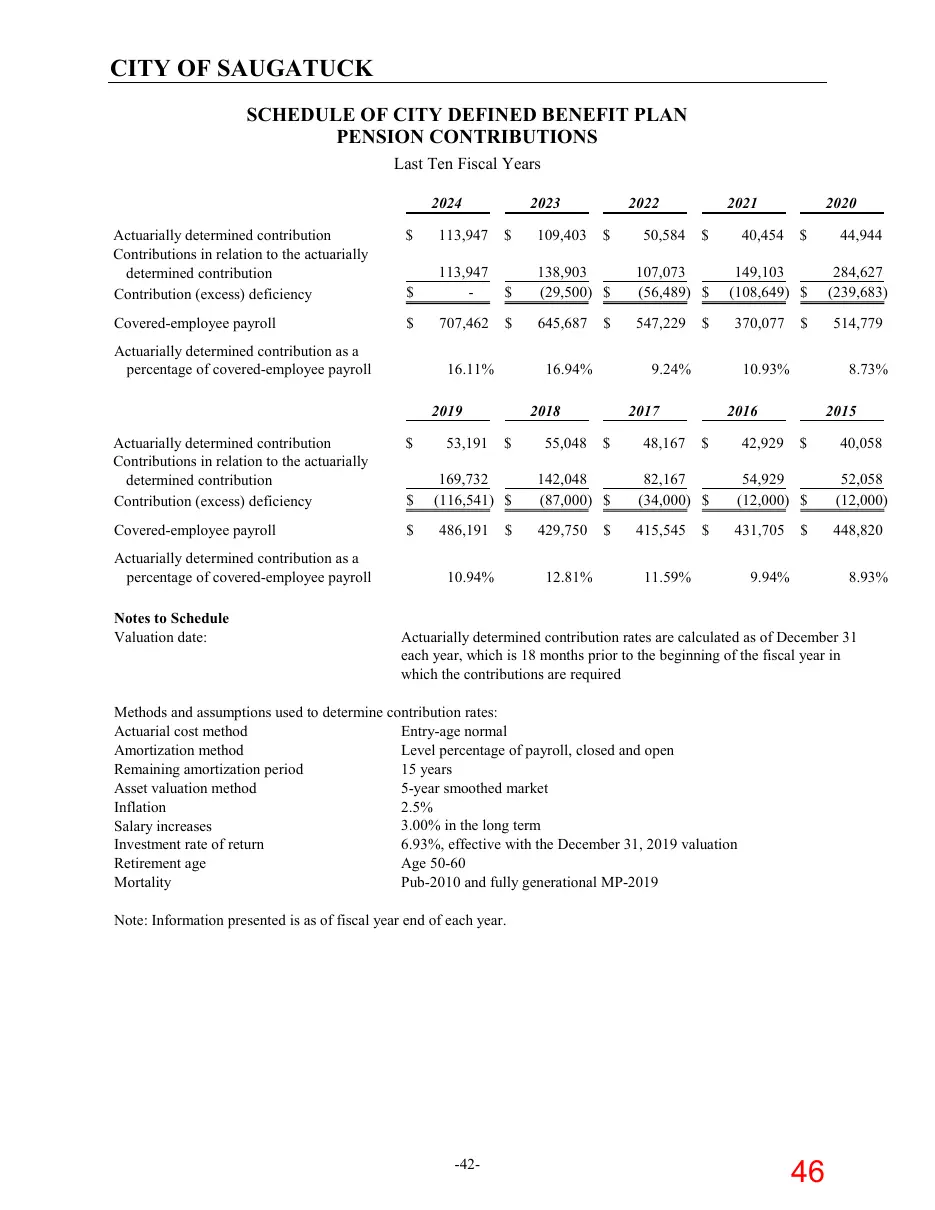
Text of page 46
CITY OF SAUGATUCK SCHEDULE OF CITY DEFINED BENEFIT PLAN PENSION CONTRIBUTIONS Last Ten Fiscal Years 2024
2023
2022
Actuarially determined contribution Contributions in relation to the actuarially determined contribution Contribution (excess) deficiency
113,947
109,403
113,947 -
138,903 (29,500) $
Covered-employee payroll
707,462
645,687
Actuarially determined contribution as a percentage of covered-employee payroll
16.11%
16.94%
53,191
169,732 (116,541) $
142,048 (87,000) $
Covered-employee payroll
486,191
429,750
Notes to Schedule Valuation date:
10.94%
55,048
12.81%
44,944
107,073 (56,489) $
149,103 (108,649) $
284,627 (239,683)
547,229
370,077
514,779
40,454
2020 $
48,167
10.93%
2017
Actuarially determined contribution Contributions in relation to the actuarially determined contribution Contribution (excess) deficiency
Actuarially determined contribution as a percentage of covered-employee payroll
9.24%
2018
2019
50,584
2021
8.73%
2016 $
40,058
82,167 (34,000) $
54,929 (12,000) $
52,058 (12,000)
415,545
431,705
448,820
42,929
2015
11.59%
9.94%
8.93%
Actuarially determined contribution rates are calculated as of December 31 each year, which is 18 months prior to the beginning of the fiscal year in which the contributions are required
Methods and assumptions used to determine contribution rates: Actuarial cost method Entry-age normal Amortization method Level percentage of payroll, closed and open Remaining amortization period 15 years 5-year smoothed market Asset valuation method 2.5% Inflation 3.00% in the long term Salary increases 6.93%, effective with the December 31, 2019 valuation Investment rate of return Age 50-60 Retirement age Pub-2010 and fully generational MP-2019 Mortality Note: Information presented is as of fiscal year end of each year.
-42-
Page 47
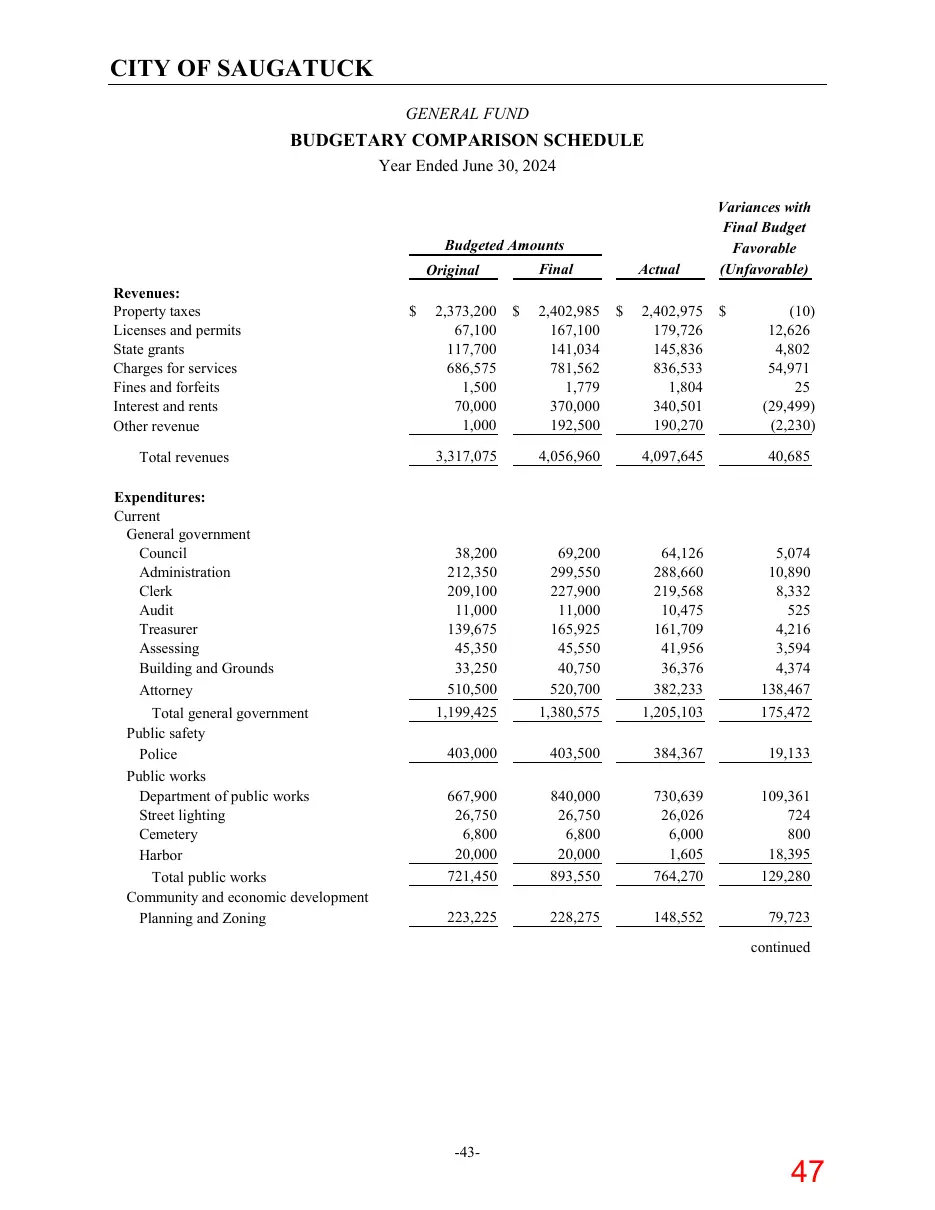
Text of page 47
CITY OF SAUGATUCK GENERAL FUND
BUDGETARY COMPARISON SCHEDULE Year Ended June 30, 2024
Budgeted Amounts Final
Original Revenues: Property taxes Licenses and permits State grants Charges for services Fines and forfeits Interest and rents Other revenue Total revenues Expenditures: Current General government Council Administration Clerk Audit Treasurer Assessing Building and Grounds Attorney Total general government Public safety Police Public works Department of public works Street lighting Cemetery Harbor Total public works Community and economic development Planning and Zoning
2,373,200 67,100 117,700 686,575 1,500 70,000 1,000
2,402,985 167,100 141,034 781,562 1,779 370,000 192,500
Actual $
2,402,975 179,726 145,836 836,533 1,804 340,501 190,270
Variances with Final Budget Favorable (Unfavorable) $
(10) 12,626 4,802 54,971 25 (29,499) (2,230)
3,317,075
4,056,960
4,097,645
40,685
38,200 212,350 209,100 11,000 139,675 45,350 33,250 510,500 1,199,425
69,200 299,550 227,900 11,000 165,925 45,550 40,750 520,700 1,380,575
64,126 288,660 219,568 10,475 161,709 41,956 36,376 382,233 1,205,103
5,074 10,890 8,332 525 4,216 3,594 4,374 138,467 175,472
403,000
403,500
384,367
19,133
667,900 26,750 6,800 20,000 721,450
840,000 26,750 6,800 20,000 893,550
730,639 26,026 6,000 1,605 764,270
109,361 724 800 18,395 129,280
223,225
228,275
148,552
79,723 continued
-43-
Page 48
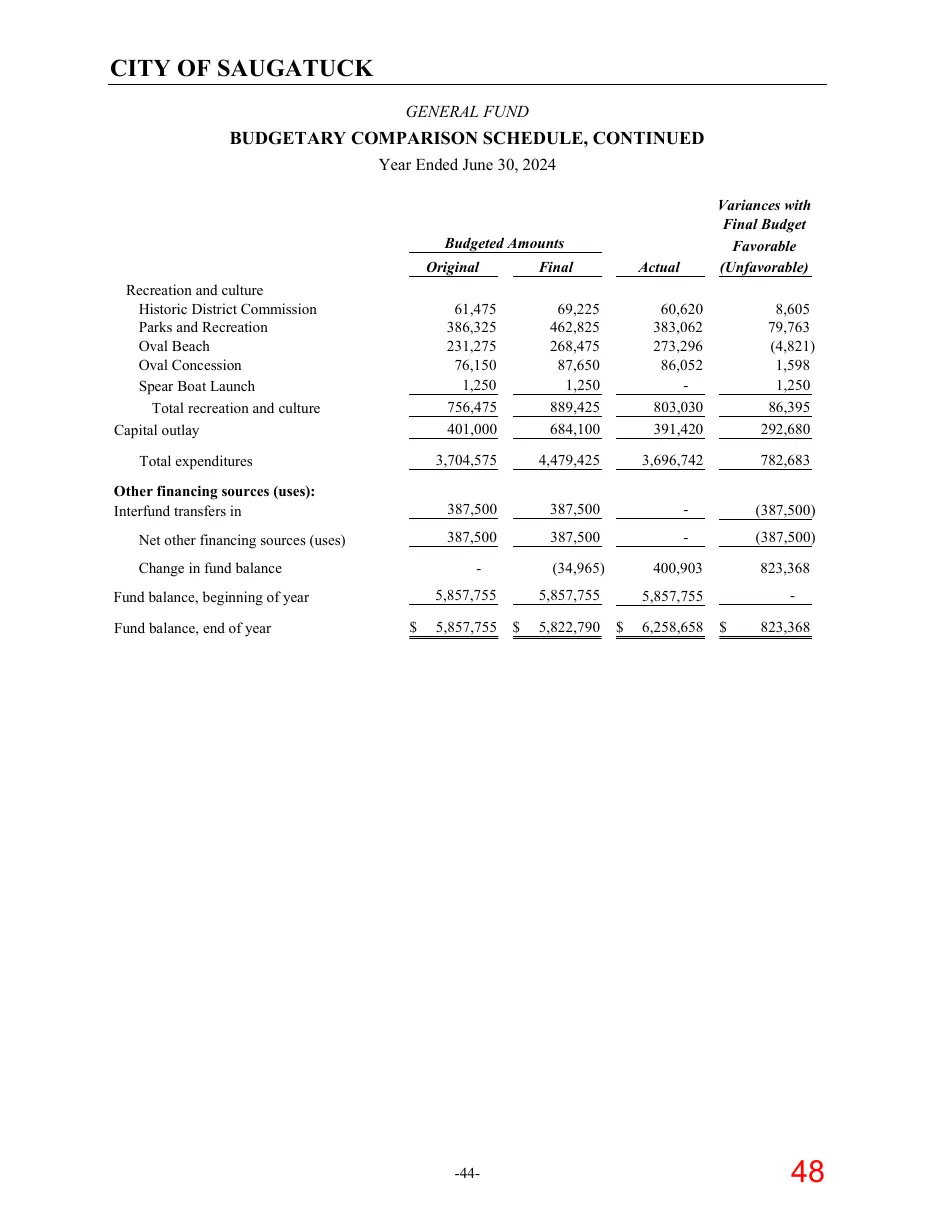
Text of page 48
CITY OF SAUGATUCK GENERAL FUND
BUDGETARY COMPARISON SCHEDULE, CONTINUED Year Ended June 30, 2024 Variances with Final Budget Favorable (Unfavorable)
Budgeted Amounts Final
Original Recreation and culture Historic District Commission Parks and Recreation Oval Beach Oval Concession Spear Boat Launch Total recreation and culture Capital outlay Total expenditures Other financing sources (uses): Interfund transfers in
Net other financing sources (uses) Change in fund balance
Fund balance, end of year
61,475 386,325 231,275 76,150 1,250 756,475 401,000
69,225 462,825 268,475 87,650 1,250 889,425 684,100
60,620 383,062 273,296 86,052 803,030 391,420
8,605 79,763 (4,821) 1,598 1,250 86,395 292,680
3,704,575
4,479,425
3,696,742
782,683
387,500
387,500
(387,500)
387,500
387,500
(387,500)
(34,965)
400,903
823,368
5,857,755
5,857,755
5,857,755
Fund balance, beginning of year $
Actual
5,857,755
-44-
5,822,790
6,258,658
823,368
Page 49
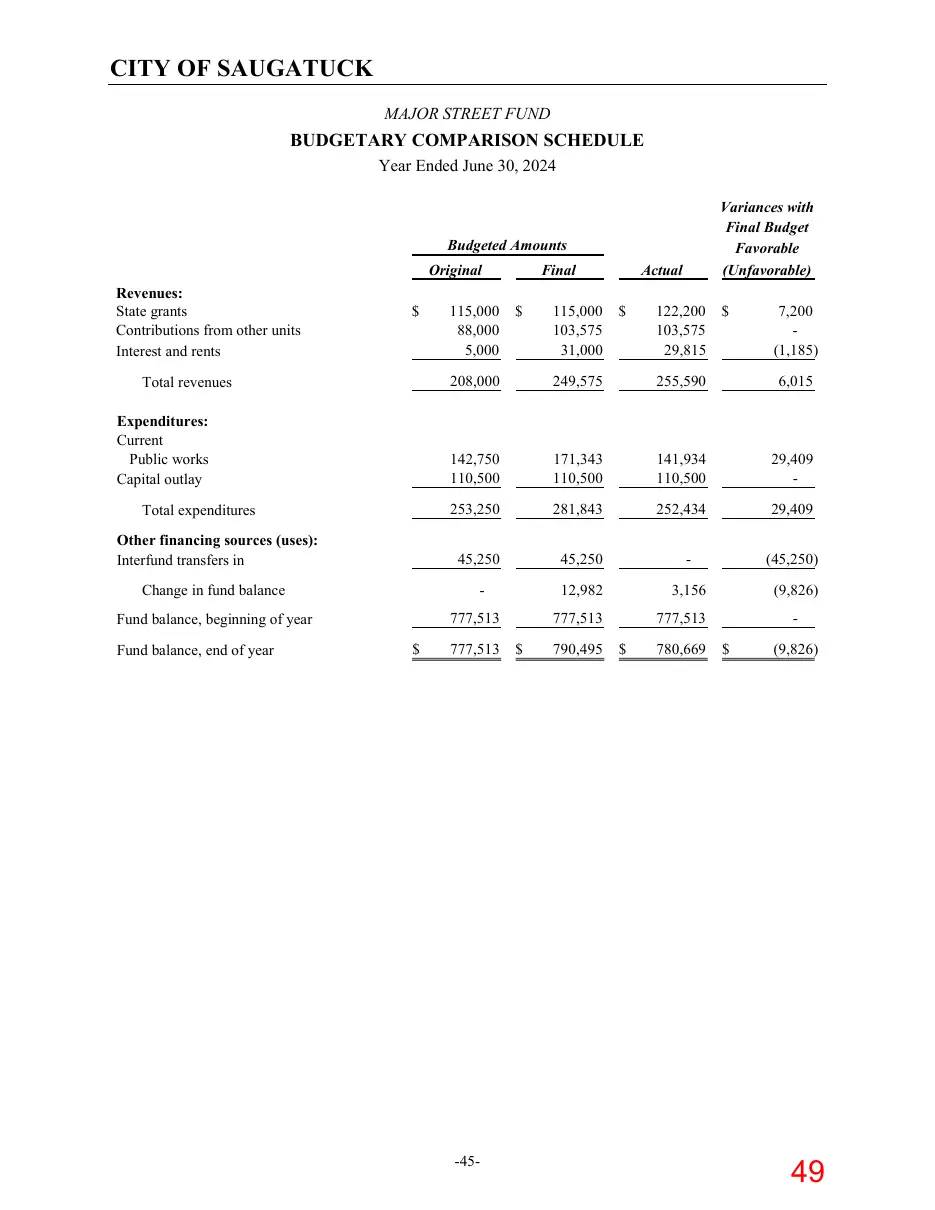
Text of page 49
CITY OF SAUGATUCK MAJOR STREET FUND
BUDGETARY COMPARISON SCHEDULE Year Ended June 30, 2024 Variances with Final Budget Favorable (Unfavorable)
Budgeted Amounts Final
Original Revenues: State grants Contributions from other units Interest and rents
115,000 88,000 5,000
115,000 103,575 31,000
Actual $
122,200 103,575 29,815
7,200 (1,185)
208,000
249,575
255,590
6,015
142,750 110,500
171,343 110,500
141,934 110,500
29,409 -
253,250
281,843
252,434
29,409
Other financing sources (uses): Interfund transfers in
45,250
45,250
(45,250)
Change in fund balance
12,982
3,156
(9,826)
Fund balance, beginning of year
777,513
777,513
777,513
Total revenues Expenditures: Current Public works Capital outlay Total expenditures
Fund balance, end of year
777,513
-45-
790,495
780,669
(9,826)
Page 50
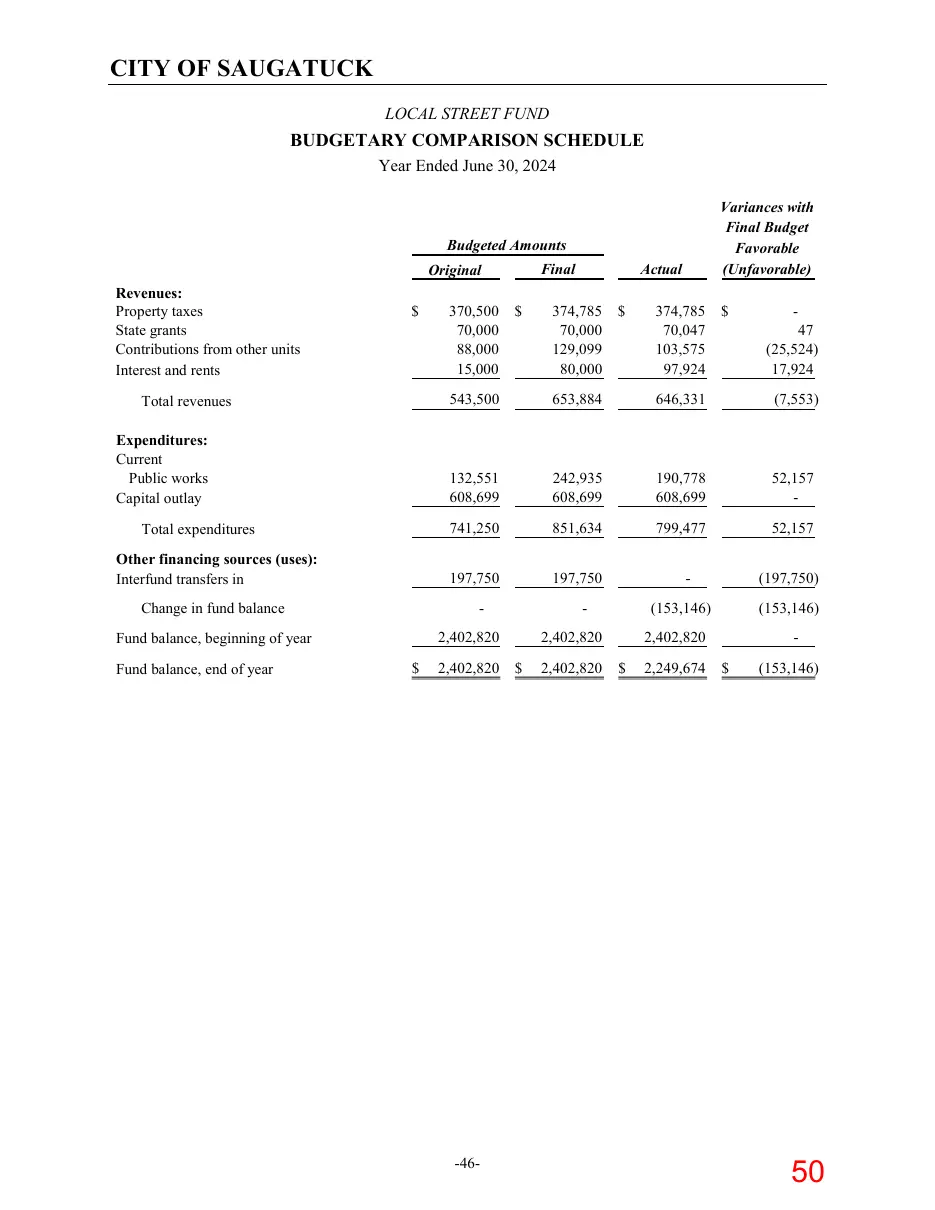
Text of page 50
CITY OF SAUGATUCK LOCAL STREET FUND
BUDGETARY COMPARISON SCHEDULE Year Ended June 30, 2024 Variances with Final Budget Favorable (Unfavorable)
Budgeted Amounts Final
Original Revenues: Property taxes State grants Contributions from other units Interest and rents
370,500 70,000 88,000 15,000
Actual
374,785 70,000 129,099 80,000
374,785 70,047 103,575 97,924
47 (25,524) 17,924
543,500
653,884
646,331
(7,553)
132,551 608,699
242,935 608,699
190,778 608,699
52,157 -
741,250
851,634
799,477
52,157
Other financing sources (uses): Interfund transfers in
197,750
197,750
(197,750)
Change in fund balance
(153,146)
(153,146)
2,402,820
Total revenues Expenditures: Current Public works Capital outlay Total expenditures
Fund balance, end of year
2,402,820
2,402,820
Fund balance, beginning of year $
2,402,820
-46-
2,402,820
2,249,674
(153,146)
Page 51
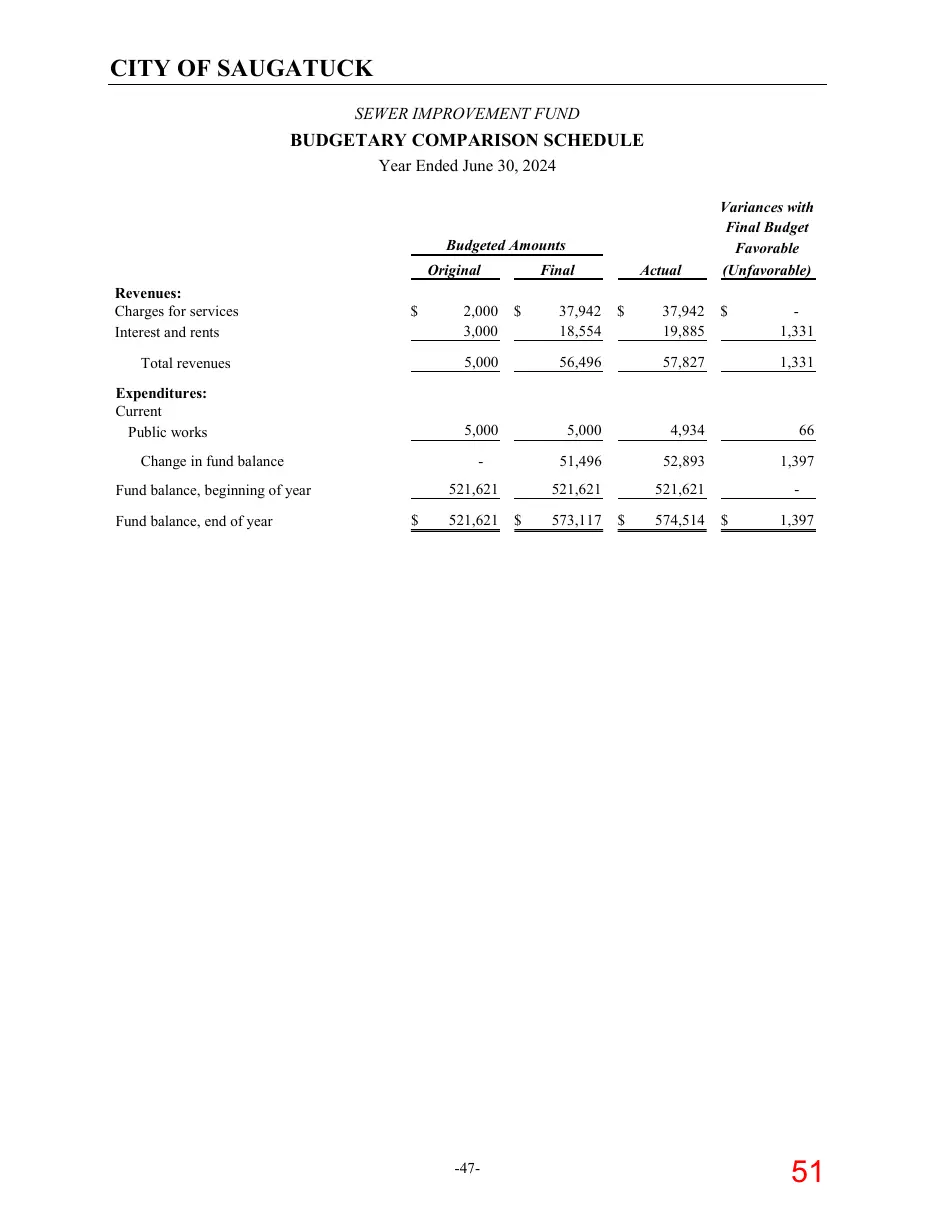
Text of page 51
CITY OF SAUGATUCK SEWER IMPROVEMENT FUND
BUDGETARY COMPARISON SCHEDULE Year Ended June 30, 2024
Budgeted Amounts Final
Original Revenues: Charges for services Interest and rents
2,000 3,000
37,942 18,554
Actual $
37,942 19,885
Variances with Final Budget Favorable (Unfavorable) $
1,331
5,000
56,496
57,827
1,331
5,000
5,000
4,934
Change in fund balance
51,496
52,893
1,397
Fund balance, beginning of year
521,621
521,621
521,621
Total revenues Expenditures: Current Public works
Fund balance, end of year
521,621
-47-
573,117
574,514
1,397
Page 52
Text of page 52
SUPPLEMENTARY INFORMATION
Page 53
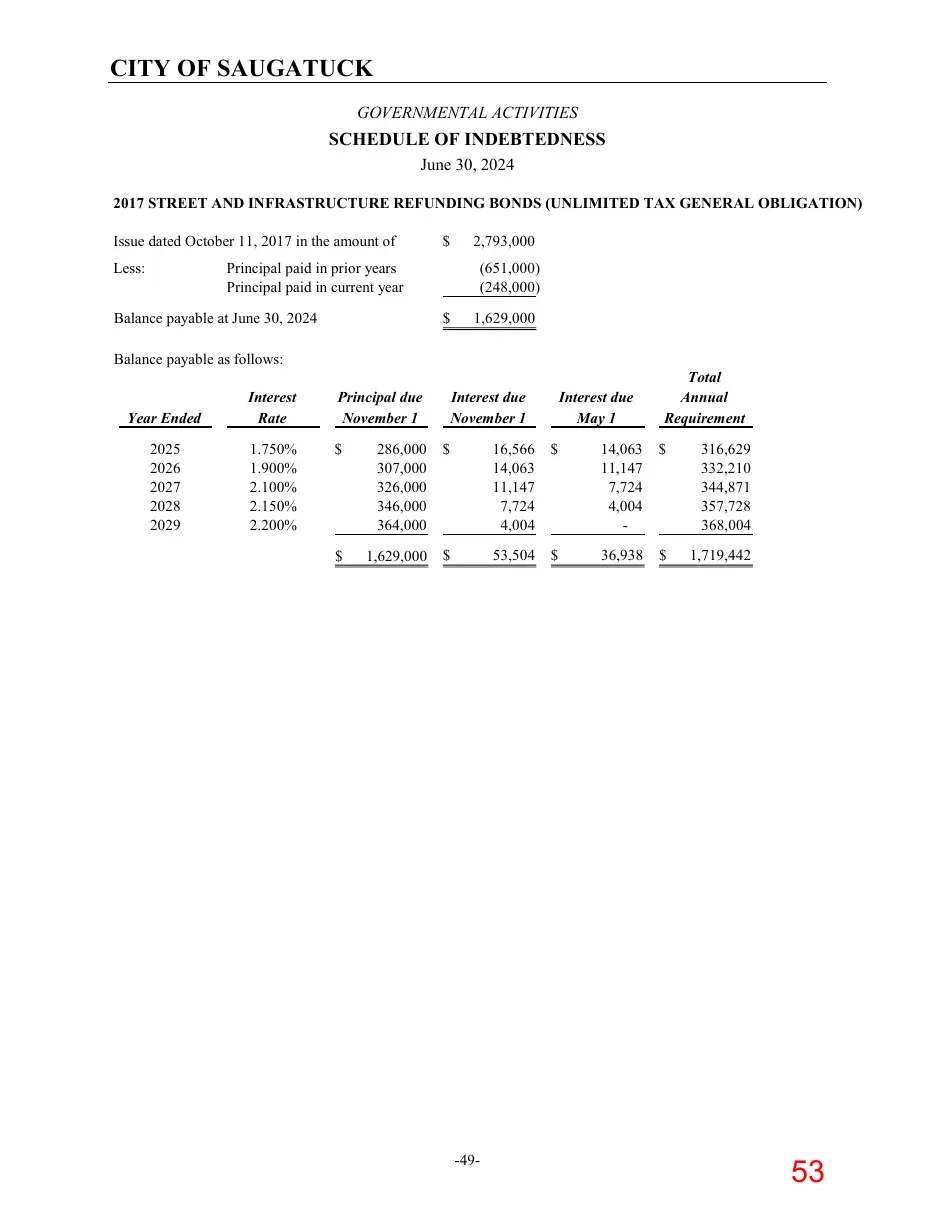
Text of page 53
CITY OF SAUGATUCK GOVERNMENTAL ACTIVITIES
SCHEDULE OF INDEBTEDNESS June 30, 2024 2017 STREET AND INFRASTRUCTURE REFUNDING BONDS (UNLIMITED TAX GENERAL OBLIGATION) Issue dated October 11, 2017 in the amount of Less:
2,793,000
Principal paid in prior years Principal paid in current year
Balance payable at June 30, 2024
(651,000) (248,000) $
1,629,000
Balance payable as follows: Interest due November 1
Year Ended
Principal due November 1
2025 2026 2027 2028 2029
1.750% 1.900% 2.100% 2.150% 2.200%
286,000 307,000 326,000 346,000 364,000
16,566 14,063 11,147 7,724 4,004
14,063 11,147 7,724 4,004 -
316,629 332,210 344,871 357,728 368,004
1,629,000
53,504
36,938
1,719,442
-49-
Interest due May 1
Total Annual Requirement
Interest Rate