Council Agenda item 14B
Audit Engagement Letter/Proposal for 2025, 2026, and 2027. (Roll Call)
City Council, Monday, January 27, 2025
Download these 10 pages, 1.0 MB Whole packet, 76 pages, 14.0 MB
Page 37
Text of page 37
City Council Agenda Item Report FROM: Nicole Bredeweg MEETING DATE: January 27, 2025 SUBJECT: Audit Engagement Letters DESCRIPTION: Included is the audit engagement letter submitted by the current accountants, Berthiaume & Company, as well as a brief single audit quote, should such be necessary. SAMPLE MOTION: Motion to approve the audit engagement letter with Berthiaume & Company for 2025, 2026, and 2027.
Page 38
Text of page 38
December 30, 2024 Ryan Cummins, Manager Nicole Bredeweg, Treasurer City of Saugatuck 102 Butler Street P.O. Box 86 Saugatuck, MI 49453
RE:
Audit Engagement Letter for 2025, 2026 and 2027
Dear Nicole: The 2024 audit was the last period for which we were previously engaged to provide audit services. So that we may continue to help the City with this requirement, I have attached the audit engagement letter / proposal for the upcoming years ended June 30, 2025, 2026, and 2027. The proposed fees reflect the increased requirements of new GASB accounting and audit standards. The proposed amount also is based on our recent records of the time and costs required to perform a quality audit for the City. Your understanding in this matter is appreciated. If accepted / approved, please sign both copies and return one to me. We appreciate the opportunity to serve as City auditors. Sincerely,
Kenneth Berthiaume Certified Public Accountant Berthiaume & Company KAB/ceb
Page 39
Text of page 39
December 30, 2024 Ryan Cummins, Manager Nicole Bredeweg, Treasurer City of Saugatuck 102 Butler Street P.O. Box 86 Saugatuck, MI 49453
ENGAGEMENT LETTER FOR 2025, 2026 AND 2027 We are pleased to confirm our understanding of the services we are to provide to City of Saugatuck for the years ended June 30, 2025, 2026 and 2027. Audit Scope and Objectives We will audit the financial statements of the governmental activities, and each major fund, and the remaining fund information and the disclosures, which collectively comprise the basic financial statements of City of Saugatuck as of and for the years ended June 30, 2025, 2026 and 2027. Accounting standards generally accepted in the United States of America (GAAS) provide for certain required supplementary information (RSI), such as management’s discussion and analysis (MD&A), to supplement City of Saugatuck’s basic financial statements, is required by the Governmental Accounting Standards Board who considers it to be an essential part of financial reporting for placing the basic financial statements in an appropriate operational, economic, or historical context. As part of our engagement, we will apply certain limited procedures to City of Saugatuck’s RSI in accordance with GAAS. These limited procedures will consist of inquiries of management regarding the methods of preparing the information and comparing the information for consistency with management’s responses to our inquiries, the basic financial statements, and other knowledge we obtained during our audit of the basic financial statements. We will not express an opinion or provide any assurance on the information because the limited procedures do not provide us with sufficient evidence to express an opinion or provide any assurance. The following RSI is required by U.S. generally accepted accounting principles (GAAP) and will be subjected to certain limited procedures, but will not be audited. 1) Management’s Discussion and Analysis 2) Budgetary Comparison Schedules 3) Schedule of Changes in the City’s Net Pension Liability and Related Ratios 4) Schedule of City Defined Benefit Plan Pension Contributions
Page 40
Text of page 40
We may also be engaged to report on supplementary information other than RSI that accompanies City of Saugatuck’s financial statements. We will subject the supplementary information, if any, to the auditing procedures applied in our audit of the financial statements and certain additional procedures, including comparing and reconciling such information directly to the underlying accounting and other records used to prepare the financial statements or to the financial statements themselves, and other additional procedures in accordance with GAAS, and we will provide an opinion on it in relation to the financial statements as a whole in a separate written report accompanying our auditor’s report on the financial statements. The objectives of our audit are to obtain reasonable assurance as to whether the financial statements as a whole are free from material misstatement, whether due to fraud or error, issue an auditor’s report that includes our opinion about whether your financial statements are fairly presented, in all material respects, in conformity with GAAP, and report on the fairness of the supplementary information referred to in the second paragraph when considered in relation to the financial statements as a whole. Reasonable assurance is a high level of assurance but is not absolute assurance and therefore is not a guarantee that an audit conducted in accordance with GAAS will always detect a material misstatement when it exists. Misstatements, including omissions, can arise from fraud or error and are considered material if there is a substantial likelihood that individually or in the aggregate, they would influence the judgment of a reasonable user made based on the financial statements. Auditor’s Responsibilities for the Audit of the Financial Statements We will conduct our audit in accordance with GAAS and will include tests of your accounting records and other procedures we consider necessary to enable us to express such opinions. As part of an audit in accordance with GAAS, we exercise professional judgment and maintain professional skepticism throughout the audit. We will evaluate the appropriateness of accounting policies used and the reasonableness of significant accounting estimates made by management. We will also evaluate the overall presentation of the financial statements, including the disclosures, and determine whether the financial statements represent the underlying transactions and events in a manner that achieves fair presentation. We will plan and perform the audit to obtain reasonable assurance about whether the financial statements are free of material misstatement, whether from (1) errors, (2) fraudulent financial reporting, (3) misappropriation of assets, or (4) \violations of laws or governmental regulations that are attributable to the government or to acts by management or employees acting on behalf of the government. Because of the inherent limitations of an audit, combined with the inherent limitations of internal control, and because we will not perform a detailed examination of all transactions, there is an unavoidable risk that some material misstatements may not be detected by us, even though the audit is properly planned and performed in accordance with GAAS. In addition, an audit is not designed to detect immaterial misstatements or violations of laws or governmental regulations that do not have a direct and material effect on the financial statements. However, we will inform the appropriate level of management of any material errors, fraudulent financial
Page 41
Text of page 41
statements, or misappropriation of assets that comes to our attention. We will also inform the appropriate level of management of any violations of laws or governmental regulations that come to our attention, unless clearly inconsequential. Our responsibility, as auditors, is limited to the period covered by our audit and does not extend to any later periods for which we are not engaged as auditors. We will also conclude, based on the audit evidence obtained, whether there are conditions or events, considered in the aggregate, that raise substantial doubt about the government’s ability to continue as a going concern for a reasonable period of time. Our procedures may include tests of documentary evidence supporting the transactions recorded in the accounts, tests of the physical existence of inventories, and direct confirmation of receivables and certain assets and liabilities by correspondence with selected customers, creditors, and financial institutions. We may also request written representations from your attorneys as part of the engagement. We may, from time to time and depending on the circumstances, use third-party service providers in serving your account. We may share confidential information about you with these service providers but remain committed to maintaining the confidentiality and security of your information. Accordingly, we maintain internal policies, procedures, and safeguards to protect the confidentiality of your personal information. In addition, we will secure confidentiality agreements with all service providers to maintain the confidentiality of your information and we will take reasonable precautions to determine that they have appropriate procedures in place to prevent the unauthorized release of your confidential information to others. In the event that we are unable to secure an appropriate confidentiality agreement, you will be asked to provide your consent prior to the sharing of your confidential information with the third-party service provider. Furthermore, we will remain responsible for the work provided by any such third-party service providers. Our audit of the financial statements does not relieve you of your responsibilities. Audit Procedures—Internal Control We will obtain an understanding of the government and its environment, including internal control relevant to the audit, sufficient to identify and assess the risks of material misstatement of the financial statements, whether due to error or fraud, and to design and perform audit procedures responsive to those risks and obtain evidence that is sufficient and appropriate to provide a basis for our opinions. The risk of not detecting a material misstatement resulting from fraud is higher than for one resulting from error, as fraud may involve collusion, forgery, intentional omissions, misrepresentation or the override of internal control. An audit is not designed to provide assurance on internal control or to identify deficiencies in internal control. Accordingly, we will express no such opinion. However, during the audit, we will communicate to management and those charged with governance internal control related matters that are required to be communicated under AICPA professional standards.
Page 42
Text of page 42
According to GAAS, significant risks include management override of controls, and GAAS presumes that revenue recognition is a significant risk. Accordingly, we have considered these as significant risks. We have identified the following other significant risk(s) of material misstatement as part of our audit planning: • Cash receipts from Oval Beach parking and concessions. Audit Procedures—Compliance As part of obtaining reasonable assurance about whether the financial statements are free of material misstatement, we will perform tests of City of Saugatuck’s compliance with the provisions of applicable laws, regulations, contracts, and agreements. However, the objective of our audit will not be to provide an opinion on overall compliance and we will not express such an opinion. Responsibilities of Management for the Financial Statements Our audit will be conducted on the basis that you acknowledge and understand your responsibility for designing, implementing, and maintaining internal controls relevant to the preparation and fair presentation of financial statements that are free from material misstatement, whether due to fraud or error, including monitoring ongoing activities, for the selection and application of accounting principles, and for the preparation and fair presentation of the financial statements in conformity with accounting principles generally accepted in the United States of America with the oversight of those charged with governance. Management is responsible for making drafts of financial statements, all financial records, and related information available to us and for the accuracy and completeness of that information (including information from outside of the general and subsidiary ledgers). You are also responsible for providing us with (1) access to all information of which you are aware that is relevant to the preparation and fair presentation of the financial statements, such as records, documentation, identification of all related parties and all related-party relationships and transactions, and other matters, (2) additional information that we may request for the purpose of the audit, and (3) unrestricted access to persons within the government from whom we determine it necessary to obtain audit evidence. At the conclusion of our audit, we will require certain written representations from you about the financial statements and related matters. Your responsibilities include adjusting the financial statements to correct material misstatements and confirming to us in the management representation letter that the effects of any uncorrected misstatements aggregated by us during the current engagement and pertaining to the latest period presented are immaterial, both individually and in the aggregate, to the financial statements of each opinion unit taken as a whole. You are responsible for the design and implementation of programs and controls to prevent and detect fraud, and for informing us about all known or suspected fraud affecting the government involving (1) management, (2) employees who have significant roles in internal control, and (3)
Page 43
Text of page 43
others where the fraud could have a material effect on the financial statements. Your responsibilities include informing us of your knowledge of any allegations of fraud or suspected fraud affecting the government received in communications from employees, former employees, grantors, regulators, or others. In addition, you are responsible for identifying and ensuring that the government complies with applicable laws and regulations. You are responsible for the preparation of the supplementary information in conformity with accounting principles generally accepted in the United States of America. You agree to include our report on the supplementary information in any document that contains, and indicates that we have reported on, the supplementary information. You also agree to include the audited financial statements with any presentation of the supplementary information that includes our report thereon OR make the audited financial statements readily available to users of the supplementary information no later than the date the supplementary information is issued with our report thereon. Your responsibilities include acknowledging to us in the representation letter that (1) you are responsible for presentation of the supplementary information in accordance with GAAP; (2) you believe the supplementary information, including its form and content, is fairly presented in accordance with GAAP; (3) the methods of measurement or presentation have not changed from those used in the prior period (or, if they have changed, the reasons for such changes); and (4) you have disclosed to us any significant assumptions or interpretations underlying the measurement or presentation of the supplementary information. Other Services We will prepare the financial statements of City of Saugatuck in conformity with accounting principles generally accepted in the United States of America based on information provided by you. We will perform the services in accordance with applicable professional standards. The other services are limited in the financial statement services previously defined. We, in our sole professional judgment, reserve the right to refuse to perform any procedure or take any action that could be construed as assuming management responsibilities. You agree to assume all management responsibilities for the financial statement preparation services and any other non-attest services we provide, oversee the services by designating an individual, preferably from senior management, with suitable skill, knowledge, or experience, evaluate the adequacy and results of the services, and accept responsibility for them. Engagement Administration, Fees and Other We understand that your employees will prepare all cash, accounts receivable, or other confirmations we request and will locate any documents selected by us for testing. The audit documentation for this engagement is the property of Berthiaume & Company, Certified Public Accountants, and constitutes confidential information. However, subject to applicable laws and regulations, audit documentation and appropriate individuals will be made available upon request and in a timely manner to a State or Federal regulator or its designee. We
Page 44
Text of page 44
will notify you of any such request. If requested, access to such audit documentation will be provided under the supervision of Berthiaume & Company personnel. Furthermore, upon request, we may provide copies of selected audit documentation to the regulator or its designee. The regulator or its designee may intend or decide to distribute the copies or information contained therein to others, including other governmental agencies. Kenneth Berthiaume is the engagement partner and is responsible for supervising the engagement and signing the report or authorizing another individual to sign it. Our fee for these services will be as follows: For The Year Ended June 30, 2025……………………………………$11,900 For The Year Ended June 30, 2026……………………………………$12,300 For The Year Ended June 30, 2027……………………………………$12,700 The above fees are based on anticipated cooperation from your personnel and the assumption that unexpected circumstance will not be encountered during the audit. If significant additional time is necessary, we will discuss it with you and arrive at a new fee estimate before we incur the additional costs. Reporting We will issue a written report upon completion of our audit of City of Saugatuck’s financial statements. Our report will be addressed to the City Council of City of Saugatuck. Circumstances may arise in which our report may differ from its expected form and content based on the results of our audit. Depending on the nature of these circumstances, it may be necessary for us to modify our opinions or add an emphasis-of-matter or other-matter paragraph to our auditor’s report, or if necessary, withdraw from this engagement. If our opinions are other than unmodified, we will discuss the reasons with you in advance. If, for any reason, we are unable to complete the audit or are unable to form or have not formed opinions, we may decline to express opinions or withdraw from this engagement. We appreciate the opportunity to be of service to City of Saugatuck and believe this letter accurately summarized the significant terms of our engagement. If you have any questions, please let us know. If you agree with the terms of our engagement as described in this letter, please sign the attached copy and return it to us. Sincerely,
Kenneth A. Berthiaume, President Certified Public Accountant Berthiaume & Company KAB / ceb
Page 45
Text of page 45
RESPONSE: This letter correctly sets forth the understanding of the City of Saugatuck.
Management Signature:________________________________Date:______________________ Title:________________________________________
Governance Signature (City Council):_______________________________Date:____________ Title:________________________________________
Page 46
Text of page 46
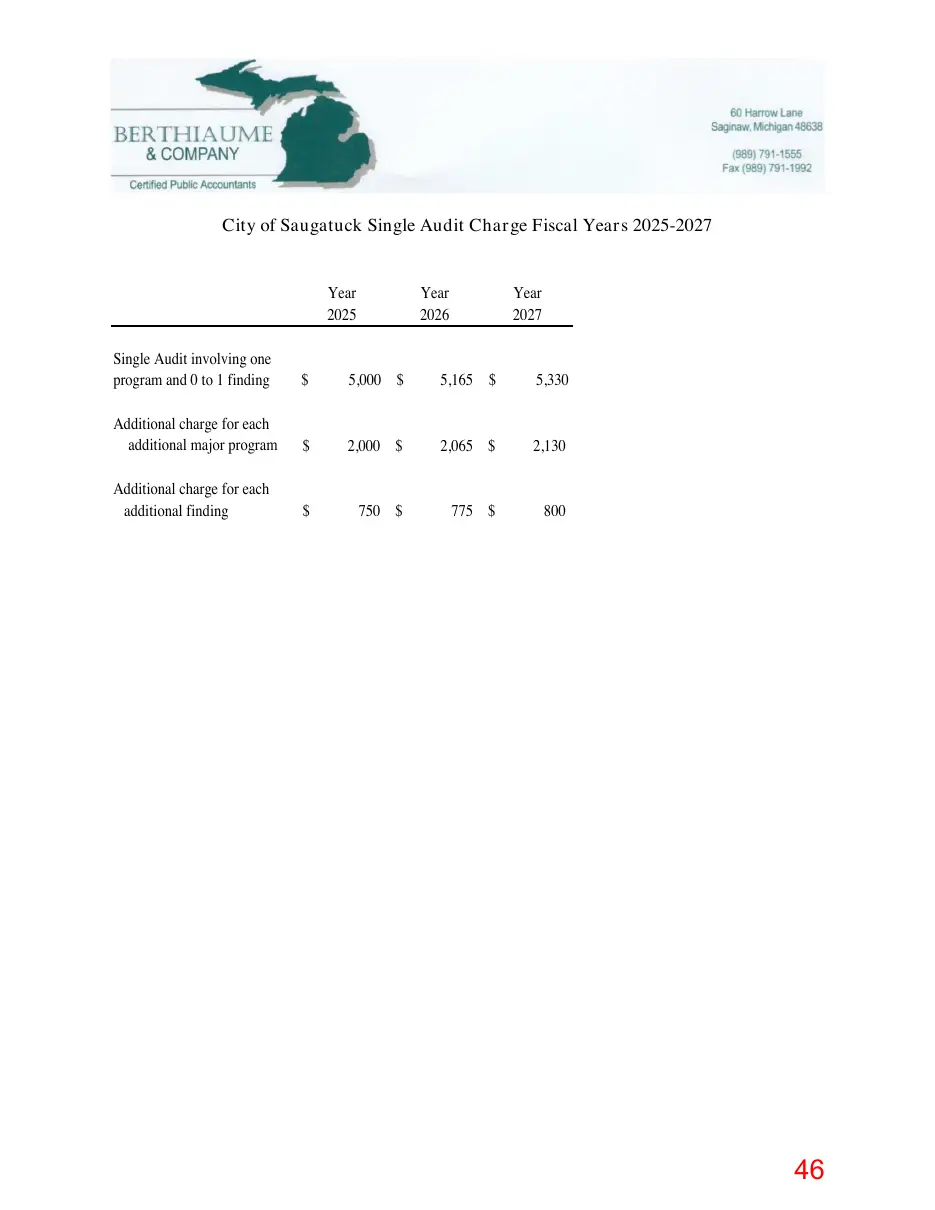
City of Saugatuck Single Audit Charge Fiscal Years 2025-2027
Year 2025
Year 2026
Year 2027
Single Audit involving one program and 0 to 1 finding
5,000 $
5,165 $
5,330
Additional charge for each additional major program
2,000 $
2,065 $
2,130
Additional charge for each additional finding
750 $
775 $